Category: Uncategorized

  • Buying vs Renting in Maryland: Which Is Better for Your Wealth in 2026?

    Buying vs Renting in Maryland: Which Is Better for Your Wealth in 2026?

    Deciding whether to sign another lease or commit to a 30-year mortgage is one of the biggest financial crossroads you’ll face. In 2026, the Maryland real estate market presents a unique set of challenges and opportunities. With home prices stabilizing and rental inventory shifting, the "right" choice depends on more than just your monthly payment: it’s about your long-term wealth strategy.

    At K-Stone Enterprises, we believe in providing the education you need to make an informed move. Whether you’re looking at a townhouse in Silver Spring, a single-family home in Bowie, or an apartment in downtown Baltimore, understanding the math behind your housing choice is the first step toward financial clarity.

    The 2026 Maryland Market Snapshot

    To understand the buy-vs-rent debate, we have to look at the current numbers. As of mid-2026, the Maryland housing market is characterized by tight inventory and steady demand.

    • Average Home Value: The typical Maryland home is currently valued at approximately $434,000. While we aren't seeing the double-digit surges of previous years, the market remains resilient with a modest 0.1% growth over the past twelve months.
    • Median Rent: If you’re looking to rent, the median price across the state is holding steady around $2,200 per month.
    • Inventory Trends: New listings have seen a significant dip: down about 22% compared to last year. This scarcity of homes for sale is keeping prices firm, even as buyer activity fluctuates.

    These figures tell us that Maryland is a "high-floor" market. It’s expensive to enter, but the lack of inventory provides a level of protection against significant price drops.

    🗳️ Poll: What's your move in 2026?

    The numbers are out — what's your gut telling you?

    A) I'm buying this year — ready to commit
    B) I'm renting for now — flexibility matters more
    C) I'm watching and waiting
    D) I already own — just here for the breakdown

    The Case for Renting: Flexibility and Liquidity

    Renting often gets a bad rap as "throwing money away," but in the 2026 economy, it can be a strategic move for many Marylanders.

    1. Short-Term Savings

    When you rent, your upfront costs are usually limited to a security deposit and the first month’s rent. Buying a home requires a down payment, closing costs (which can range from 2% to 5% of the purchase price), and immediate maintenance reserves. If you plan on living in an area for less than three years, the high transaction costs of buying usually outweigh any equity you might build.

    2. Maintenance Predictability

    In 2026, the cost of labor and materials for home repairs remains high. As a renter, your housing cost is the "ceiling": it’s the most you’ll pay each month. As a homeowner, your mortgage is the "floor": it’s the minimum you’ll pay, before factoring in a broken HVAC system or a leaking roof.

    3. Career Mobility

    Maryland’s economy is heavily influenced by federal agencies, healthcare, and tech. If your career might require a move to Northern Virginia or out of state within the next 24 months, the flexibility of a lease is invaluable.

    Conceptual illustration of rent receipts vs gold coin house equity

    The Case for Buying: Equity and Appreciation

    If you have a longer time horizon: specifically five years or more: the financial benefits of ownership in Maryland start to pull ahead.

    1. Forced Savings through Equity

    Every time you make a mortgage payment, a portion goes toward the principal. This is essentially a forced savings account. By 2031, a homeowner who bought in 2026 will have five years of principal paydown and five years of potential appreciation. A renter will have a collection of receipts.

    2. Long-Term Appreciation

    While 2025 and early 2026 saw flat growth, analysts project a return to a more sustainable 2% to 4% annual appreciation in Maryland. On a $434,000 home, a 3% annual increase adds over $13,000 to your net worth in the first year alone. Over a decade, that compounding growth is a primary driver of middle-class wealth in the U.S.

    3. Tax Advantages

    While you should always consult a tax professional, many homeowners still benefit from mortgage interest deductions and property tax deductions. These can significantly lower your effective monthly housing cost compared to a rent check that offers no tax relief.

    The 5-Year Break-Even Rule

    In the Maryland market, the "break-even" point is currently hovering around the 4.5 to 5-year mark.

    • Year 1-3: Renting is almost always cheaper. Between closing costs, moving expenses, and the interest-heavy early years of a mortgage, you are likely "in the red" compared to a renter.
    • Year 4: The lines begin to blur. Your equity is growing, and your "locked-in" mortgage payment is likely starting to look a lot better than the rising rents in your neighborhood.
    • Year 5 and Beyond: Ownership typically wins. As Maryland rents continue to climb (often 3-5% annually), your fixed-rate mortgage stays the same, and your equity continues to climb.

    Maryland real estate professional handing keys to a couple

    Factors to Consider Before Deciding

    If you are currently debating your next move, ask yourself these three questions:

    1. What is my "Stay-Put" Timeline? If you can’t commit to 5 years in your current city, renting is likely the safer financial play in 2026.
    2. Does the Math Work? Compare the total cost of ownership (mortgage + taxes + insurance + 1% annual maintenance) against the market rent for a similar property. In some parts of Maryland, the "buy" payment is currently 20% higher than the "rent" payment. You need to decide if that premium is worth the future equity.
    3. Is My Credit Ready? Interest rates in 2026 are stabilizing, but your credit score still dictates your "wealth-building" potential. A better rate means more of your money goes to your principal and less to the bank.

    The Maryland Advantage

    Maryland is unique because of its stable job market and geographic constraints. We aren't building "new land," and the proximity to D.C. ensures a constant floor of demand. Whether you choose to rent or buy, being part of this local economy is a smart move.

    However, the "right" home isn't just about the number of bedrooms; it's about how that property fits into your total financial picture. At K-Stone Enterprises, we specialize in helping Maryland residents navigate these exact decisions. We don't just look at a house; we look at a deal.

    Calculator, house key, and Maryland flag on a desk

    Next Steps: Get the Clarity You Need

    The market moves fast, and generic advice only goes so far. If you’ve found a property that has you curious: whether it’s one you want to rent or one you want to buy: let’s look at the specifics.

    There is no substitute for local data and a professional eye. We help our clients review the components of a potential deal: from neighborhood comps to estimated repair budgets: so you can move with confidence.

    Send me the property address or basic details and I’ll let you know what information would be needed for the next step.


    Tweet Draft for Sonny:
    Is 2026 the year to buy in Maryland or keep renting? 🏠 We’re breaking down the $434k median home value vs $2,200 median rent. Spoiler: The "5-year rule" is more important than ever. Read the full wealth-building breakdown here: [Link] #MarylandRealEstate #HomeBuyingTips #KStoneEnterprises


  • The Proven Bill Negotiation Framework: How to Lower Monthly Expenses Without Stress

    The Proven Bill Negotiation Framework: How to Lower Monthly Expenses Without Stress

    Do you ever look at your monthly bank statement and wonder where all the money went? You aren’t overspending on fancy dinners or high-end gadgets, yet your balance seems to dwindle faster every month.

    Welcome to the world of "Bill Creep."

    It starts with a $5 increase in your internet bill. Then, your cell phone provider adds a "regulatory recovery fee." Your streaming services hike their prices by $2, and suddenly, you’re paying $150 more per month than you were two years ago for the exact same services.

    Most people simply shrug and pay it. They assume that these costs are fixed, like gravity or taxes. But in 2026, the reality is that many of your recurring monthly expenses are more flexible than you think.

    I’m Lamont Milbourne, and at K-Stone Enterprises, we focus on providing financial education and clarity. I’m not a professional negotiator, but I act as a liaison to the information and resources that can help you take control of these "silent" expenses. Today, I’m sharing a proven framework to help you audit, benchmark, and negotiate your bills without the stress.

    The Psychology of the "Negotiation Nerves"

    Before we get into the how, we have to address the why. Why don't more people negotiate their bills?

    Usually, it's one of two things: time or fear.

    We live busy lives. Spending 45 minutes on hold with a cable company feels like a root canal without the anesthesia. There’s also the "Negotiation Nerves", the feeling that you're being "cheap" or the fear that the person on the other end will simply say "no" and make things awkward.

    Here’s the shift: You aren't asking for a favor. You are a customer in a highly competitive market. In 2026, companies like Comcast, Verizon, and Geico spend billions of dollars every year just to acquire a new customer. It is significantly cheaper for them to give you a $20 discount than it is for them to lose you and have to find someone to replace you.

    When you call, you aren't begging. You are providing them with an opportunity to keep your business.

    A confident person on the phone, managing their finances with a smile.

    The 5-Step Bill Negotiation Framework

    If you want to see results, you need a system. Randomly calling your electric company won't work (utilities are often regulated and non-negotiable), but targeting the right providers with the right data will.

    Step 1: The Deep Audit (The "Shred" List)

    Don’t just glance at your banking app. Log in to your actual accounts for the following services:

    • Cell Phone
    • Internet / Fiber
    • Home Security
    • Pest Control
    • Cable / Satellite TV
    • Auto & Renters Insurance

    Look for "junk fees" or services you don't use. Are you paying for a "premium" data plan when you're on Wi-Fi 90% of the time? Are you paying for "equipment rental" for a router you could buy yourself for $80? Highlight these items.

    Step 2: The Market Benchmark

    Knowledge is your only leverage. Before you call Provider A, you need to know what Provider B is offering to new customers.

    • Check "New Customer" deals: Look at your own provider’s website as if you were a new customer. If they are offering the same speed for $40 less, that is your baseline.
    • Competitor Rates: Check sites like the FCC's Consumer Guide or local comparison tools to see what the going rate is for your area.

    Step 3: The Script (Tone is Everything)

    When you call, your goal is to get to the "Retention Department." The first person who answers is usually a general customer service rep with limited power to give discounts.

    What to say:
    "Hi, I’m looking at my budget for the month and I noticed my bill has increased significantly. I’ve been a loyal customer for [X] years, but I’m seeing much better rates from [Competitor] for the same service. I’d like to stay with you, but I need to get this bill down to a more competitive level. Is there a loyalty discount or a better plan available, or should I speak with the cancellation department?"

    The Magic Phrase: "I’d like to stay, but I need a more affordable option." This tells them you are a "warm" lead: they don't want to lose you, and you've given them the "why."

    Step 4: The Retention Pivot

    If the first rep says they can't help, politely ask to speak with the "Retention" or "Account Management" department. These individuals are literally paid to keep you from leaving. They have access to "save desks" and promotional codes that standard reps don't.

    Be firm but incredibly polite. People are more likely to help someone who is kind than someone who is screaming.

    Step 5: The Maintenance Cycle

    Negotiating a bill isn't a one-and-done event. Promotions expire. "Introductory rates" disappear after 12 months.
    Put a recurring reminder in your calendar every 6 months to review your "Big 5" bills. Staying on top of this ensures that "Bill Creep" never has a chance to take root again.

    Floating money graphic representing the potential savings found through better financial management.

    Which Bills Are Actually Negotiable?

    Not all bills are created equal. You likely can't negotiate your water bill or your property taxes, but according to consumer data, households that actively negotiate can often see 10–30% reductions in certain categories.

    1. Internet & Cable: These are the "Big Fish." With 5G home internet and fiber expanding, competition is fierce.
    2. Cell Phone Plans: Often, just switching to a newer plan (even with the same company) can save you money because older plans are frequently more expensive.
    3. Insurance (Auto/Home): While you don't "negotiate" the rate like a phone bill, you can negotiate the terms. Asking for a higher deductible or a "safe driver" discount can drastically lower your premium.
    4. Satellite Radio / Subscriptions: These companies are notorious for offering 50–70% discounts the moment you threaten to cancel.

    The Advantage of Professional Resources

    I know what you're thinking: "Lamont, this sounds great, but I don't have three hours this week to sit on hold."

    I get it. That’s where the power of modern financial resources comes in. Part of the MWR Financial membership includes access to experts who can actually do this heavy lifting for you. They review your bills, contact the providers, and negotiate on your behalf.

    As a Marketing Director, I’m here to point you toward these tools. I don't guarantee that you'll save $100 or $1,000, but I do know that most people are leaving money on the table simply because they don't have the time or the "script" to ask for it.

    Education is the first step toward financial clarity. When you stop viewing your monthly bills as "fixed" and start viewing them as "contracts," your entire perspective on wealth changes.

    S.I.M.P.L.E Leverage graphic showing how to multiply and protect wealth.

    Next Steps for Your Financial Clarity

    If you’re tired of watching your hard-earned money disappear into the pockets of massive corporations through "Bill Creep," it’s time to take action. Whether you use the 5-step framework above or look into professional resources to do it for you, the goal is the same: Keep more of what you earn.

    Want to see how the experts handle this process?

    Review the information here when ready: www.mwrfinancial.com/krnrstn21

    Want me to send you the information so you can review how it works? Reply "INFO" and I'll send the next step.


    Tweet Draft for Sonny:
    "Stop letting 'Bill Creep' drain your bank account! 💸 Most people are overpaying for internet, cell, and insurance by 10-30%. Check out our latest guide on the Proven Bill Negotiation Framework to take control of your monthly expenses. #FinancialClarity #KStoneEnterprises"

    Note to Lamont: This post focuses on bill negotiation awareness and education. It does not guarantee specific savings or financial outcomes. It positions you as a liaison to MWR resources.

  • Are High Mortgage Rates Bad? The 2026 Truth for Maryland Homebuyers

    Are High Mortgage Rates Bad? The 2026 Truth for Maryland Homebuyers

    If you’ve been keeping an eye on the Maryland housing market lately, you’ve probably seen the headlines. As of June 2026, the 30-year fixed mortgage rate is hovering around 6.6%. For many people who remember the "glory days" of 3% or even 4% rates, that number looks like a giant red "STOP" sign.

    But is it?

    When you dig into the actual data and look at how the market is behaving on the ground in places like Millersville, Gambrills, and the broader Baltimore region, a different story emerges. The truth is that "high" rates aren't necessarily a bad thing for homebuyers. In fact, for the prepared buyer, they might just be the best news you’ve heard all year.

    🗳️ Quick Poll: What's your take on the 2026 Maryland market?

    Which camp are you in? Drop your answer in the comments!

    A) "Rates are too high — I'm waiting it out"
    B) "Less competition sounds like my opportunity"
    C) "I'm not sure — just trying to learn the market"
    D) "I'm already under contract or closed this year"

    In this deep dive, we’re going to look at the reality of the 2026 market, why the sticker shock is often misplaced, and how you can actually use these rates to your advantage to secure a home that you would have been outbid on just a few years ago.

    The 6.6% Reality Check: Perspective Matters

    First, let’s talk about that 6.6% figure. Yes, it’s higher than the pandemic lows, but let’s look at the historical context. If you talk to anyone who bought a home in the 1980s, they’ll tell you stories of 13%, 15%, or even 18% mortgage rates. In that light, 6.6% is actually quite moderate.

    According to recent data, the Maryland average mortgage rate is sitting at about 6.59%, which is almost exactly in line with the national average. While it means your monthly payment will be higher than it would have been in 2021, the market has also changed to accommodate these numbers.

    Why the "High Rate" Fear Might Be Costing You

    When rates are low, everyone and their cousin is out looking for a house. This creates the "feeding frenzy" environment we saw a few years ago: 20 offers on one house, buyers waiving inspections, and prices being driven $50,000 over asking price in a weekend.

    When rates are "high," that crowd thins out.

    A conceptual balance scale showing higher mortgage rates outweighing lower buyer competition

    The Hidden Benefit: The Return of Negotiating Power

    The biggest advantage of the 2026 Maryland market is the shift in power. For years, sellers held all the cards. If you asked for a repair, they moved to the next buyer. If you asked for closing cost assistance, they laughed.

    Today, we are seeing the Home Demand Index in the Baltimore region drop. As of June 2024, it sat at 77, categorized as "Slow." Homes are sitting on the market longer, and new listings are starting to accumulate.

    What does this mean for you?

    1. Seller Concessions are Back: We are seeing more sellers willing to contribute to a buyer's closing costs. Some are even willing to pay for a "rate buy-down," which can effectively lower your interest rate for the first few years of the loan.
    2. Inspection Leverage: You no longer have to gamble on a house with a 20-year-old roof. With longer days on market, you have the time and the leverage to ask for necessary repairs or credits.
    3. Price Stability: While Maryland home prices are still up about 2.4% to 5% year-over-year, the rate of growth has slowed down. You aren't necessarily chasing a runaway train anymore.

    Maryland-Specific Opportunities: From Millersville to the DMV

    The Maryland market isn't a monolith. What’s happening in Montgomery County is different from what’s happening in Anne Arundel or Baltimore City.

    For instance, in areas like Millersville and Gambrills, we are seeing a shift toward a more balanced environment. These are highly desirable areas with great schools and amenities, but even here, the "slowdown" is giving buyers a chance to breathe.

    If you are looking at specific listings, like those found on OneReal, you’ll notice that properties are being priced more realistically. The days of "list low and wait for the bidding war" are largely over. Sellers who want to move are having to be more competitive with their pricing and their willingness to work with buyers.

    The Maryland Mortgage Program (MMP)

    Don't forget that Maryland has some of the best state-level support for homebuyers in the country. The Maryland Mortgage Program (MMP) offers competitive rates, currently around 6.625% for conventional loans, but more importantly, they offer down payment and closing cost assistance.

    If you are a first-time buyer or even a repeat buyer in certain areas, these programs can bridge the gap that higher rates might have created in your budget. It’s not just about the rate; it’s about the total cost to get into the door.

    The Strategy: Analyze the Deal, Not Just the Rate

    One of the biggest mistakes buyers make in 2026 is focusing solely on the interest rate. They see 6.6% and walk away. But real estate wealth is built on the deal, not just the financing.

    Think about it this way:

    • Scenario A: 3% Interest Rate, but you have to pay $50,000 over asking price and waive all inspections.
    • Scenario B: 6.6% Interest Rate, but you buy the house at a fair market price, get $10,000 in seller-paid closing costs, and get a new HVAC system installed before closing.

    In many cases, Scenario B leaves you in a much stronger financial position. You can eventually refinance a mortgage rate if they drop in the future, but you can never go back and change the price you paid for the house.

    A modern, aspirational Maryland kitchen representing the goal of homeownership

    Is Now the Time to Buy in Maryland?

    The answer depends on your personal situation, but from a market perspective, 2026 is providing a unique window of opportunity. The "scary" rates are keeping the competition at bay, while the steady (but slower) price growth ensures that your investment is still likely to build equity over time.

    Instead of asking "Is the rate too high?", you should be asking:

    • Does this property meet my long-term needs?
    • Can I comfortably afford the monthly payment at current rates?
    • Does the lack of competition allow me to get a better property than I could have two years ago?

    If the answer to those is yes, then the "high" rates are actually your ally. They are the filter that removed the chaos from the market, leaving room for serious, prepared buyers to make smart moves.

    Your Next Step: Getting the Real Data

    Headlines are great for general information, but real estate is local: down to the street level. If you're looking at a specific property in Maryland and wondering if the numbers make sense, don't guess.

    Whether you’re looking at a vacant property that seems like a deal, or a beautiful home in a neighborhood you love, the first step is always analysis. I help buyers and investors look past the headlines and into the actual data of the property.

    Close-up of a hand typing a property address into a phone

    Send me the property address or basic details and I’ll let you know what information would be needed for the next step.


    Tweet for Sonny:
    "Stop letting 'high' mortgage rates scare you away from the Maryland market. 📉 In 2026, 6.6% is the rate that’s actually clearing the path for savvy buyers. Less competition = more negotiating power. 🏠 Check out the full breakdown on the blog! #MarylandRealEstate #HomeBuying2026 #KStoneEnterprises"

  • The Proven 5-Step Framework to Eliminate Debt and Finally Get Financial Clarity

    The Proven 5-Step Framework to Eliminate Debt and Finally Get Financial Clarity

    Let’s be honest: debt doesn’t just sit in your bank account or on a credit card statement. It sits on your shoulders. It’s that low-level hum of anxiety when the mail comes, or the slight hesitation before you swipe your card at the grocery store.

    As we move through 2026, the numbers tell a pretty intense story. Total U.S. household debt has climbed to a staggering $18.8 trillion in the first quarter of this year. If you feel like your balances are creeping up faster than your income, you aren’t alone. In fact, the average credit card debt per individual has hit a record high of nearly $6,580.

    But here’s the thing: debt isn't a life sentence. It’s a math problem with an emotional component. At K-Stone Enterprises, we believe that education is the ultimate equalizer. When you understand the "why" and the "how," the "when" starts to feel a lot more manageable.

    We’ve put together a 5-step framework designed to move you from "how did this happen?" to "here is exactly where I’m going." No hype, no overnight miracles: just a clear, educational path toward financial clarity.


    Step 1: The Debt Audit (Stop Guessing, Start Knowing)

    The hardest part of any journey is looking at the starting line. Most people have a "vague idea" of what they owe, but vagueness is the enemy of progress. You can’t defeat an enemy you haven't identified.

    A Debt Audit isn't just about the numbers; it’s about the details. Grab a spreadsheet or a piece of paper and list every single debt you have. You need four columns:

    1. The Name of the Creditor
    2. The Total Balance
    3. The Interest Rate (APR)
    4. The Minimum Monthly Payment

    When you see it all in one place, it might feel overwhelming at first, but that feeling is actually the beginning of control. You're no longer wondering: you’re measuring. In 2026, with interest rates still being a major factor in household budgets, knowing your APR is more important than ever. If you're paying 24% interest on a $5,000 balance, you aren't just paying back what you borrowed; you’re effectively paying a "penalty" for being in debt every single day.

    Motivational finance prompt encouraging debt elimination


    Step 2: Plugging the Leaks (Cash Flow vs. Income)

    We often think the answer to debt is "making more money." While more money helps, it doesn't solve a cash flow problem. Cash flow is the movement of money in and out of your life. If you have "leaks": unnecessary subscriptions, high-cost conveniences, or "lifestyle creep": even a $20,000 raise won't fix the underlying issue.

    Before you can accelerate your debt payoff, you have to find the "hidden" money already sitting in your budget. This is what we call Cash Flow Management.

    • The 30-Day Freeze: Try pausing all non-essential spending for 30 days. This isn't about deprivation; it's about reset.
    • The Subscription Audit: Check your bank statements for those $9.99 charges you forgot about two years ago.
    • The "Found" Money Strategy: Any tax refunds, work bonuses, or garage sale profits shouldn't be "bonus spending" money. In this framework, they are "velocity" money used to attack the balances you identified in Step 1.

    Step 3: Choosing Your Velocity Strategy (Snowball vs. Avalanche)

    Once you’ve stopped the bleeding, you need a plan of attack. There are two primary educational methods for paying down debt, and the "right" one depends on your personality.

    The Debt Snowball

    You pay the minimum on everything except the smallest balance. You attack that smallest balance with every extra dollar you found in Step 2. When that debt is gone, you take the entire payment you were making and "roll" it into the next smallest debt.

    • Why it works: It provides quick wins. Seeing a $300 credit card disappear in 30 days gives you the psychological fuel to keep going.

    The Debt Avalanche

    You pay the minimum on everything except the debt with the highest interest rate.

    • Why it works: Mathematically, this saves you the most money over time. By killing the high-interest "predators" first, you stop the compounding interest from working against you.

    In our experience at K-Stone, the best strategy is the one you will actually stick to. Whether you choose the psychological boost of the Snowball or the mathematical efficiency of the Avalanche, the key is consistency.

    Illustration of reaching the peak of financial freedom


    Step 4: Lowering the "Cost of Borrowing"

    One of the biggest hurdles to debt elimination is high interest. If your interest rate is 29%, a significant portion of your monthly payment is just treading water: it’s not actually reducing your principal.

    Part of a smart financial strategy involves interest rate awareness. This could mean:

    • Negotiating with Creditors: Many people don't realize they can call their credit card company and ask for a lower rate, especially if they have a history of on-time payments.
    • Credit Education: Improving your credit score can give you access to better financial tools. A higher score might allow you to move high-interest debt to a lower-interest consolidation option, though this should only be done if you’ve already fixed the "spending leaks" from Step 2.
    • Professional Strategies: This is where having the right resources matters. Understanding how to leverage financial strategies that banks use can change the timeline of your debt journey.

    S.I.M.P.L.E Leverage Everything Weekly Event Graphic


    Step 5: Sustainable Habits & Professional Leverage

    The final step isn't just about reaching zero; it’s about staying there. Debt elimination is a lifestyle change, not a one-time event. This means building an emergency buffer.

    Most people fall back into debt because a "surprise" happens: the car breaks down, the AC dies, or a medical bill arrives. Without a small emergency fund (even just $1,000 to $2,000 to start), you’ll be forced to swipe that credit card again, and the cycle restarts.

    This is also where Professional Leverage comes in. You don't have to be an expert in tax awareness, bill negotiation, or credit education to benefit from them. You just need to be a liaison to the right information. At K-Stone Enterprises, we point people toward resources that help them review their options, understand their numbers, and move toward financial clarity with confidence.


    The Path Forward

    Financial clarity isn't about being rich; it's about being in control. It’s knowing that every dollar has a job and every debt has an expiration date.

    The average U.S. household is carrying a heavy load right now, but you don't have to carry it forever. By auditing your numbers, plugging your leaks, choosing a strategy, lowering your interest costs, and building sustainable habits, you change the trajectory of your family's future.

    We’re here to help you navigate that information. No guarantees, no pressure: just the education and resources you need to make the best decision for your situation.

    Golden key unlocking a chain representing breaking free from debt

    Review the information here when ready: www.mwrfinancial.com/krnrstn21


    Draft Tweet for Sonny:
    "The average US household debt hit $18.8T in 2026. 📉 If you're feeling the weight, it's time to move from guessing to knowing. Check out our 5-step framework for debt education and financial clarity. #FinancialEducation #DebtAwareness #KStoneEnterprises"

  • The Ultimate Guide to Buying a Home in Maryland: Everything You Need to Succeed with Tight Inventory

    The Ultimate Guide to Buying a Home in Maryland: Everything You Need to Succeed with Tight Inventory

    Buying a home in Maryland in 2026 feels a lot different than it did a few years ago. We aren't in the "wild west" of 2021 anymore, where homes were selling in four hours for $50,000 over asking price with no inspections. But we aren't in a "buyer's paradise" either.

    Today’s Maryland market is a unique beast. It’s a seller-leaning environment that is slowly, very slowly, moving toward a more balanced state. We are seeing active inventory levels hover around 2.8 months of supply. To put that in perspective, a "balanced" market is usually considered six months of supply.

    So, yes, inventory is still tight. But here is the good news: buyers actually have more breathing room than they’ve had in years. Instead of homes disappearing in a heartbeat, the average home in Maryland is now sitting on the market for about 32 to 45 days.

    If you are looking to plant roots in the Old Line State, you don’t need luck: you need a strategy. This guide will break down exactly how to navigate the current Maryland housing landscape, from the sub-$450k competition to the "30-day window" secret.

    The 2026 Maryland Market: By the Numbers

    Before you start touring homes, you have to understand the ground you're standing on. As of June 2026, the Maryland real estate market is defined by a few key metrics:

    • Median Sale Price: Roughly $454,000 statewide. This is up about 3-5% from this time last year.
    • Mortgage Rates: Floating in the mid-6% range (averaging around 6.46%). While higher than the historic lows of the past, they have stabilized, making it easier to plan a long-term budget.
    • Days on Market: Expect homes to stay active for 30 to 60 days. In counties like Montgomery, Howard, and Frederick, it’s closer to 20-40 days because demand there is higher.
    • Inventory Levels: We are currently at about 2.8 months of supply. It’s tight, but it’s an improvement over the 1-month supply we saw during the pandemic peak.

    What does this mean for you? It means you have time to think, but you still have to be prepared to move when the right opportunity surfaces.

    Strategy #1: Target the "30-Day Window"

    One of the biggest mistakes Maryland buyers make right now is only looking at "New Listings."

    When a home is brand new on the market, it draws the most eyeballs and the most competition. If it’s priced perfectly and looks like a model home, you might still see multiple offers. However, once a home hits the 30-day mark without a contract, the power dynamic shifts.

    Sellers who haven't received an offer after a month often start to get nervous. This is your "sweet spot." In the current market, homes sitting for 30-60 days are prime candidates for:

    1. Price Negotiations: Sellers may be more willing to drop the price to get the deal done.
    2. Inspection Requests: You have more leverage to ask for repairs.
    3. Seller Concessions: You might be able to get the seller to cover some of your closing costs.

    When you use Lamont’s property search tool, pay close attention to the "Days on Market" filter. Don't be afraid of a house that’s been sitting for 45 days: it might just be the best deal in the neighborhood.

    An aerial view of a charming Maryland neighborhood with tree-lined streets and a mix of modern and colonial homes.

    Strategy #2: Budget for the Payment, Not Just the Price

    In a mid-6% interest rate environment, the "sticker price" of the home is only half the story. Your monthly payment is what actually matters for your lifestyle.

    For example, a $400,000 mortgage at 6.5% results in a principal and interest payment of roughly $2,528. A few years ago, at 3%, that same loan was about $1,686. That’s a significant difference.

    When you sit down to plan your move, start with your comfortable monthly "all-in" number: including taxes, insurance, and any HOA or condo fees. Work backward from there to find your target home price. This prevents "budget creep" and ensures that when you find a home you love, the numbers actually make sense.

    If you want to see what's currently available in your specific price bracket across Maryland, you can browse current listings here.

    Strategy #3: Master the Art of Seller Concessions

    Because inventory is tight but demand has cooled slightly due to rates, "seller concessions" are back on the menu. A concession is when the seller agrees to pay for something on the buyer's behalf.

    In 2026, the most popular concession is the Interest Rate Buydown. Instead of asking the seller to drop the price of the home by $10,000, you can ask them to contribute that $10,000 toward "buying down" your interest rate. This can lower your monthly payment significantly more than a simple price reduction would.

    Other common concessions include:

    • Covering the cost of a one-year home warranty.
    • Paying for specific repairs identified during the home inspection.
    • Contributing to the buyer's closing costs (which can be 3-5% of the purchase price in Maryland).

    A couple sitting at a kitchen table with a laptop and folders, optimistically discussing their home buying budget.

    Local Spotlight: Where is the Inventory?

    Maryland is a diverse state, and the market varies wildly depending on where you are looking.

    • Montgomery, Howard, and Frederick Counties: These remain the tightest markets. Inventory is often under 2 months, and competition is highest for single-family homes under $600k. If you are looking here, you need to be pre-approved and ready to act quickly.
    • Baltimore City and County: The Baltimore region is currently seeing a "Slow" demand index. This is great news for buyers. You’ll find more options, more flexibility from sellers, and a higher likelihood of getting concessions.
    • Anne Arundel County: This area is a middle ground. Coastal properties and high-end suburbs move fast, while mid-range townhomes are seeing more balanced days-on-market.

    Lamont Milbourne, a licensed Maryland real estate professional with The Real Brokerage LLC, specializes in helping buyers navigate these local nuances. You can learn more about his approach and background on his About Page.

    Step-by-Step: The Path to Your New Maryland Home

    If you're ready to start the journey, here is the roadmap for the current market:

    1. Get Your "Paperwork" in Order: Before you step foot in a house, get a rock-solid pre-approval from a reputable lender. In a tight inventory market, a seller won't even look at your offer without one.
    2. Identify Your "Must-Haves" vs. "Nice-to-Haves": With fewer homes to choose from, you might not find a place that checks all 100 boxes. Identify the 3-5 non-negotiables (location, bedroom count, school district) and be flexible on the rest.
    3. The "First Look" Tour: When a home hits the market that fits your criteria, go see it within the first 48 hours. Even if you plan to wait for the "30-day window" on some properties, you need to know what's moving fast so you can gauge value.
    4. Data-Driven Offers: Don't guess. Have your agent pull recent "Comps" (comparable sales) from the last 90 days. In a shifting market, data from six months ago is irrelevant.
    5. The Inspection is Your Friend: Never skip the inspection. Even in a competitive market, you need to know the bones of what you are buying.

    A real estate agent's hand holding a set of house keys with a 'Sold' keychain in front of a brick Maryland townhouse.

    Final Thoughts: Should You Wait?

    Many people ask, "Is 2026 a good time to buy, or should I wait for a crash?"

    Most experts agree that a housing crash in Maryland is highly unlikely. Why? Because we still have a fundamental supply issue. There simply aren't enough homes for everyone who wants one. While prices aren't skyrocketing like they were in 2021, they are still projected to appreciate by about 2-4% this year.

    If you wait two years for rates to drop, you might find that home prices have increased by another 6-8%, washing out any savings you gained from a lower interest rate.

    The best time to buy a home is when you are financially ready and plan to stay for at least 5 to 7 years. In the long run, Maryland real estate has proven to be a resilient and valuable asset.

    Ready to see what’s out there or have a specific neighborhood in mind? Let's talk about your goals and find the right path forward.

    Reply INFO and I'll send the next step.

  • 7 Tax Strategy Mistakes Maryland Families Are Making in 2026 (and How to Fix Them)

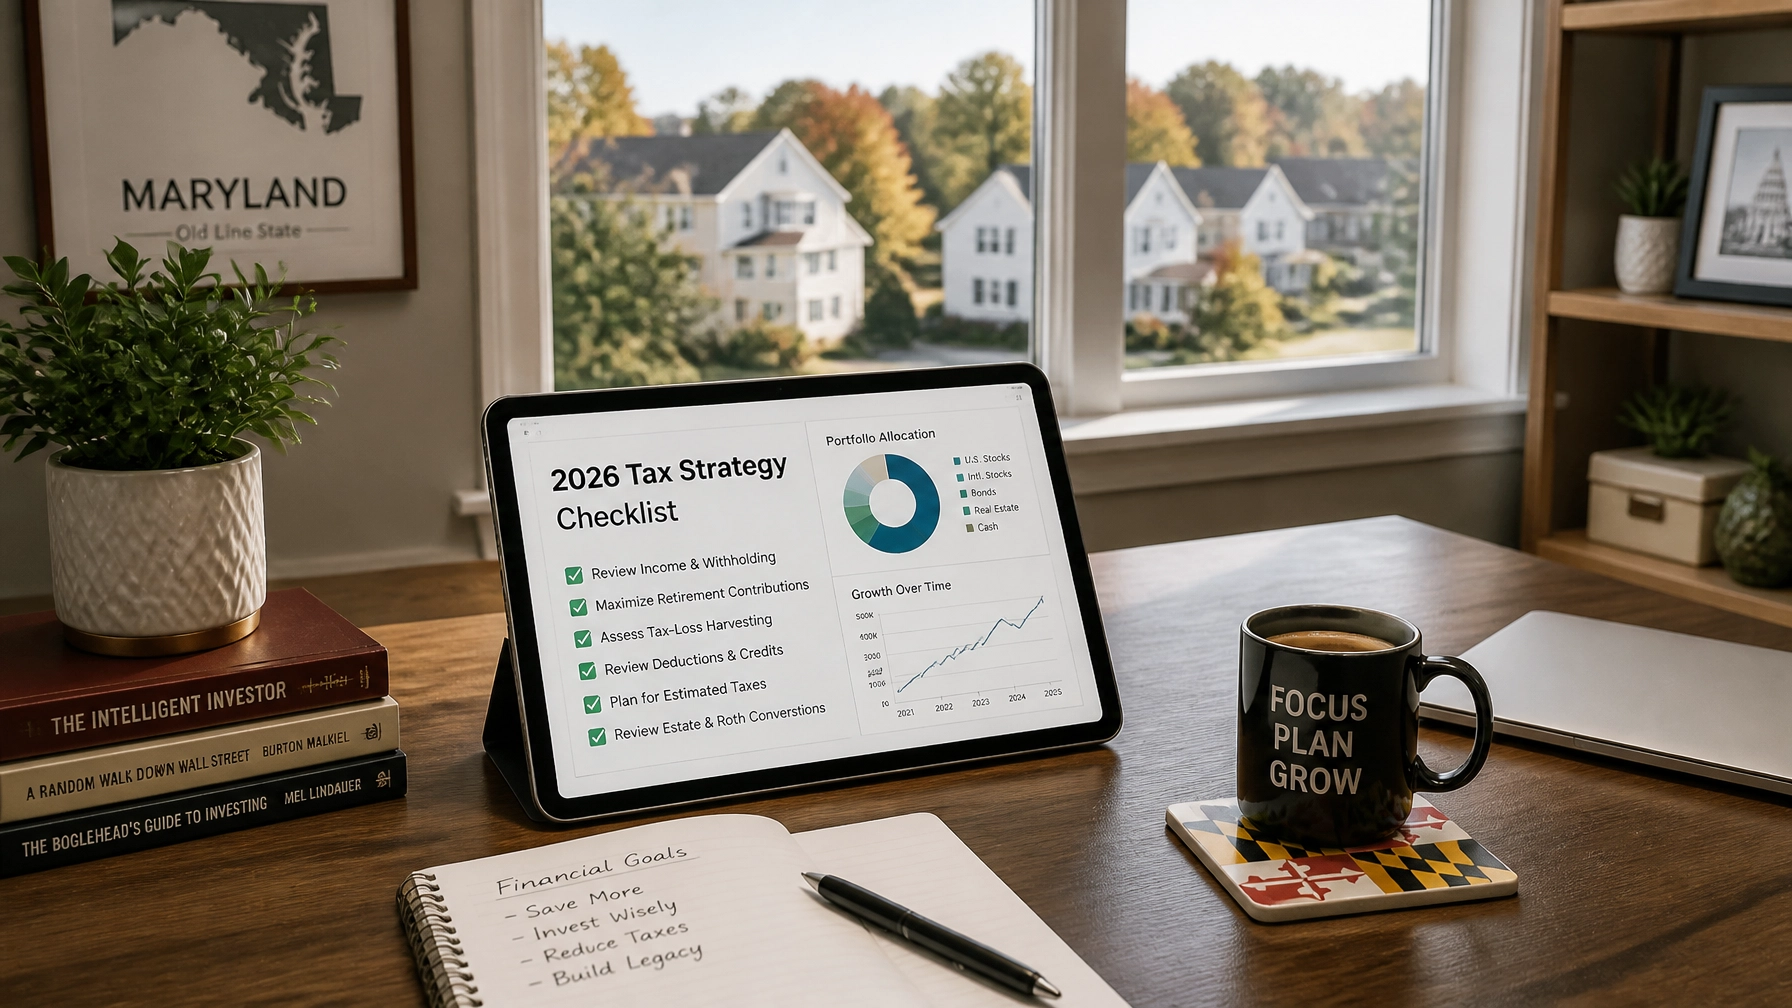
    7 Tax Strategy Mistakes Maryland Families Are Making in 2026 (and How to Fix Them)

    If you’re a Marylander, you know that our state doesn’t exactly have a reputation for being "low tax." Between state income taxes, local county piggyback taxes, and ever-shifting federal rules, keeping more of your hard-earned money can feel like a full-time job.

    As we move through 2026, the landscape has shifted again. Significant changes in Maryland’s budget legislation have introduced new surcharges and rate hikes, while federal updates like the "One Big Beautiful Bill Act" have rewritten the rules for families and workers.

    At K-Stone Enterprises, we believe that financial clarity is the first step toward financial freedom. Lamont Milbourne often says he isn't here to give you a magic pill or guarantee a specific refund amount: he’s here as a liaison to the information and resources you need to make better decisions.

    Unfortunately, many families are still using 2019 strategies in a 2026 world. Here are the seven most common tax strategy mistakes Maryland families are making right now and, more importantly, how you can start fixing them today.


    1. The "Set It and Forget It" Withholding Trap

    Most people fill out their W-4 when they get hired and never look at it again. In 2026, that’s a recipe for a surprise bill in April.

    Maryland has recently updated its state and local withholding guidance. The Comptroller’s office has tied default state withholding percentages to the median local tax rates across our 23 counties and Baltimore City. If you live in a higher-tax county like Montgomery or Prince George’s, but your withholding is set to a "default" median, you might be under-withholding every single paycheck.

    The Fix: Don’t wait for your tax preparer to tell you that you owe thousands. Review your Maryland Form MW507 and your federal W-4. If your household income has changed or you’ve moved to a different county, a quick adjustment now can save you a massive headache later.

    2. Ignoring the New Capital Gains Surcharge

    Maryland enacted a significant capital gains tax surcharge that is now in full swing for the 2026 tax year. This was designed to help close the state’s budget gap, and it primarily hits families who are selling assets like stocks, secondary properties, or business interests.

    Many families assume capital gains are purely a "federal problem," but Maryland's new surcharge means the state is taking a larger bite of those profits than ever before.

    The Fix: If you’re planning to sell an asset, talk to a professional about "harvesting" gains or losses over multiple years. Spreading the sale out can sometimes keep you under the thresholds that trigger the highest surcharge rates.

    Maryland state map integrated with financial graphs, representing local tax awareness.

    3. Federal "Credit Amnesia" (The Expanded Child Tax Credit)

    The federal government hasn't stayed still, either. For 2026, the expanded Child Tax Credit (CTC) can reduce a family’s tax liability by up to $200 more per child than in previous years.

    While that sounds like a win, the mistake lies in failing to plan for the eligibility phase-outs. If your income has grown, you might find yourself in a "dead zone" where you no longer qualify for the full credit, yet you haven't adjusted your other strategies to compensate for that lost tax break.

    The Fix: Use a simple tax projection tool or consult with an expert to see exactly where your 2026 income falls relative to the new CTC phase-outs. Knowing your "true" tax liability helps you budget for the year ahead.

    4. The "Year-to-Year" Strategy Blindspot

    This is perhaps the most common mistake Lamont sees. Most families look at taxes as a one-time event that happens every April. They ask, "How can I pay less this year?"

    Real wealth, however, is built by looking at taxes over a lifetime. By only focusing on this year, you might miss opportunities for Roth conversions or strategic retirement contributions that would have saved you six figures over thirty years, even if they cost you a little more today.

    The Fix: Shift your mindset from "tax preparation" (recording the past) to "tax strategy" (planning the future). Think about where tax rates might be when you retire versus where they are now in 2026.

    A Maryland family looking empowered and relieved while planning their finances at home.

    5. Neglecting the "No Tax on Tips" Provision

    If you or anyone in your household works in Maryland’s thriving hospitality, restaurant, or service industry, 2026 brought a game-changing federal update: the "No Tax on Tips" deduction.

    Eligible workers can now deduct up to $25,000 of tips from their federal taxable income. However, many workers aren't keeping the specific, rigorous records required to claim this deduction safely, or they are accidentally reporting it in a way that triggers an IRS flag.

    The Fix: If you earn tips, start using a digital tracking app specifically designed for tip-based income. Accurate, daily records are your best defense and your ticket to keeping more of those earnings.

    6. Leaving Maryland-Specific Deductions on the Table

    Maryland offers several unique tax benefits that often go unclaimed. For example, contributions to a Maryland 529 College Investment Plan can offer a state tax deduction of up to $2,500 per beneficiary per year.

    Because Maryland’s state income tax rates have increased in 2026, these deductions are actually more valuable than they used to be. Every dollar you deduct now saves you more in actual tax than it did two years ago.

    The Fix: Audit your state-specific contributions. Are you maximizing your 529 plan? Are you taking advantage of the Maryland Pension Exclusion if you are an older taxpayer? These "small" wins add up quickly.

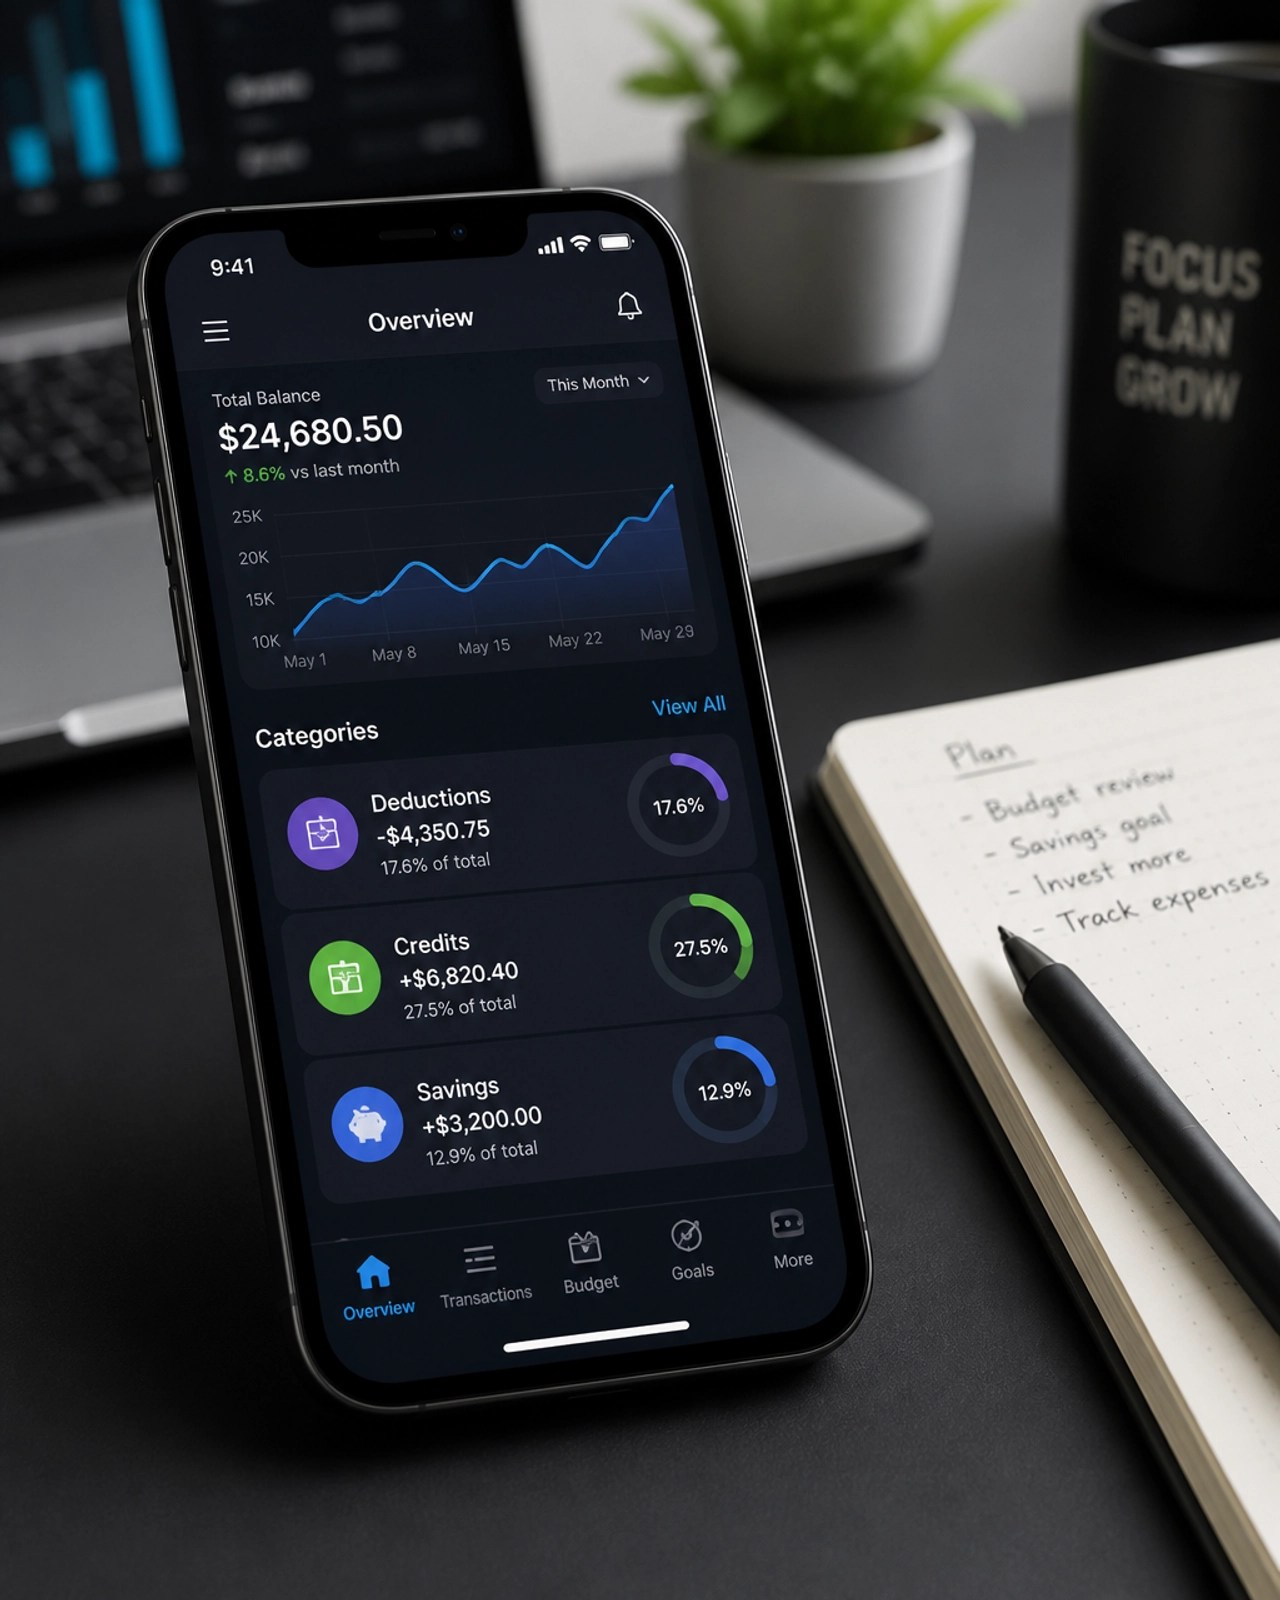
    A smartphone displaying a financial management app, representing modern digital documentation.

    7. Documentation Disorder (The "Shoebox" Method)

    We live in a digital world, yet many families still show up to their tax appointments with a literal or metaphorical shoebox of receipts. In 2026, with the IRS increasing its use of AI for automated notices and audits, "guessing" or "estimating" your deductions is a dangerous game.

    Poor documentation leads to two outcomes: you either miss out on deductions because you can't prove them, or you claim them and end up in a stressful audit three years from now.

    The Fix: Use the tools available to you. There are apps that link directly to your bank account to flag potential business expenses or tax-deductible charitable giving in real-time. Don’t wait until December 31st to try and remember what you spent in January.


    Moving Toward Financial Clarity

    Taxes don't have to be a source of constant stress. Most of the frustration comes from the "unknown": not knowing the laws, not knowing your numbers, and not knowing where to turn for information.

    Lamont Milbourne and K-Stone Enterprises are committed to helping Maryland families bridge that gap. We don't provide legal or tax advice, and we don't guarantee that you'll pay zero taxes. What we do is provide access to a system of education and resources through MWR Financial that can help you understand the "rules of the game."

    Whether it's learning about debt education, credit clarity, or general tax awareness, the goal is always the same: to move you from a place of uncertainty to a place of action.

    An older couple walking on a Maryland shoreline, symbolizing long-term financial security.

    Ready to take the next step?

    Don't let 2026 be the year you look back on and say, "I wish I had known." The information is out there, and it’s more accessible than you think.

    Review the information here when ready: www.mwrfinancial.com/krnrstn21


    Tweet Draft for Sonny:
    "Maryland families: Are you making these 7 tax strategy mistakes in 2026? 🦀 From new state surcharges to the 'No Tax on Tips' rule, the landscape has changed. Check out our latest guide to stay ahead. #MarylandRealEstate #TaxStrategy #MWRFinancial #FinancialEducation"

  • Are You Making These 7 Common Credit Score Mistakes? (The 2026 Truth Revealed)

    Are You Making These 7 Common Credit Score Mistakes? (The 2026 Truth Revealed)

    Let’s be real: navigating the financial landscape in 2026 feels a lot different than it did even a few years ago. With total U.S. consumer debt hitting a staggering $18.21 trillion earlier this year, and credit card balances projected to climb to $1.18 trillion by December, the "old rules" of credit don't always apply.

    I’m Lamont Milbourne, and at K-Stone Enterprises, we focus on providing you with the clarity and education you need to make sense of these numbers. Whether you're looking to buy a home in Maryland or just trying to get your financial house in order, your credit score is the heartbeat of your financial life.

    But here’s the thing: most people are still following advice from 2010. In today’s high-interest environment: where the average credit card APR is hovering around 21.52%: a small mistake on your credit report can cost you thousands of dollars in extra interest over time.

    Are you making these common credit score mistakes? Let’s dive into the 2026 truth about what’s actually holding your score back and how you can start looking at your credit with fresh eyes.

    1. The "Just One Day Late" Fallacy

    We’ve all been there. You forget a due date, or the autopay doesn't trigger, and you think, "I'll just pay it tomorrow; it’s no big deal."

    In 2026, it’s a very big deal. Payment history remains the single most influential factor in your credit score, accounting for about 35% of the calculation in most models. With lenders being more conservative due to the current economic climate, even a single 30-day late payment can cause a significant drop in your score.

    The mistake isn't just the late payment; it's the assumption that it "won't hurt that much." In reality, that one slip-up can stay on your report for up to seven years.

    The 2026 Fix: Set up multiple layers of reminders. Don’t just rely on one app. Use calendar alerts, bank notifications, and "safety net" balances to ensure that "just one day" never happens.

    2. The 30% Utilization Trap

    For years, the "golden rule" was to keep your credit card balances below 30% of your limit. While that’s better than being maxed out, in 2026, the 30% rule is more like a "C-grade" effort.

    Data shows that consumers with the highest credit scores typically keep their utilization below 10%, and often even lower. With credit card balances at record highs nationwide, lenders are looking for those who use their credit sparingly. If you're hovering at 29% utilization, you might be wondering why your score is stagnant. It’s because, to a modern algorithm, you’re still showing signs of "credit hunger."

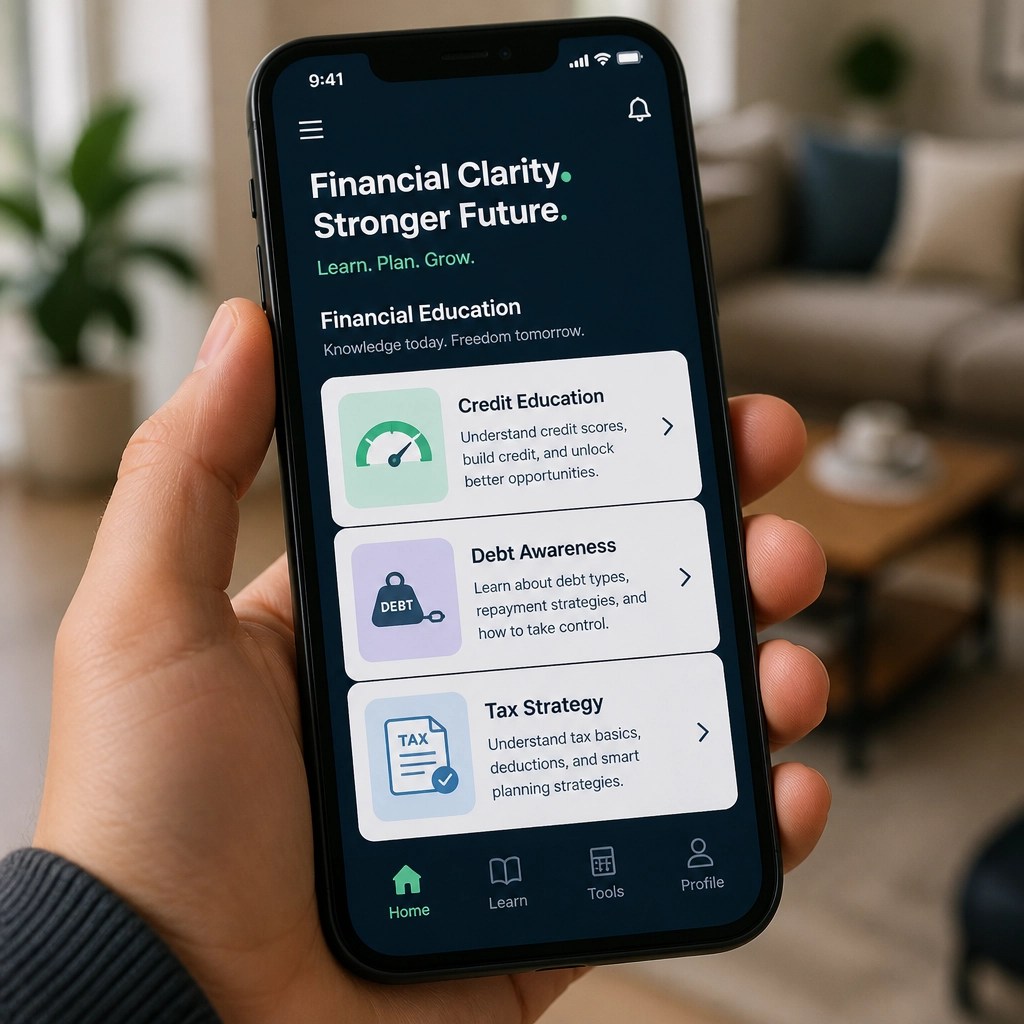
    A smartphone screen showing a modern financial education app interface.

    3. Closing Your "Old Friends"

    When you finally pay off a credit card, the impulse is often to close the account and "be done with it." This is one of the most common mistakes I see.

    Your credit score loves history. Specifically, it loves the average age of your accounts. When you close an old account, you're essentially deleting a part of your financial resume. You're also reducing your total available credit, which can inadvertently spike your credit utilization ratio (see mistake #2).

    Unless a card has a massive annual fee that outweighs its benefits, keeping it open and using it for a small, recurring subscription once a month is usually the better move for your score's longevity.

    4. The "Retail Card" Impulse

    It happens at the checkout counter: "Would you like to save 15% today by opening a store card?"

    In a world where inflation has made every dollar count, 15% off sounds great. But there’s a hidden cost. Every time you apply for new credit, a "hard inquiry" is placed on your report. Multiple inquiries in a short window signal financial stress to lenders.

    Furthermore, retail cards often have lower limits and much higher APRs: frequently exceeding 30% in today's market. One small purchase on a new retail card can negatively impact your average account age and increase your inquiry count, all for a one-time discount on a pair of shoes.

    5. "Set It and Forget It" Syndrome

    Are you actually checking your credit report, or are you just glancing at the "estimated score" on your banking app?

    In 2026, identity theft and data errors are more sophisticated than ever. According to recent consumer trends, many scores are depressed simply because of incorrect information: addresses you never lived at, accounts you never opened, or balances that were paid off but never updated.

    Assuming your score is correct because "you pay your bills" is a mistake. You wouldn't ignore a weird sound in your car's engine just because you changed the oil; don't ignore your credit report just because you're making payments.

    Motivational graphic asking viewers to rate the importance of their financial goals.

    6. Thinking "No Debt" Equals "Great Credit"

    There is a massive difference between being "debt-free" and having "great credit." I talk to many people who pride themselves on never using credit cards and paying for everything in cash. While that’s an admirable lifestyle choice, it leaves you with a "thin file."

    If you ever decide to buy a home or lease a vehicle, a lender needs to see a track record of you managing borrowed money responsibly. If there's no data, they see you as a high risk. You don't have to carry a balance or pay interest to have a great score, but you do need to have active accounts that show you can handle credit.

    7. Ignoring New Scoring Models

    The world moved on to FICO 10T and VantageScore 4.0, which look at "trended data." This means they don't just look at what your balance is today; they look at whether your balances are growing or shrinking over time.

    If you're making the mistake of only paying the minimum while your balance slowly creeps up due to interest, the new models notice that trend. Even if you're never late, a growing debt trend can pull your score down because it looks like you're losing the battle against your balances.

    Why Education is Your Best Asset

    At K-Stone Enterprises, we believe that clarity is the first step toward confidence. We aren't here to guarantee you a specific score or promise "overnight repair": anyone who does that in 2026 isn't being straight with you.

    Instead, we focus on the MWR Financial lane of education. This means helping you understand:

    • Credit Clarity: What’s actually on your report.
    • Debt Education: How to navigate those rising APRs.
    • Financial Protection: Keeping your information safe from modern threats.

    When you have the right information, you stop guessing and start strategizing. You move from being a passenger in your financial life to being the driver.

    A diverse group of adults engaged in a positive financial discussion.

    Final Thoughts

    Your credit score isn't a grade on your value as a person; it's just a data point. But in 2026, it's a data point that dictates how much you pay for your home, your car, and even your insurance.

    By avoiding these seven common mistakes: paying on time, keeping utilization low, respecting your account age, being picky with inquiries, monitoring your reports, building a healthy history, and watching your trends: you put yourself in a much stronger position.

    Ready to see how these pieces fit together for your specific situation?

    Review the information here when ready: www.mwrfinancial.com/krnrstn21


    Tweet for Sonny:
    📊 Think you know the "rules" of credit? Think again. In 2026, the game has changed. From the "30% trap" to the danger of retail cards, are you making these 7 common mistakes? Get the clarity you need here: [Link to Blog] #CreditEducation #FinancialClarity #KStoneEnterprises


  • Maryland Real Estate 2026: 10 Things Every Homeowner Should Know Before Selling

    Maryland Real Estate 2026: 10 Things Every Homeowner Should Know Before Selling

    Selling a home in Maryland has always been a journey, but as we navigate the mid-way point of 2026, the landscape has shifted into something unique. Whether you are looking to downsize in Millersville, move up in Gambrills, or relocate out of the state entirely, the rules of engagement for homeowners have evolved.

    The market today isn't the frantic "bidding war" chaos of a few years ago, nor is it a stagnant environment. It is a market of precision. In 2026, buyers are more educated, financing is more calculated, and the "vibe" of a home matters just as much as the square footage. If you’re thinking about putting a "For Sale" sign in your yard this year, you need to be strategic.

    Here are 10 critical things every Maryland homeowner should know before selling in 2026.

    1. The Inventory Squeeze is Still Real

    Even in 2026, Maryland is facing a persistent inventory challenge. While more homes are trickling onto the market compared to the "lock-in" years of the early 2020s, demand in the Mid-Atlantic region continues to outpace supply. For a seller, this is generally good news. It means that well-maintained, correctly priced homes are still seeing healthy interest.

    However, "low inventory" doesn't mean "automatic sale." In 2026, buyers aren't just looking for any house; they are looking for the right house. They are willing to wait for a property that checks their boxes rather than settling for a fixer-upper at a premium price.

    2. Mortgage Rates Have Found a "New Normal"

    As of June 2026, typical mortgage rates in Maryland are hovering in the mid-6% to low-7% range. While this is a far cry from the historic lows of 2021, the shock has worn off for most buyers. This is the "new normal."

    What does this mean for you as a seller? It means your buyer pool is payment-sensitive. They aren't just looking at the purchase price; they are calculating their monthly outflow with 7% interest in mind. Understanding this helps you empathize with the buyer's perspective and highlights the importance of making your home a "turn-key" opportunity. If a buyer has to pay a higher rate, they often don’t want the added burden of immediate, expensive repairs.

    3. Pricing Strategy: Market Value vs. List Price

    In 2026, overpricing is the fastest way to kill a listing. Current data shows that homes priced correctly from day one sell significantly faster and closer to the asking price than those that start too high and require a "price correction" later.

    A price drop often signals to buyers that something might be "wrong" with the home, even if it’s just that the initial price was ambitious. Working with a professional who understands the specific micro-trends in your Maryland zip code: rather than relying on broad national averages: is essential. You can see examples of how homes are currently positioned in the local market by checking out active Maryland listings.

    4. High-Impact Prep Still Wins

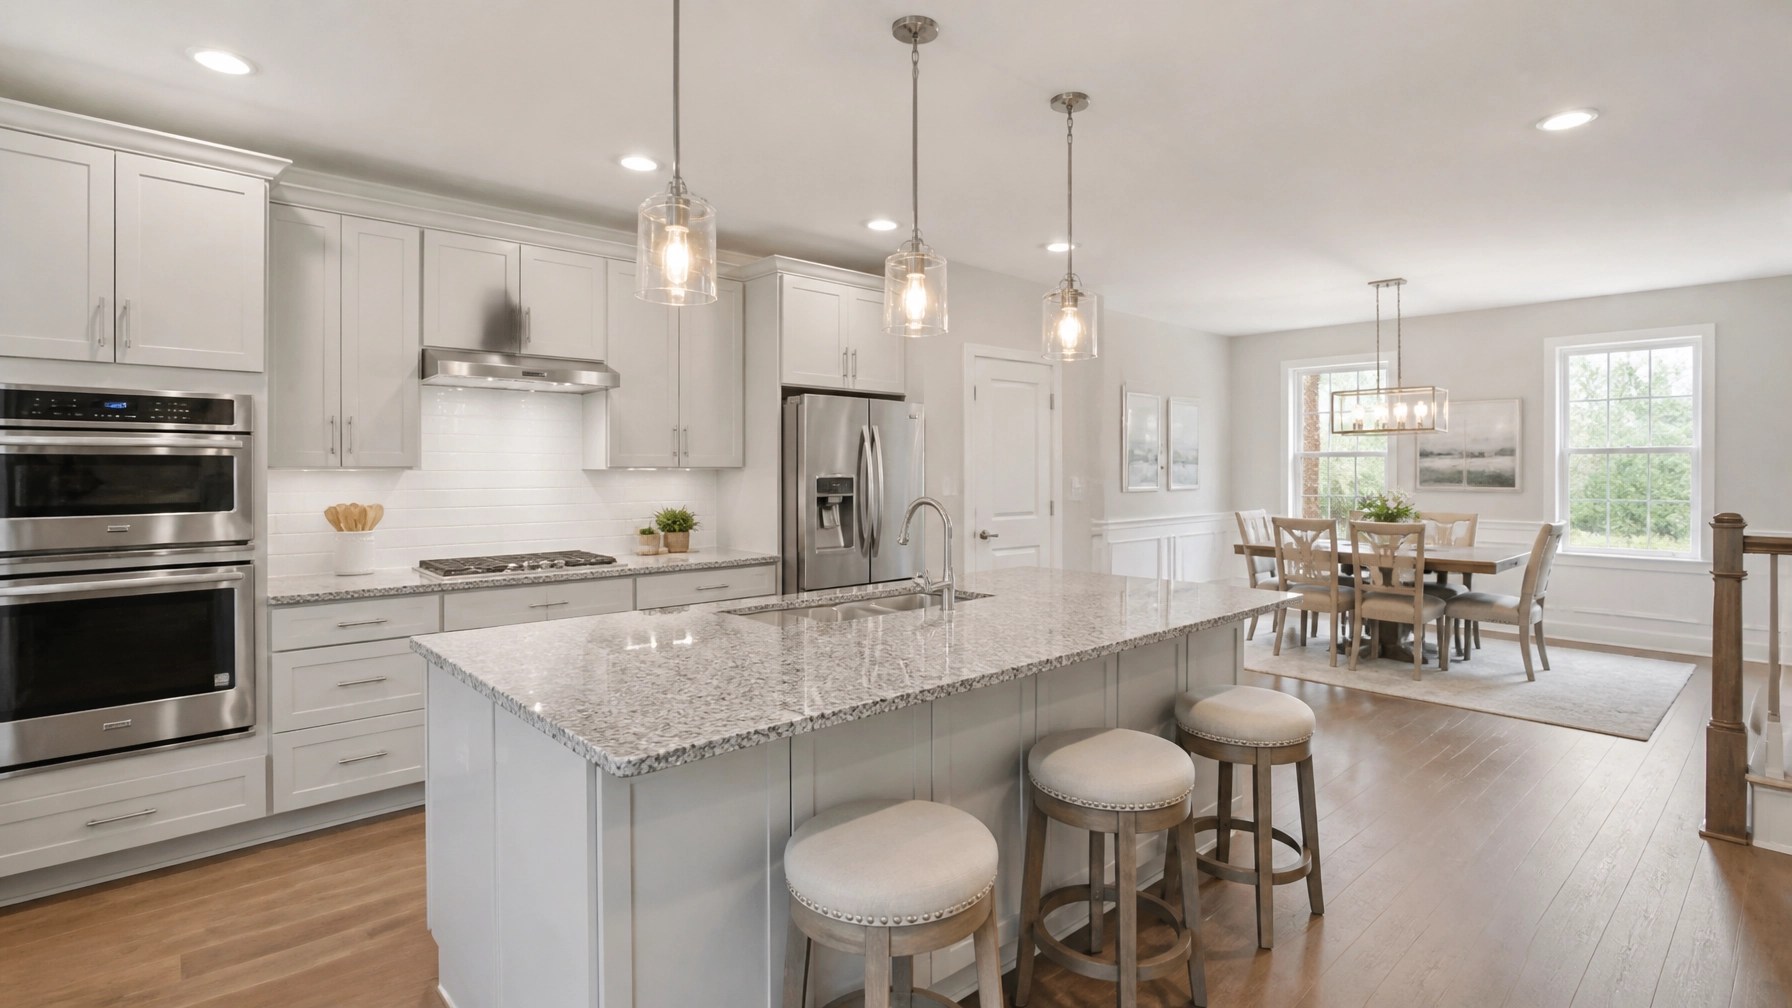
    A modern, professionally staged kitchen and dining area in a Maryland home with neutral colors, granite countertops, and updated lighting. The space is clean and bright to show maximum ROI for a home sale.

    You don’t need a full-scale renovation to get top dollar, but you do need to be intentional. In 2026, the "Big Three" remain the most important areas for ROI:

    • Kitchen Refresh: Think neutral cabinet colors, updated hardware, and ensuring appliances are spotless.
    • Lighting: In the age of high-def photography, lighting is everything. Replace old yellow bulbs with bright, soft white LEDs and update dated fixtures.
    • Paint and Flooring: Fresh, neutral paint and clean (or new) flooring are the most cost-effective ways to make a home feel "new."

    Buyers in 2026 are looking for a lifestyle, not just a structure. Staging: whether physical or virtual: helps them visualize themselves in the space.

    5. Timing the "Spring Surge"

    Data from early 2026 confirms that the traditional spring market is still the peak time for activity in Maryland. Historically, listing your home between mid-April and June can yield the highest sale prices, often $20,000 or more above the annual average.

    The weather is better, the Maryland greenery is blooming, and families are looking to move before the new school year starts. If you have the flexibility to wait for the spring bloom, it often pays off in increased foot traffic and stronger offers.

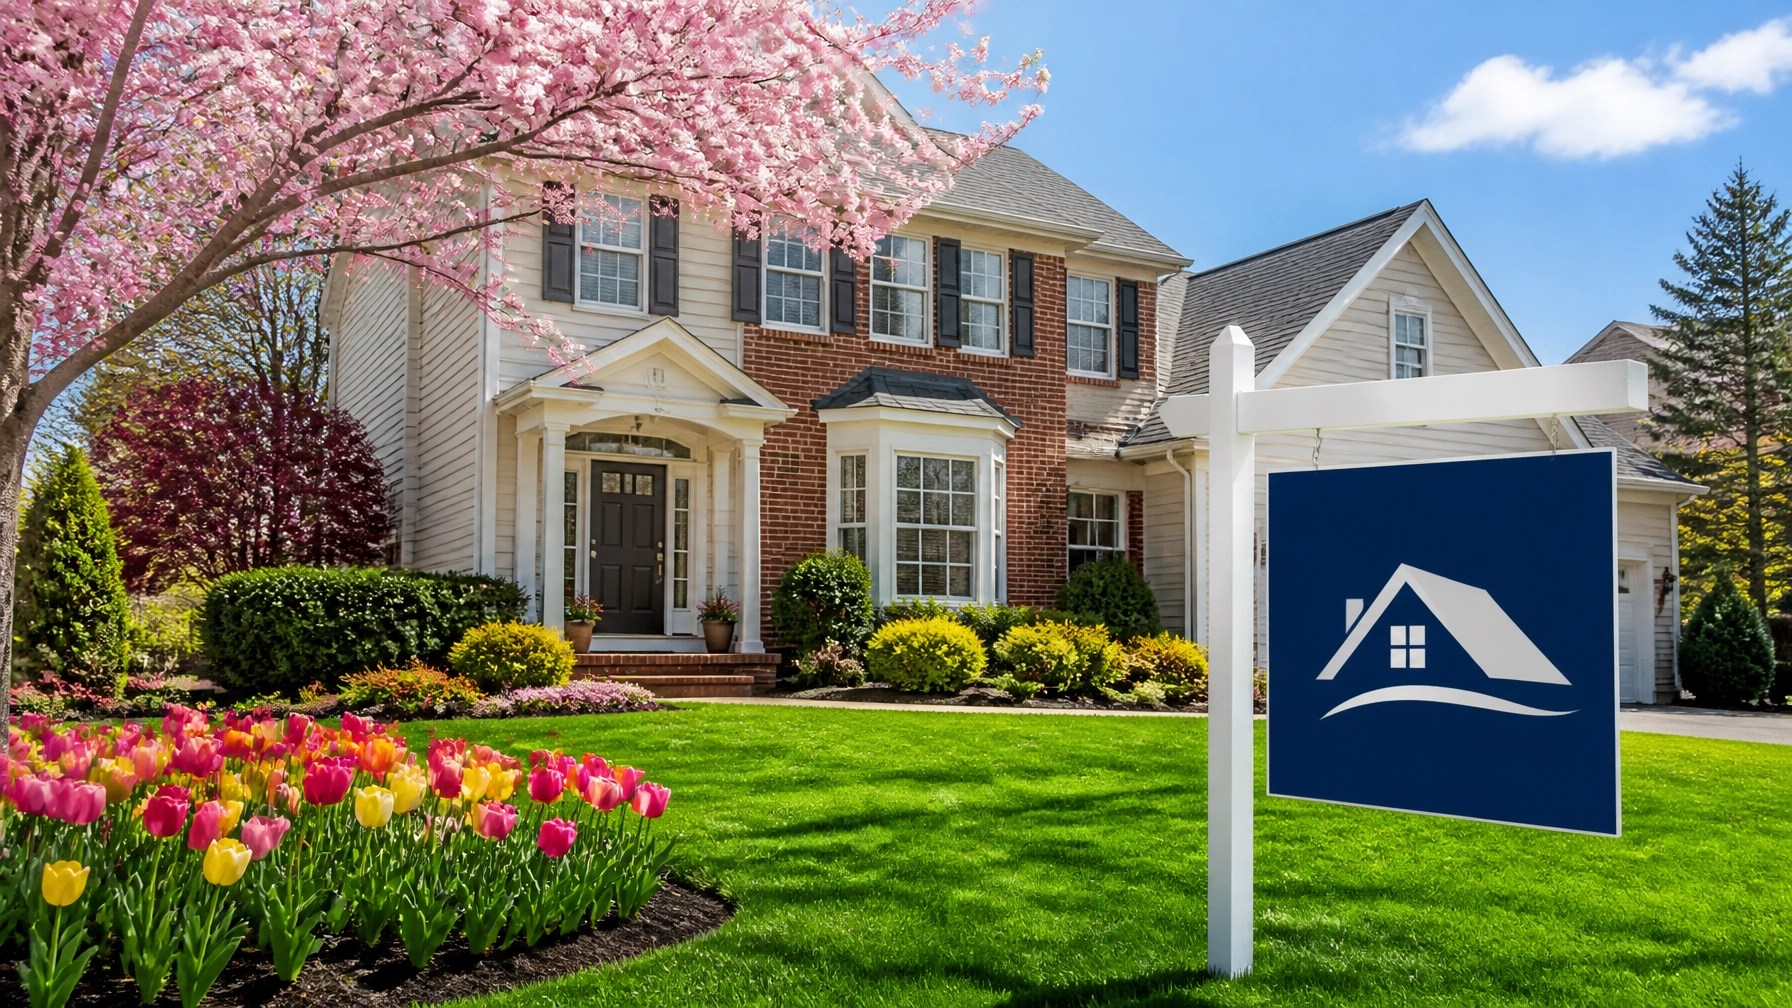
    A front yard of a Maryland suburban home in mid-April with cherry blossoms and tulips in bloom and a 'For Sale' sign in the lush green lawn.

    6. Navigating Maryland-Specific Disclosures

    Maryland has specific requirements when it comes to property disclosures. Sellers are generally required to provide a "Disclaimer or Disclosure" statement. This covers everything from the condition of the roof to any known environmental issues like radon or lead-based paint (especially in older Maryland homes).

    In 2026, transparency is your friend. Buyers are hiring more thorough inspectors than ever before. Being upfront about the age of your HVAC or the condition of your basement helps prevent deals from falling apart during the inspection contingency period.

    7. The Necessity of Professional Marketing

    In 2026, your "First Open House" happens on a smartphone screen. If your online photos aren't professional, many buyers won't even put your address into their GPS.

    Effective marketing in 2026 includes:

    • High-Resolution Photography: Drone shots for larger lots are standard.
    • 3D Virtual Tours: Buyers want to walk through the layout digitally before committing to an in-person showing.
    • Social Media Reach: Your home needs to be where the buyers are: Instagram, TikTok, and localized Facebook groups.

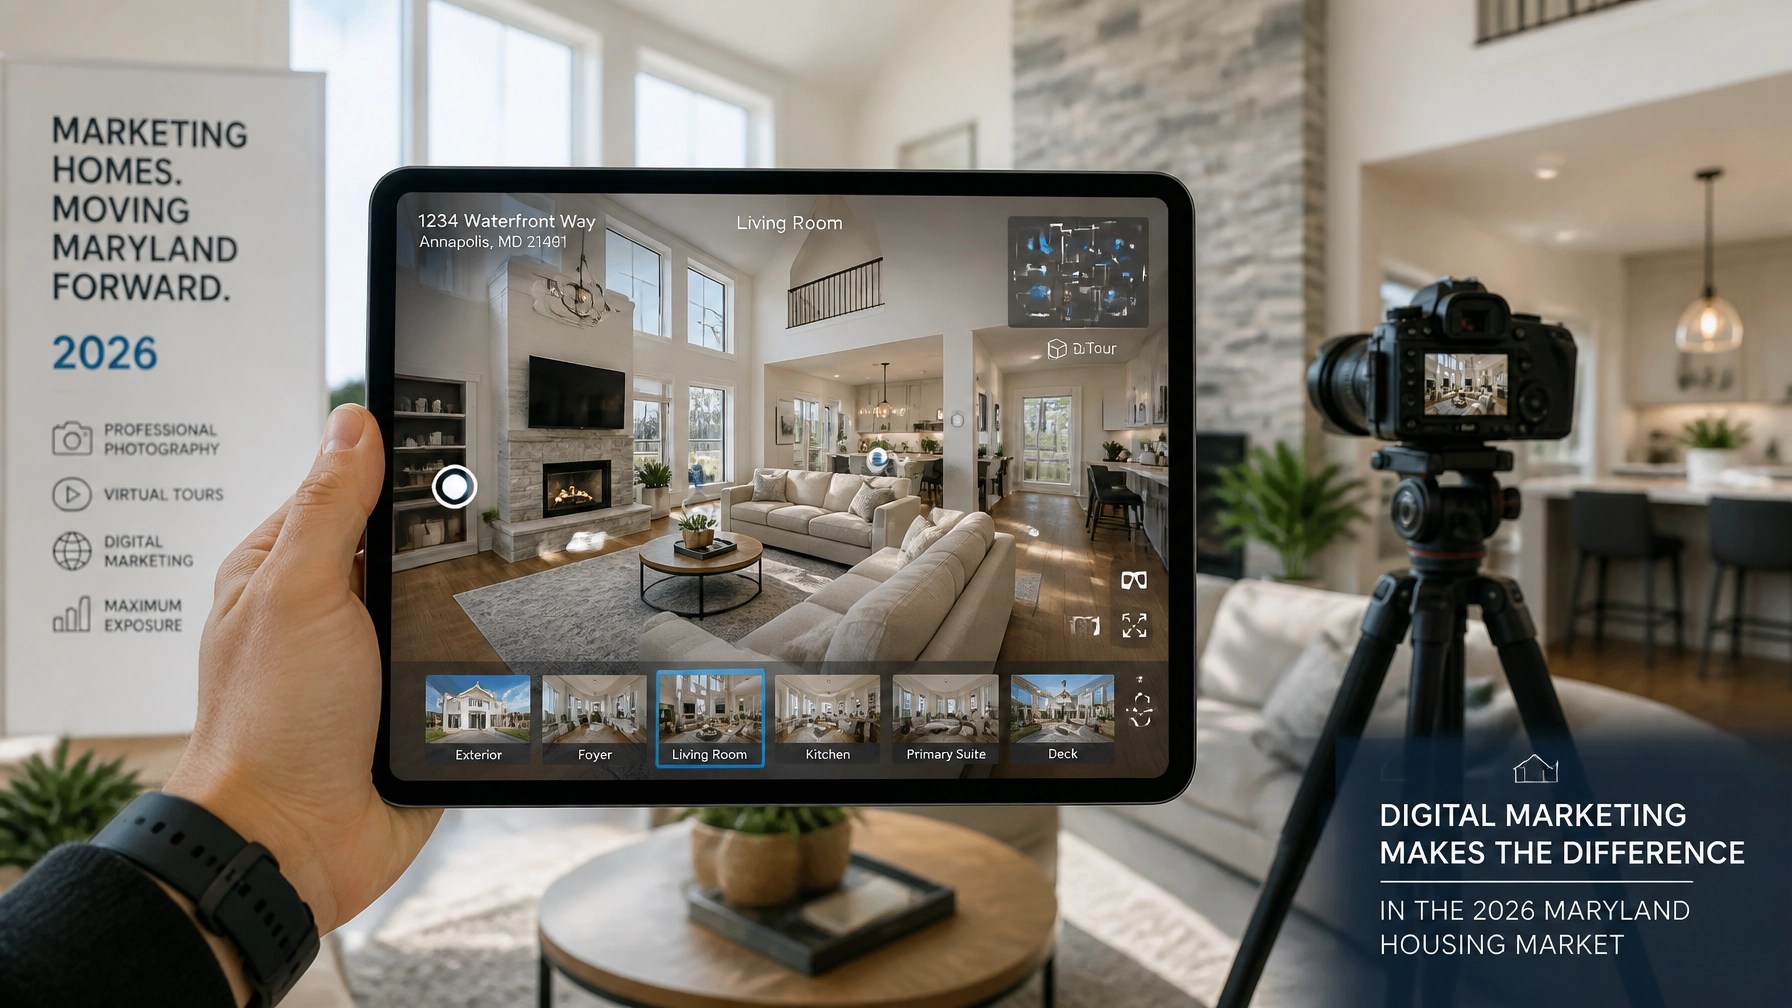
    A high-tech real estate marketing scene with a hand holding a tablet displaying a 3D virtual home tour of a modern living room, with a professional camera on a tripod in the background.

    8. Evaluating the Whole Offer (Not Just the Price)

    A high offer price is great, but in a 7% interest rate environment, the terms of the offer are just as important. In 2026, we are seeing more buyers use various financing programs to manage their rates.

    When you receive an offer, look at:

    • Type of Financing: Is it a conventional loan, VA, or FHA?
    • Contingencies: How long is the inspection period? Is the sale contingent on the buyer selling their own home?
    • Earnest Money: How much skin do they have in the game?
    • Closing Timeline: Does their move-out date align with your move-in date?

    A slightly lower price with "cleaner" terms (fewer contingencies and a solid lender) is often better than a high price that has a high risk of falling through.

    9. Neighborhood Micro-Trends Matter

    Real estate is hyper-local. What’s happening in Baltimore City is vastly different from what’s happening in Millersville or Gambrills.

    Before you list, look at the "comps" (comparable sales) within a 1-to-2-mile radius of your home from the last 90 days. Are homes in your specific neighborhood sitting for 30 days, or are they gone in a weekend? Understanding these micro-trends allows you to set realistic expectations for your own sale.

    10. The Modern Experience: Speed and Tech

    The 2026 real estate transaction is faster and more digital than ever. From electronic signatures to AI-driven market analysis, the process is streamlined. However, this speed requires sellers to be more prepared.

    Have your paperwork ready, have a plan for where you’re going next, and be ready to respond to offers quickly. In a competitive market, momentum is a seller's best friend.

    A 'SOLD' sign rider attached to a real estate sign post in front of a charming Maryland brick-front home with a peaceful neighborhood street in the background.

    Selling your home is a major financial and emotional milestone. By focusing on preparation, pricing, and professional representation, you can navigate the 2026 Maryland market with confidence. If you're looking for more information on the local market or want to see how current listings are being handled, you can learn more about Lamont Milbourne's approach here.

    Reply INFO and I'll send the next step.

  • Business Funding Awareness: What Every Entrepreneur Should Know About Credit and Capital

    Business Funding Awareness: What Every Entrepreneur Should Know About Credit and Capital

    A lot of entrepreneurs hear mixed messages about business funding.

    Some people get told they need perfect credit. Others get pitched “fast money” with big promises and no real explanation. That confusion causes a lot of business owners to chase shortcuts instead of learning how funding decisions really work.

    The better move is awareness.

    If you understand how credit, cash flow, business structure, and lender expectations fit together, you can ask better questions, avoid weak offers, and make smarter funding decisions for your business.

    What Entrepreneurs Often Miss About Credit and Funding

    A lot of business owners assume funding starts and ends with a credit score.

    That is only part of the picture.

    Many lenders and funding providers review what is often called the 5 Cs of Credit:

    • Character – your history of managing financial obligations
    • Cash Flow – whether money is consistently coming in to support payments
    • Capital – the resources you already have invested in the business
    • Collateral – assets that may help support certain types of financing
    • Conditions – the broader economy, industry trends, and purpose of the funding

    That matters because two business owners with similar scores can have very different outcomes based on the full picture.

    It also helps explain why different funding sources ask different questions. A bank, credit union, CDFI, grant program, or online lender may all evaluate risk differently. Knowing that upfront can help you avoid frustration and focus on learning which options may fit your situation.

    image_1

    What Lenders Commonly Look For

    When entrepreneurs hear “business funding,” they often think only about approval.

    A better question is: what are lenders actually reviewing?

    Your Credit Profile

    Credit still matters, but not just the score by itself.

    One key concept is credit utilization, which is the percentage of available revolving credit you are using. For example, if a card has a $10,000 limit and the balance is $3,000, utilization on that account is 30%.

    Lower utilization can signal better control of debt. Higher utilization can raise concerns, even if payments are current. That is why many business owners pay attention not only to whether they pay on time, but also to how much of their available credit they are using.

    Other common factors may include:

    • Recent payment history
    • Length of credit history
    • Number of recent inquiries
    • Mix of account types
    • Overall debt load

    Cash Flow and Stability

    Lenders also want to understand whether the business has steady financial activity.

    That may include:

    • Consistent deposits
    • Bank account management
    • Revenue trends
    • Basic documentation that supports the story the application is telling

    Business Readiness

    In many cases, lenders also look at how organized the business is.

    That can include things like:

    • Business formation
    • Separation between personal and business finances
    • Updated contact information
    • Clear business purpose for the funds
    • Accurate records

    These details may seem small, but together they can shape how a business is viewed.

    Red Flags to Watch Out For

    Before applying for any type of funding, it helps to know what can create problems.

    Red Flag #1: Applying Everywhere at Once

    Multiple applications in a short period can create extra inquiries and make your profile look rushed. It is usually smarter to slow down, understand the requirements, and narrow your options first.

    Red Flag #2: High Credit Utilization

    Even when payments are current, heavily used credit cards can be a warning sign. High balances compared to available limits may suggest financial pressure.

    Red Flag #3: Weak Business Setup

    If the business is not properly organized, it can raise questions. Missing basics like formal registration, separate accounts, or consistent information can make the process harder.

    Red Flag #4: Inconsistent Documentation

    If bank activity, stated income, business details, and supporting records do not line up, lenders may see risk or ask for more clarification.

    Red Flag #5: Big Promises With No Real Education

    Be careful with anyone promising instant approvals, easy money, or results without reviewing your actual situation. Good funding education should help you understand options, risks, and requirements, not pressure you with hype.

    image_2

    Funding Awareness: Knowing Your Options Matters

    A lot of entrepreneurs only think about one path: walking into a traditional bank and hoping for a yes.

    But business funding can come from several different places, and each option may have different standards, costs, timelines, and risks.

    Traditional Banks

    Banks may work well for established businesses with strong documentation, healthy cash flow, and time to go through a formal review process. They often have stricter requirements, but they are still an important part of the funding conversation.

    Credit Unions

    Credit unions may offer a more relationship-based experience. Some business owners prefer them because they can be more community-focused and easier to talk to than larger institutions.

    CDFIs

    Community Development Financial Institutions, often called CDFIs, are designed to support underserved communities and businesses that may not fit the typical bank model. They can be worth exploring for entrepreneurs who want to learn about mission-driven lending resources.

    Grants

    Grants can be attractive because they are not the same as loans, but they are often competitive and usually come with specific eligibility rules. Business owners should understand the requirements carefully and avoid assuming every grant is a fit.

    Online and Alternative Lenders

    Alternative lenders may offer different qualification models than traditional banks. Some may weigh revenue, time in business, or account activity differently. That does not automatically make them better or worse. It just means entrepreneurs need to review terms carefully and make sure they understand the full picture.

    Educational Membership and Resource Platforms

    Some people also look for educational platforms that help them better understand business credit, funding language, lender expectations, and financial organization. In that type of setting, Lamont’s role is as a liaison to information and resources, helping people review educational material so they can better understand how the process works.

    A Smarter Educational Approach

    Instead of chasing bold promises, entrepreneurs are usually better served by learning the basics first.

    That includes understanding:

    • How business and personal credit can affect funding conversations
    • Why utilization, payment history, and documentation matter
    • What questions to ask before applying
    • How different funding sources may evaluate risk
    • Which red flags can make the process harder

    This kind of awareness does not promise an outcome.

    It helps people become better prepared, better informed, and more confident when reviewing their options.

    If someone wants to learn more about the educational side of business funding awareness, Lamont can help point them to information and resources so they can review how it works for themselves.

    image_3

    The Real Takeaway

    Business funding awareness is not about hype.

    It is about understanding how lenders think, how your credit profile is being viewed, what documentation matters, and what options may exist beyond the first offer you see online.

    If you are an entrepreneur, one of the best things you can do is slow down and learn the landscape before making rushed decisions. A better question is not just “Can I get funding?” but also “Do I understand what I am applying for, why it fits, and what the tradeoffs are?”

    That kind of clarity can help you avoid unnecessary mistakes and ask better questions as you explore your next step.

    Review the information here when ready: www.mwrfinancial.com/krnrstn21


    Tweet Draft for Sonny:
    "Business funding awareness starts with better questions. New post breaks down the 5 Cs of Credit, credit utilization, common red flags, and alternative funding types entrepreneurs should understand before applying. Review here: www.mwrfinancial.com/krnrstn21"

    Note to Sonny: Please share this tweet draft for promotion. Flag this post to Lamont for approval before publishing because it discusses credit and business funding, which are compliance-sensitive topics.

  • 7 Business Credit Mistakes to Avoid in 2026 (And What to Do Instead)

    7 Business Credit Mistakes to Avoid in 2026 (And What to Do Instead)

    A lot of business owners work hard to grow revenue but never stop to look at what their business credit habits are saying behind the scenes.

    That matters in 2026.

    Business credit can affect how your company is viewed when you apply for financing, set up vendor relationships, or try to create more breathing room in your operations. And many problems do not start with one big mistake. They start with small habits that get ignored too long.

    The good news is most of these issues can be corrected with better awareness, stronger systems, and clearer financial habits.

    Let’s break down 7 business credit mistakes to avoid in 2026, and what to do instead.

    Mistake #1: Not Checking Your Business Credit Report

    The Problem: You cannot fix what you never review.

    A lot of owners monitor their personal credit but rarely look at their business credit profile. That creates blind spots. Reporting errors, outdated account details, or payment issues can sit there quietly while you keep moving like everything is fine.

    If you plan to grow, apply for financing, or build stronger vendor relationships, it helps to know what your business file actually says before someone else looks at it first.

    What to Do Instead: Build a simple review habit.

    Check your business credit reports on a regular basis. Look for incorrect account information, unfamiliar activity, reporting gaps, and anything that does not reflect the way your business really operates. You do not need panic. You need awareness.

    That one habit alone can help you ask better questions and make smarter financial decisions.

    image_1

    Mistake #2: Late Payments

    The Problem: Late payments can create problems that stick around longer than most people expect.

    It is easy to think, “I’m only a few days behind.” But payment history can influence how your business is viewed by creditors, vendors, and other decision-makers. One missed due date may not feel major in the moment, but repeated lateness can start to paint a bigger picture.

    And usually, late payments are not just a money problem. They are often a systems problem.

    What to Do Instead: Tighten up the process.

    Use calendar reminders, autopay where appropriate, and a simple bill-tracking system your team can actually follow. If bookkeeping has been inconsistent, this is a good place to clean it up. The goal is not perfection overnight. The goal is to make on-time payments the standard, not the exception.

    Mistake #3: Mixing Personal and Business Money

    The Problem: This one trips up more business owners than people realize.

    When personal and business expenses are constantly mixed together, it becomes harder to track what the business is really doing. It can create confusion in your records, make budgeting harder, and blur the financial story your business is telling.

    It may seem small when you swipe the wrong card once or twice. But over time, messy separation turns into messy reporting.

    What to Do Instead: Keep clean lines between the two.

    Use dedicated business accounts for business activity. Keep receipts organized. Document transfers clearly. If something gets mixed by accident, clean it up quickly and keep a record of it.

    Simple financial separation makes your business look more organized because it is more organized.

    Mistake #4: Maxing Out Credit Cards

    The Problem: Just because credit is available does not mean it should stay fully used.

    High balances can make it harder to manage cash flow and may affect how your business credit profile is viewed. Even business owners who pay regularly can run into issues if their balances stay too close to their limits for long stretches.

    This is one of those habits that can quietly become normal until it starts creating pressure.

    What to Do Instead: Leave more room on your limits.

    Pay attention to how much of your available credit you are using. If balances stay high month after month, that is worth reviewing. Sometimes the better move is not chasing more credit. It is improving how existing credit is managed.

    Better utilization habits can support healthier financial positioning over time.

    Motivational Finance Prompt Graphic

    Mistake #5: Applying Everywhere at Once

    The Problem: When business owners feel pressure, they sometimes start applying everywhere just to see what sticks.

    That approach can create more confusion than clarity. It may lead to unnecessary inquiries, mismatched applications, and a pile of offers or denials that do not really fit the business in the first place.

    More applications do not always mean better options. Sometimes they just mean more noise.

    What to Do Instead: Slow down and get clear first.

    Before applying, understand what type of financing or credit product you are even looking at, what the requirements may be, and whether it makes sense for your stage of business. Funding awareness matters here. Not every option fits every business, and rushing the process can make things harder.

    A smarter approach starts with information, not impulse.

    Mistake #6: Not Understanding Contracts

    The Problem: A lot of people focus on the approval and ignore the agreement.

    But terms matter. Fees matter. Repayment structure matters. Timing matters. If you do not understand what you are signing, you may end up committed to something that creates more stress than support.

    This is where business owners can get caught slipping, especially when they are moving fast and just want access to capital.

    What to Do Instead: Read slower than you want to.

    Take time to review the terms, ask questions, and make sure you understand what the agreement is asking from you. If something is unclear, do not guess. Get clarification from the provider or speak with a qualified professional when needed.

    Awareness now can prevent frustration later.

    image_2

    Mistake #7: Using Credit as a Crutch

    The Problem: Credit can be useful. But when it becomes the main thing holding the business together, that is a warning sign.

    If credit is constantly being used to cover routine shortfalls, patch cash flow gaps, or keep basic operations afloat, the real issue may not be the credit itself. The real issue may be what is happening underneath the surface.

    That is a hard truth, but it is an important one.

    What to Do Instead: Use credit like a tool, not life support.

    Look at the bigger picture. Review spending patterns, recurring expenses, revenue timing, and where pressure keeps showing up. The goal is to understand whether credit is supporting a plan or covering a problem.

    When you can identify the pattern, you are in a better position to make stronger decisions going forward.

    The Bottom Line

    Business credit mistakes are usually not about laziness. They are usually about missing information, weak systems, or habits that never got corrected.

    That is why awareness matters.

    If you are a business owner in 2026, this is a good time to step back and ask a few simple questions:

    • Do I know what is showing on my business credit profile?
    • Are my payment systems strong enough?
    • Am I keeping business finances clean and separate?
    • Am I using credit strategically or reactively?
    • Do I actually understand the agreements I sign?

    You do not need hype. You need clarity.

    Lamont shares information and resources designed to help people better understand business credit, funding awareness, and financial education so they can review their options more confidently and take a smarter next step.

    Review the information here when ready: www.mwrfinancial.com/krnrstn21


    Tweet Draft for Sonny:
    "Business credit mistakes can create problems long before you apply for anything. Here are 7 business credit mistakes to avoid in 2026, plus what to do instead. Simple, practical, and built around awareness over hype. [BLOG_LINK]"

    Notify Sonny: Tweet draft included.

    Flag for Lamont approval before publishing: Yes — business credit and funding awareness content.