When you're working toward financial clarity, your credit score often feels like the gatekeeper. It’s the number that stands between you and a better interest rate, a new car, or even that home in Maryland you’ve been eyeing.
📬 Join the Inner Circle — Get weekly financial clarity insights straight to your inbox. Most people don't know what's coming. You will. Subscribe now and get the unfair advantage.
In 2026, the tools we have to manage and understand our credit have evolved. Two of the most popular paths people take to improve their credit awareness are rent reporting services and credit builder cards.
But if you’re trying to decide where to put your energy (and your money), which one actually moves the needle? Is it better to report the rent you’re already paying, or should you open a new card designed specifically for building history?
Let’s break down the mechanics, the myths, and the real-world impact of both.
The New Frontier: What is Rent Reporting?
For decades, paying your rent on time did almost nothing for your credit score. You could pay $2,500 a month for ten years, and if you applied for a mortgage, the bank would look at your history and say, “Cool, but do you have a credit card?”
Rent reporting changed the game. These services act as a bridge. They verify your monthly rent payments and report them to the major credit bureaus (Experian, Equifax, and TransUnion) as a rental tradeline.
How It Works
- Verification: The service links to your bank account or communicates with your landlord to confirm you paid.
- Reporting: That payment is sent to the bureaus as a positive "on-time" mark.
- The Catch: Not all services report to all three bureaus. Some only hit one, which can lead to a "split" in your scores across different platforms.
According to data from Experian, roughly 75% of consumers who added rent to their files saw an increase in their scores, with many seeing a jump of at least 11 points. For someone who is "credit invisible": meaning they have no score at all: rent reporting can be a fast-track to becoming "scorable" in the eyes of a lender.

The Classic Route: Credit Builder Cards
While rent reporting is the "new kid on the block," credit builder cards are the tried-and-true veterans. These are typically secured credit cards or specialized accounts where you provide a security deposit that becomes your credit limit.
Why They Matter
Unlike rent reporting, a credit builder card creates a revolving tradeline. This is a big deal because it affects the two largest pieces of your credit score "pie":
- Payment History (35%): Just like rent, on-time payments help here.
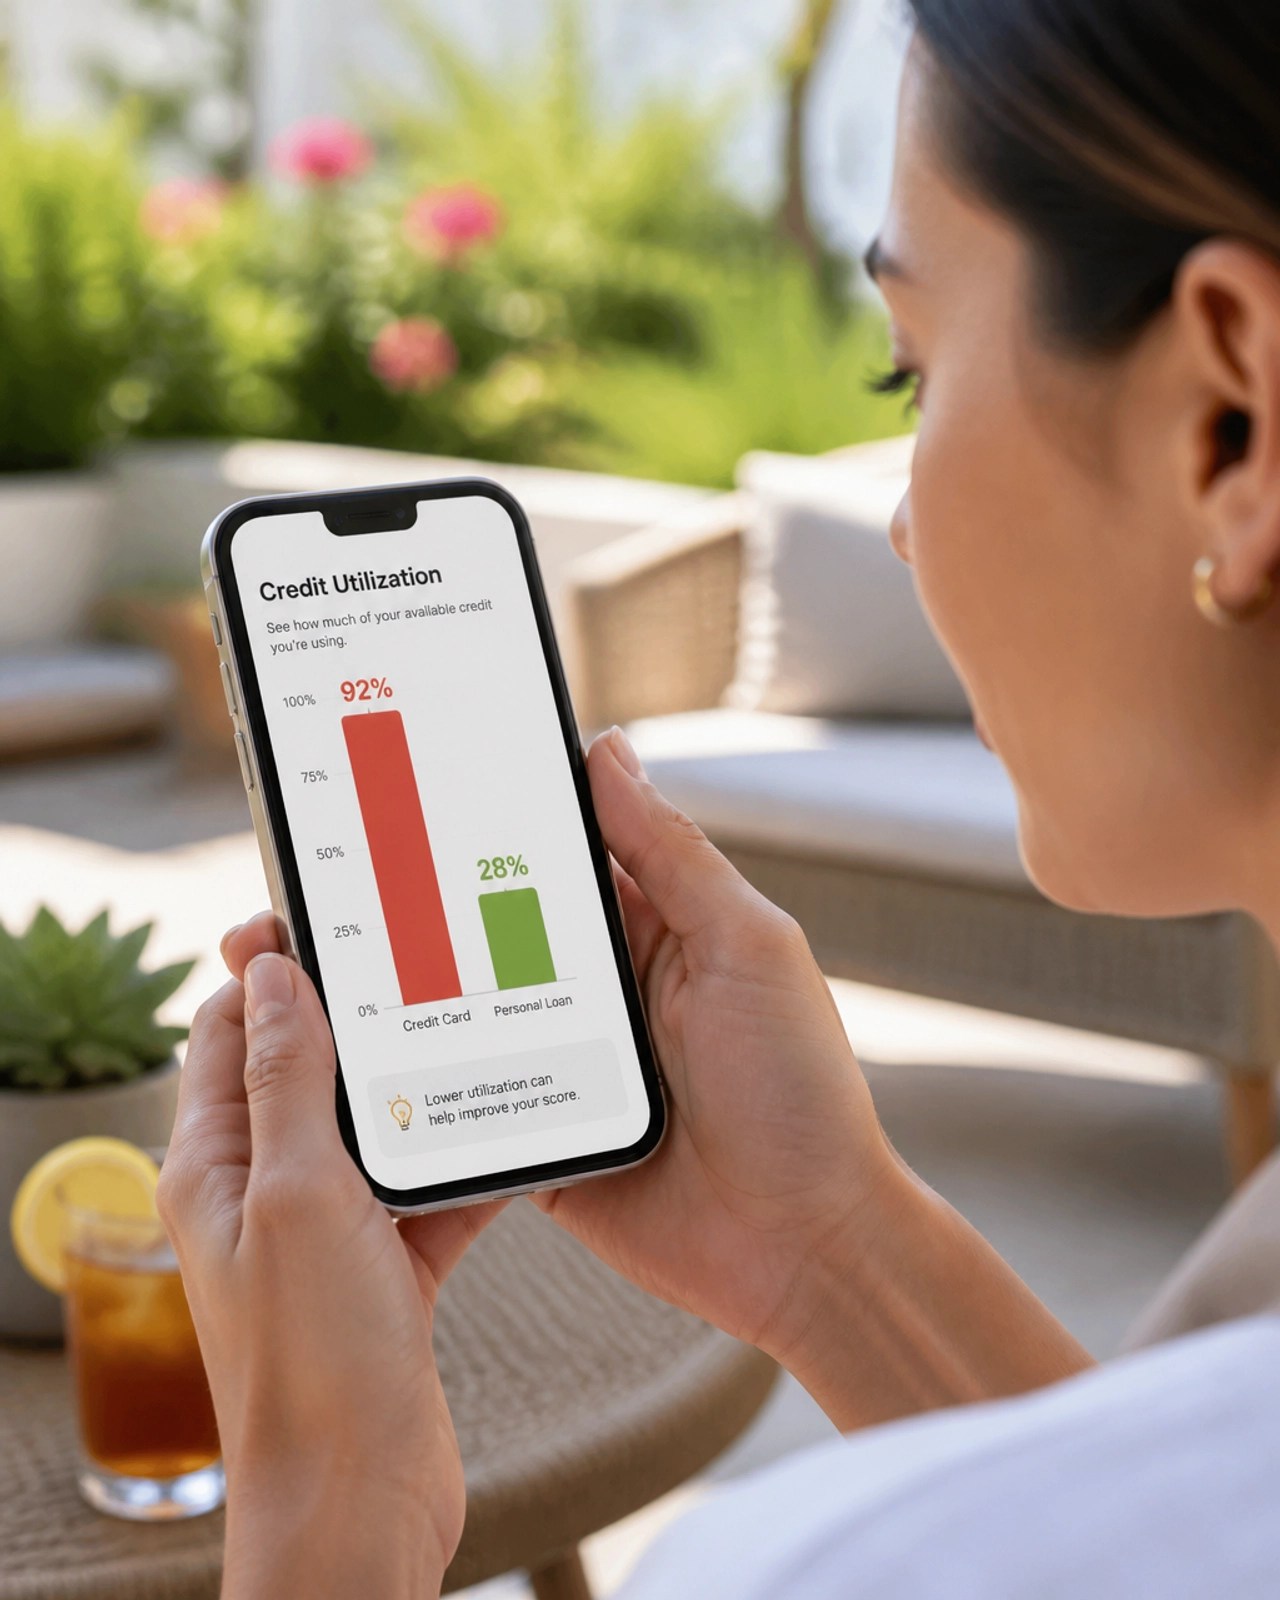
- Amounts Owed / Utilization (30%): This is where cards shine. By keeping a low balance relative to your limit, you show lenders you can handle credit responsibly without maxing it out.
The primary risk here? If you miss a payment or max out the card, you can actually see your score go down. Rent reporting doesn't carry the risk of "high utilization" because it’s not a debt account: it’s just a record of a bill paid.
FICO 8 vs. FICO 9 vs. VantageScore 4.0: The Technical Split
This is where it gets interesting. Not all credit scores are created equal. Depending on which "version" a lender uses, they might not even see your rent data.
- FICO 8: This is the most common model used by most credit card issuers and auto lenders. While it can include rent, it often gives it less weight than a traditional credit card.
- FICO 9 & VantageScore 4.0: These are newer, more modern models. They were designed specifically to be more inclusive. They love rent reporting and utility data. If your landlord reports your rent, these scores are usually the first to show the love.
- Mortgage Scores: If you’re buying a home, many lenders still use older FICO versions that might ignore rent reporting entirely. This is why having a "mix" of credit types is so important.

Myth-Busting: What These Tools Won't Do
At K-Stone Enterprises, we believe in education over hype. You’ll see plenty of ads claiming these tools "guarantee" a 100-point jump overnight. Let’s set the record straight:
- There are no guarantees. Every credit profile is unique. What works for a 22-year-old with no credit might not work the same way for a 45-year-old with a past bankruptcy.
- They don't erase bad history. Reporting your rent won't make a recent late payment on a car loan disappear. It simply adds "good" data to balance out the "bad."
- They aren't a "set it and forget it" solution. Building financial clarity is a habit, not a one-time transaction.
The Verdict: Which One Should You Choose?
So, which is better for your score? In 2026, the answer is usually both, but it depends on your starting point.
Strategy 1: The "Credit Invisible" Path
If you have no credit score at all, start with rent reporting. It’s the lowest risk because you’re already paying rent. It establishes a baseline and proves you have a history of meeting your financial obligations.
Strategy 2: The "Rebuilding" Path
If you have a score but it’s lower than you’d like, a credit builder card is often more powerful. Because it affects your utilization ratio, it has the potential to impact your FICO 8 score: the one most lenders actually use: more significantly than rent reporting.
Strategy 3: The "Wealth Building" Path
If you’re serious about total financial protection and awareness, you use both as part of a larger strategy. You report the bills you already have (rent, utilities) to broaden your file, and you manage a card to master your revolving credit.

Moving Toward Financial Clarity
Understanding the difference between these tools is the first step toward taking control of your financial narrative. Whether you are looking to buy your first home in Maryland or simply want to stop feeling stressed when you check your bank app, education is your best asset.
We don't provide credit repair or guarantees, but we do provide the map. When you have the right information, you can make decisions that lead to genuine peace of mind.
Are you ready to see how these pieces fit into your overall financial makeover?
Want this kind of insight every week? Join the Inner Circle — it's free and it keeps you ahead of the curve.
Want to talk it through? Call Rachel at +1 (227) 295-2046 and she'll get you connected to the right person.
Review the information here when ready: www.mwrfinancial.com/krnrstn21
Tweet Draft for Sonny:
"Rent Reporting vs. Credit Builder Cards: Which one actually moves the needle for your credit score in 2026? 🏠💳 We’re breaking down the pros, cons, and the FICO vs. VantageScore debate. No hype, just facts. Read more: [Link] #FinancialLiteracy #MarylandRealEstate #CreditAwareness"
🧵 Check out Twisted Emotions (Threaded Creations KLM) on Etsy — unique, handcrafted apparel that lets you wear your story. Browse the shop here: https://threadedcreationsklm.etsy.com