When it comes to your financial journey, there is one number that often feels like a mysterious gatekeeper: your credit score. For many, credit is a source of stress, confusion, or even fear. But here at K-Stone Enterprises, we believe that fear is usually just a lack of information. When you move with understanding, that fear turns into clarity, and clarity leads to smarter decisions.
📬 Join the Inner Circle — Get weekly credit and financial clarity insights straight to your inbox. Most people don't know what's coming. You will. Subscribe now and get the unfair advantage.
Financial education isn't about finding a "magic fix" or overnight "repair." It’s about building a foundation of awareness. Whether you are looking to buy a home in Maryland, start a business, or simply lower your monthly expenses, understanding how the credit system works in 2026 is the first step toward true financial empowerment.
This guide is designed to strip away the jargon and give you the fundamental building blocks of credit awareness. We aren't here to guarantee scores or promise quick results: we are here to provide the education you need to navigate the financial landscape with confidence.
What Exactly is a Credit Score?
Think of your credit score as a financial "shorthand." It is a three-digit number, typically ranging from 300 to 850, that summarizes the information in your credit reports. Lenders, landlords, and even some employers use this number to get a snapshot of how you’ve handled borrowed money in the past.
In 2026, the most common scoring model remains the FICO Score, used by approximately 90% of top lenders. While there are other models, like VantageScore, the goal is always the same: to estimate the likelihood that you will repay a loan on time.
A score around 670–700 is generally considered "good," while anything over 800 is considered "excellent." Most Americans fall somewhere between 600 and 750. Understanding where you sit on this scale is the starting point, but understanding why you are there is where the real power lies.
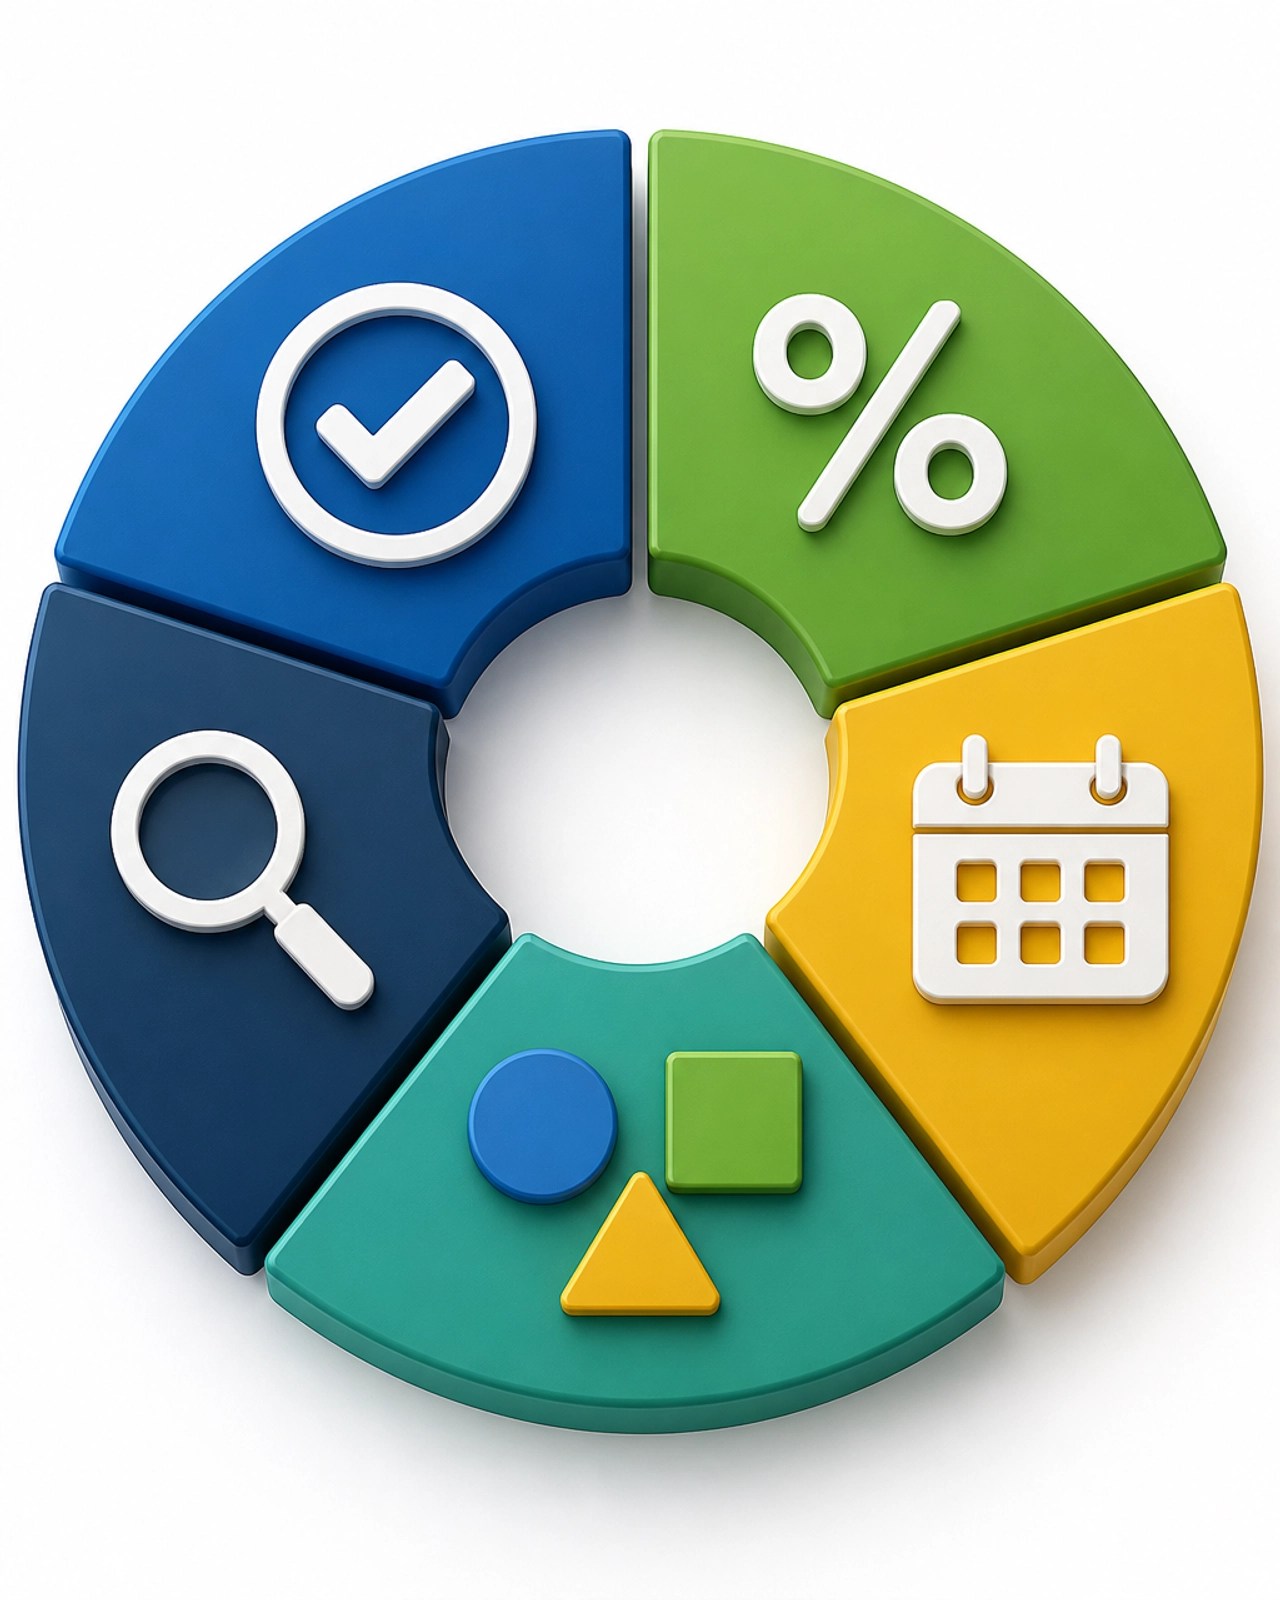
The 5 Pillars of Credit Awareness
To truly master your credit awareness, you have to look under the hood. Your credit score isn't a random number; it is calculated using five specific components. Knowing the weight of each component allows you to focus your energy on what matters most.
1. Payment History (35%)
This is the single most important factor in your score. Lenders want to know one thing above all else: Do you pay your bills on time? Even a single payment that is 30 days late can have a significant impact on your score. Consistent, on-time payments across all accounts: credit cards, auto loans, mortgages: build the foundation of a strong score over time.
2. Credit Utilization (30%)
This measures how much of your available "revolving" credit you are using. If you have a credit card with a $1,000 limit and you have a $900 balance, your utilization is 90%. In the world of credit awareness, high utilization is often seen as a sign of financial stress. Most experts suggest keeping this number below 30%, and those with the highest scores often keep it under 10%.
3. Length of Credit History (15%)
Experience matters. This pillar looks at how long your accounts have been open and the average age of all your accounts. This is why financial educators often suggest keeping your oldest accounts open: even if you don't use them frequently: as they provide the "age" that bolsters this part of your score.
4. Credit Mix (10%)
Lenders like to see that you can handle different types of credit responsibly. This might include "revolving" credit (like credit cards) and "installment" loans (like a car loan or a student loan). While you shouldn't take out a loan just to "mix it up," having a variety of accounts handled well can give your score a slight edge.
5. New Credit and Inquiries (10%)
Every time you apply for credit, a "hard inquiry" is recorded on your report. Opening several new accounts in a short period can signal risk to a lender. While the impact of a single inquiry is usually small and temporary, awareness of how often you are applying for new credit is a key part of long-term planning.
Financial Education: Moving with Clarity
Understanding these five pillars is like having a map. Without it, you’re just guessing. With it, you can see exactly which habits are helping you and which might be holding you back.
Education is about more than just numbers; it's about the lifestyle changes that keep you in the driver's seat. For example, did you know that your income is not a factor in your credit score? You could make $20,000 a year or $200,000 a year, and it won't change your score directly. What matters is the management of the debt you do have.

What’s New in 2026?
The financial world doesn't stand still. As we move through 2026, new models like FICO 10 and VantageScore 4.0 are becoming more widely used. These newer models are designed to give a more holistic view of your financial habits.
One of the most empowering shifts in recent years is the inclusion of "expanded data." Some 2026 models now allow for the inclusion of on-time rent and utility payments when calculating your score. This is a game-changer for people who may have "thin" credit files but have a long history of paying their monthly bills on time. Awareness of these new opportunities can help you leverage the payments you are already making to build a stronger financial profile.
Common Myths to Leave Behind
In our mission to provide financial clarity, we have to address some of the common myths that lead people astray:
- Myth: Checking your own credit score lowers it.
- Fact: Checking your own score is a "soft inquiry" and has zero impact on your score. In fact, checking your reports regularly for errors is one of the best habits you can form.
- Myth: Closing an old credit card "cleans up" your report.
- Fact: Closing an old account can actually lower your score by reducing your total available credit (increasing utilization) and shortening your credit history length.
- Myth: You need to carry a balance on your credit card to build credit.
- Fact: You do not need to pay interest to build credit. Paying your balance in full every month shows responsible usage and keeps your utilization low.
The Path to Financial Empowerment
At K-Stone Enterprises, Lamont Milbourne’s goal is to act as a liaison to information and resources. We don't believe in high-pressure tactics or unrealistic promises. We believe in the power of the "next step."
If you’re feeling overwhelmed by the complexity of the financial system, start small. Start by reviewing your information. Start by asking questions. Start by becoming aware. When you understand the "why" behind the numbers, you gain the ability to move with understanding and clarity.
Credit awareness isn't a destination; it's a practice. It’s about making small, consistent decisions that align with your long-term goals. Whether you want to qualify for a better mortgage rate, lower your insurance premiums, or simply have the peace of mind that comes with financial health, education is your greatest asset.
Want this kind of insight every week? Join the Inner Circle — it's free and it keeps you ahead of the curve.
Review the information here when ready: www.mwrfinancial.com/krnrstn21
Want me to send you the information so you can review how it works?
Reply INFO and I’ll send the next step.
Tweet for Sonny:
Financial Education 101: Stop guessing and start knowing. 🧠 Master your credit awareness by understanding the 5 pillars that actually drive your score. No "magic fixes," just real clarity for 2026. Read the full guide here: [Link] #FinancialEducation #CreditAwareness #KStoneEnterprises
🧵 Check out Twisted Emotions (Threaded Creations KLM) on Etsy — unique, handcrafted apparel that lets you wear your story. Browse the shop here: https://threadedcreationsklm.etsy.com
Leave a Reply