Category: Uncategorized

  • Business Credit Mastery: Scaling Your Venture in Prince George’s County

    Business Credit Mastery: Scaling Your Venture in Prince George’s County

    Let’s be real for a second: Prince George’s County is exploding. From the tech hubs in Bowie to the revitalization happening in Upper Marlboro and the bustling energy of National Harbor, the opportunity for entrepreneurs in PG County has never been higher. But here is the hurdle that stops most Maryland business owners in their tracks: capital.

    You have the vision, you have the hustle, but do you have the funding to actually scale?

    Most people think that to get a business loan, you have to put your personal life on the line. You’ve been told you need a perfect 800 credit score, three years of tax returns, and maybe even your firstborn child as collateral. We’re here to tell you that’s the "old way" of doing things. At MAKE WEALTH REAL, we focus on Business Credit Mastery. We’re talking about securing $50,000 or more in unsecured business funding without using your personal credit.

    If you’re ready to stop playing small and start leveraging the systems that big corporations use to dominate the Maryland market, this guide is for you.

    Why PG County is the Place to Build Right Now

    Prince George’s County isn't just another spot on the map; it’s one of the most opportunity-rich places in Maryland to build. But let’s keep it grounded: the statewide cost environment is real. In WalletHub’s 2026 ranking, Maryland landed as the 2nd worst state to start a business, with especially weak marks for labor costs and office-space affordability. That means local entrepreneurs are not just competing on ideas: they are competing in one of the country’s more expensive startup environments.

    At the same time, people are still building here every day. The Maryland SBDC reported 284 new business starts in 2025, which tells us two things: first, the entrepreneurial drive across the state is still strong; second, the competitive landscape is active. You are not entering an empty field. You are stepping into a market where more founders are launching, while the cost of operating remains high.

    That is exactly why strategy matters. Maryland is still ranked #1 for minority-owned businesses, the state has $198 million in federal SSBCI funding available to expand small-business lending, and the Maryland Department of Commerce has a $310.3 million FY 2026 operating budget supporting economic development priorities. With the Prince George’s County Economic Development Corporation (EDC) pushing major incentives and local programs already in motion, the environment still offers real upside, but only for entrepreneurs who are financially prepared.

    However, to tap into these resources and survive a high-cost environment, you need to be "Lender-Ready." Banks in Maryland aren't just looking for a good idea; they are looking for a solid business foundation.
    A professional Maryland business workspace showing a solid foundation for PG County entrepreneurs.

    Step 1: Getting "Lender-Ready" in Maryland

    Before you even think about applying for that $50k unsecured funding, your foundation must be rock solid. If your business looks like a "hobby" on paper, the banks will treat it like one. In Maryland, being lender-ready means:

    1. Formal Structure: You need an LLC or Corporation registered with the Maryland Department of Assessments and Taxation (SDAT). If you’re still operating as a sole proprietorship, you’re essentially telling lenders that you and the business are the same entity. That’s a red flag for business credit.
    2. The EIN and Address: Get your IRS EIN, and make sure your business address is a physical location or a dedicated virtual office: not a P.O. Box.
    3. Business Banking: This is non-negotiable. You must have a dedicated business checking account. All business income and expenses should flow through this account. Lenders look at your average daily balance and your "bank rating" to determine how much they can trust you with.

    Step 2: Building Your Business Credit Profile (The D&B Secret)

    This is where the magic happens. Business credit is tied to your EIN, not your SSN. When built correctly, your business becomes its own "person" in the eyes of the law and the banks.

    To master your business credit in PG County, you need to get listed with the big three: Dun & Bradstreet, Experian Business, and Equifax Business.

    Start by obtaining your D-U-N-S number. From there, you start working with "Net-30" vendors. These are companies that allow you to buy supplies now and pay them back in 30 days. When they report those on-time payments to the bureaus, your business credit score (often called a Paydex score) starts to climb.

    The goal? A score of 80 or higher. Once you hit that mark, doors start opening that don’t require you to sign a personal guarantee.

    Motivational Finance Prompt Graphic

    Step 3: Accessing $50k in Unsecured Funding

    Why $50,000? Because for most small businesses in Maryland, $50k is the "sweet spot." It’s enough to hire that first key employee, launch a massive marketing campaign in the DMV area, or stock up on inventory for a major contract.

    At MAKE WEALTH REAL, we show you how to access these funds through unsecured lines of credit. "Unsecured" means no collateral. No putting your house up as a backup. No pledging your equipment.

    How do we do it? By leveraging the strength of your business profile. In Prince George’s County, we have access to local institutions like the Prince George’s Community Federal Credit Union, which offers business lines of credit up to $25,000 completely unsecured for established businesses. When you combine those local resources with the national lenders we work with at MWR, hitting that $50k mark becomes a systematic process, not a pipe dream.

    Step 4: Leveraging Local PG County Incentives

    Don't leave money on the table. Scaling in Prince George’s County means taking advantage of the specific programs designed to help you succeed, while also understanding the bigger Maryland funding picture backing small-business growth.

    • FSC First: This is a powerhouse for local entrepreneurs. They offer a Small Business Capital and Growth Stimulus Fund. If you’re in the tech space or a growth-stage business, you could qualify for grants up to $10,000 that don’t need to be paid back.
    • SSBCI-backed Lending Opportunities: Maryland has $198 million in federal State Small Business Credit Initiative (SSBCI) funding available to strengthen small-business lending through state-supported programs. For Prince George’s County founders, this matters because these dollars are specifically designed to increase access to capital, especially for underserved businesses and entrepreneurs who may not fit the traditional bank box on day one.
    • Maryland Commerce Support: The $310.3 million FY 2026 operating budget for the Maryland Department of Commerce shows that business growth is not an afterthought in this state. That broader investment helps reinforce programs, partnerships, and financing channels that entrepreneurs in Prince George’s County can tap into as they scale.
    • The EDI Fund: The Economic Development Incentive Fund is a $50 million pot of gold for businesses that are expanding and creating jobs in the county.
    • Enterprise Zones: If your business is located in designated zones within the county, you could be eligible for significant real property tax credits.

    The real play in Prince George’s County is stacking these opportunities. You build your business credit profile, get lender-ready, position yourself for local county incentives, and then pursue Maryland-backed lending channels fueled by SSBCI and broader Commerce support. In a state now ranked near the bottom for startup affordability, that kind of structure is not optional: it is how serious entrepreneurs stay alive long enough to grow. That is how local entrepreneurs move from surviving to scaling.

    When you combine business credit mastery with these local incentives, you aren't just "starting a business": you’re building with a plan that can handle real Maryland costs.
    Modern PG County office representing business credit mastery and economic growth in Maryland.

    Step 5: The Power of Procurement

    One of the best ways to scale your venture is by securing government or corporate contracts. The Prince George’s Chamber of Commerce offers an Equity in Procurement (EIP) program. They connect local businesses with giants like Pepco, Clark Construction, and Luminis Health.

    Having a high business credit score makes you much more attractive for these contracts. Large corporations want to know that their suppliers are financially stable. Your business credit report is your "resume" for these big deals.

    Stop Stressing, Start Scaling

    The difference between the businesses that thrive in Maryland and those that fold under pressure isn't just the quality of the product: it’s the access to capital. In a state where WalletHub’s 2026 data flags labor and office costs as major barriers, having the right financial strategy can be the difference between momentum and burnout.

    You shouldn't have to drain your personal savings or ruin your personal credit score to chase your dreams. There is a better way. By following the MAKE WEALTH REAL blueprint, you can build a business that stands on its own two feet.

    We’ve seen entrepreneurs in Bowie, Laurel, and Oxon Hill transform their financial lives by simply shifting how they view credit. It’s time to stop being a "consumer" and start being a "capitalist."

    Take the Next Step

    Are you ready to unlock the secrets to $50k+ in unsecured funding? Do you want to join a community of Maryland entrepreneurs who are actually making wealth real?

    Join our Skool community today! We dive deep into the funding secrets, the "lender-ready" checklists, and the exact steps you need to take to scale your Prince George’s County venture to the moon.
    Diverse business owners in Maryland celebrating a successful financial transformation and growth.

    Ready for your Financial Transformation?
    Don’t wait for the banks to find you. Take control of your financial destiny now. Join the MWR membership and start your Financial Makeover today.

    Join the movement here: www.mwrfinancial.com/krnrstn21

    For more information on our programs and how we help you increase your cash flow, eliminate debt, and build business credit, visit the authoritative source: www.mwrfinancial.com.


    Tweet Draft for Sonny:
    "🚀 Scaling a business in Prince George’s County? Stop using your personal credit! Learn how to secure $50k in unsecured business funding and master the Maryland market. Check out the latest blog from @MAKEWEALTHREAL Maryland! 🦀💼 #BusinessCredit #PGCounty #MWRFinancial #MarylandEntrepreneurs"

  • Why Maryland Professionals are Drowning in Bills (and the Simple Way to Stop It)

    Why Maryland Professionals are Drowning in Bills (and the Simple Way to Stop It)

    If you live in Maryland and work as a professional: whether you’re a healthcare hero in Baltimore, a tech expert in Bethesda, or a policy pro in Annapolis: you’ve likely noticed something unsettling lately. You’re making "good money," yet your bank account feels like a leaky bucket.

    You’re not imagining it. Maryland professionals are currently being squeezed by a perfect storm of rising utility costs, high taxes, and a cost of living that seems to have a mind of its own. It’s a phenomenon we call the "Squeezed Middle." You earn too much to qualify for state assistance programs, but you’re not "wealthy enough" to ignore a Baltimore Gas & Electric (BGE) bill that suddenly doubles overnight.

    At MAKE WEALTH REAL, we see this every day. You’re working harder, but the "finish line" of financial freedom keeps moving further away. The good news? It’s not about how much you make; it’s about how much you keep. There is a simple, systematic way to stop the bleeding and start building a legacy, and it starts with understanding why the game is rigged against you right now.

    The Maryland Squeeze: Why Your Bills Are Skyrocketing

    Recent data shows that Marylanders are getting hit with some of the most aggressive utility pressure in the country. As of May 2026, BGE base gas distribution rates are approximately 94 to 98 cents per therm, and electric distribution rates are around 4.9 cents per kWh. On top of that, BGE’s February 2026 reconciliation charge added roughly 3.5 cents per therm for gas and 0.1 cents per kWh for electric. For many households, that means the delivery side of the bill keeps climbing even when usage stays relatively steady. Gas delivery rates have also nearly tripled since 2012, which helps explain why bills feel so much heavier than they used to.

    Why is this happening to us?

    1. Infrastructure Upgrades: Utilities are passing the multi-billion dollar costs of modernization and "net-zero" goals directly to you.
    2. Delivery Fees: Even if you turn off every light in the house, the "delivery and service fees" remain high.
    3. The "Energy Gap": Maryland doesn't generate enough of its own power, making us dependent on regional markets where prices fluctuate wildly.

    For the Maryland professional, this isn't just an annoyance: it’s a threat to your lifestyle. When your fixed costs (utilities, insurance, taxes) spike, your "discretionary" income: the money you use for vacations, investments, and your kids' college funds: evaporates.

    Maryland professional reviewing high monthly utility and insurance bills in a Baltimore office.

    Why "Budgeting" Isn't Enough for Professionals

    We’ve all heard the traditional advice: "Stop buying lattes" or "Eat out less." But for a professional making $100k, $200k, or more, the problem isn't the $5 coffee. The problem is the Big Four wealth killers:

    • Taxes: You’re likely in the highest tax bracket, losing 30-40% of your income before it even hits your account.
    • Interest: Between Maryland mortgages, car notes, and student loans, you’re paying a "wealth tax" to the banks.
    • Big Bills: Cell phone, internet, cable, and those surging Maryland utilities.
    • Inflation: The silent thief that makes every dollar you save worth less by the time you go to spend it.

    If you try to solve these problems by just "working more," you’ll eventually hit a wall. You only have 24 hours in a day. To stop drowning in bills, you don't need a second job; you need a Financial Makeover.

    The Simple Way to Stop the Bleeding

    At MAKE WEALTH REAL, we believe in Empowering our members to take control of their cash flow without having to live a life of sacrifice. We focus on four specific pillars that work together to put money back in your pocket immediately.

    1. Expert Bill Negotiation

    You probably don't have three hours to sit on hold with BGE, Comcast, or Geico to argue for a better rate. Our experts do it for you. We have professional negotiators who know the "secret" codes and loyalty discounts that service providers never tell you about.

    • The Result: Our members often see hundreds of dollars in monthly savings on bills they were already paying. It’s like giving yourself a raise without asking your boss.

    2. Tax Shifting

    This is the big one for Maryland professionals. Because you have a high income, you are the IRS’s favorite customer. By utilizing the same strategies the wealthy use: including home-based business deductions: you can legally and ethically shift your tax dollars back into your own pocket.

    • The Result: Imagine seeing an extra $300 to $1,000 in your paycheck every single month because you adjusted your withholdings based on expert advice.

    3. Debt Elimination (The Debt Shredder)

    Interest is a parasite. If you have a mortgage in Columbia or student loans from Johns Hopkins, the interest is eating your future. Our "Debt Shredder" technology uses a mathematical algorithm to show you exactly how to pay off every cent of your debt (including your mortgage) in record time, without spending a penny more than you are right now.

    Motivational Finance Prompt Graphic

    4. Cash Flow Management

    We help you set up a system where your bills are predictable and your savings are automated. Instead of being reactive to the next BGE spike, you become proactive.

    Taking Action: A Maryland Professional’s Checklist

    You can’t control what the Public Service Commission approves for utility rates, but you can control your internal economy. Here is your "stop the drowning" checklist:

    1. Audit Your Bills: Take 30 minutes this weekend to look at your BGE, water, and insurance bills. Are you paying for "extras" you don't use?
    2. Check Your Tax Withholding: If you get a big refund every year, you’re giving the government an interest-free loan while you struggle to pay your monthly bills. Stop that immediately.
    3. Leverage a System: Stop trying to be your own accountant, bill negotiator, and financial planner.

    Why MWR Financial is the Game Changer

    The reason most people stay "drowning" is that they don't have the time to fix the leaks. You’re busy living your life, building your career, and taking care of your family.

    The MAKE WEALTH REAL lifestyle membership gives you access to a team of experts: Enrolled Agents (the highest credential the IRS awards), professional negotiators, and credit experts: who do the heavy lifting for you. We provide the "Simple Way" because we automate the wealth-building process.

    S.I.M.P.L.E Leverage Everything! Weekly Event Promotional Graphic

    Whether it’s shifting your taxes, lowering your bills, or crushing your debt, the goal is the same: Increasing your cash flow so you can live the life you’ve earned.

    Maryland is a beautiful place to live, but it’s expensive. You shouldn't have to choose between a comfortable retirement and your current lifestyle. By leveraging the right tools, you can have both.

    Are You Ready to Stop the Squeeze?

    The bills aren't going to lower themselves. The Maryland government is working on "Relief Acts," but those take time and often provide only a drop in the bucket ($150 a year doesn't help much when your bill is $1,200).

    You need a private solution for a public problem. It’s time to stop letting your hard-earned money leak out of your household and start keeping what is rightfully yours.

    MWR @Home Opportunity Promotion

    Join the thousands of Marylanders who have decided that "enough is enough." Take back control of your financial future today.

    Join our lifestyle membership and start your Financial Transformation at www.mwrfinancial.com/krnrstn21.

    For more information on our programs and how we help you Make Wealth Real, visit the authoritative source at www.mwrfinancial.com.


    Tweet Draft for Sonny:
    "Maryland professionals: Are your utility bills feeling like a second mortgage? 💸 Stop the squeeze! Learn the 'Simple Way' to reduce bills, shift taxes, and crush debt. Check out our latest blog: Why MD Professionals are Drowning (and how to stop). #MWRFinancial #MarylandWealth #BillReduction"

  • The Wealth Blueprint: How Annapolis Families Are Building Multi-Generational Legacies

    The Wealth Blueprint: How Annapolis Families Are Building Multi-Generational Legacies

    Annapolis is a city defined by its history. From the colonial brick streets of downtown to the enduring traditions at the Naval Academy, we are surrounded by things that last. But when it comes to our personal finances, many families in Maryland are realizing that "making good money" isn't the same thing as "building a legacy." That distinction feels even more real in a market where the median sale price in Annapolis is around $622,000 as of May 2026, homes are typically spending about 35 days on market, and local forecasts point to roughly 2% to 4% price growth through the rest of the year.

    We’ve all heard the staggering statistic: 70% of wealthy families lose their fortune by the second generation, and 90% lose it by the third. It’s a cycle of building, spending, and dissolving. But it doesn't have to be that way.

    Right here in Annapolis, a new wave of families is moving away from traditional, "cross-your-fingers" financial planning. They are building a Wealth Blueprint: a strategic, multi-generational approach to asset protection, tax efficiency, and private reserves. At MAKE WEALTH REAL, we believe wealth shouldn’t just be a lucky break for one generation; it should be a foundation for every generation that follows.

    What is Multi-Generational Wealth, Really?

    Most people think multi-generational wealth is just about leaving a big life insurance check or a house to their kids. While that’s a start, true legacy is about creating a Financial Engine that continues to run long after you’ve retired to the Shore.

    In Annapolis, that conversation has to be rooted in reality. When the median home sale price is about $622,000, even a modest move, refinance decision, or delayed purchase can have a major impact on a family’s balance sheet. With homes still moving in roughly 35 days and values expected to rise another 2% to 4% this year, local families need a plan that accounts for higher housing costs, tighter affordability, and the opportunity to build equity intentionally instead of letting rising costs dictate every money decision.

    It’s about having a plan for how your assets are built, how they are shielded from Uncle Sam (especially with Maryland’s specific tax climate), and how your family is educated to manage that wealth. Without a blueprint, you’re just leaving behind a pile of cash that the world is waiting to take back through taxes, interest, and inflation.

    Pillar 1: Plugging the Leaks (Tax and Interest Strategies)

    You can't build a skyscraper on a cracked foundation. In Maryland, we deal with some of the more complex tax structures in the country. Between federal taxes and our local state taxes, many Annapolis business owners and high-income earners are overpaying by thousands: sometimes tens of thousands: of dollars every single year.

    That is money that should be going into your family’s legacy. In a city where buying or keeping a home often means planning around a $622,000 median price point, every dollar you recover from unnecessary taxes matters more. Lowering tax drag can help create room for emergency reserves, business capital, education planning, or a stronger housing position in a market where properties still move in about 35 days.

    The first step in the MWR Financial Makeover is Tax Reduction. Our experts look at your current situation to ensure you are taking advantage of every legal deduction available. We shift you from a "tax victim" to a "tax strategist." By keeping more of your hard-earned Maryland income, you create the immediate cash flow needed to fund the rest of your legacy.

    Next, we look at Debt Elimination. You cannot build multi-generational wealth while paying 20% interest to a bank. We use the "Million Dollar Blueprint" to help families pay off mortgages, student loans, and credit cards in record time: without spending a penny more than they are right now.

    Multi-generational family on an Annapolis pier symbolizing a secure Maryland financial legacy.

    Pillar 2: The Private Reserve Account (Being Your Own Bank)

    This is the "secret sauce" for many of the wealthiest families in the country, and it’s a core part of what we teach at MAKE WEALTH REAL. Most people put their money in a traditional bank where it earns 0.01% while the bank lends it out to your neighbors for 7%.

    What if you could flip the script?

    A Private Reserve Account (PRA) allows you to build a pool of capital that grows with compound interest, tax-favored, while still allowing you to access that money for major purchases: like a new car, a business investment, or a child’s tuition.

    When Annapolis families use a PRA, they aren't just saving money; they are creating a family bank. That can be especially powerful in a local market where a median-priced home sits around $622,000 and values may climb another 2% to 4% this year. Instead of being caught flat-footed by rising down payment needs, repair costs, or opportunity-driven purchases, families with private reserves are better positioned to respond with control. Instead of paying interest to a faceless corporation, the "interest" stays within the family ecosystem. This is how legacies are protected and multiplied over decades.

    Pillar 3: Asset Protection and the Maryland Landscape

    Wealth attracts attention: and not always the good kind. As you build your legacy in Annapolis, protecting your assets from lawsuits, predators, and excessive probate costs is vital.

    Asset protection isn't just for billionaires. If you own a business or have a growing portfolio of investments, you need to ensure those assets are shielded. This involves proper entity structuring and ensuring your estate plan is airtight.

    In Maryland, estate taxes and probate can be a headache for those who haven't planned ahead. A Wealth Blueprint ensures that when it’s time to pass the torch, your heirs aren't stuck in a legal nightmare or forced to sell off assets just to pay the tax bill. We focus on "Succession, not just Success."

    Motivational Finance Prompt Graphic

    Pillar 4: Education and the "Stewardship" Mindset

    The biggest threat to your family's wealth isn't the stock market: it’s the mindset of the people inheriting it. If the next generation doesn't understand how the money was made or how to keep it, it will vanish.

    Building a legacy requires a family culture of financial literacy. At MAKE WEALTH REAL, we encourage our members to involve their families in the process.

    • Talk about the "Private Reserve."
    • Explain why we focus on tax deductions.
    • Show them the power of compound interest.

    By moving away from "taboo" money conversations and moving toward transparent financial leadership, you prepare your children to be stewards of the wealth, not just consumers of it.

    The MWR Advantage: Experts on Your Side

    The reason most people never finish their "Wealth Blueprint" is that it’s overwhelming. Between taxes, credit, debt, and investing, where do you start?

    That’s why MWR Financial is a game-changer for Maryland families. We don’t just give you a book and wish you luck. We provide the experts who do the work for you.

    • Enrolled Agents to handle your taxes.
    • Credit Experts to optimize your score.
    • Financial Strategists to map out your debt elimination and land banking/private reserve strategies.

    We provide the tools; you provide the vision. Whether you are a business owner in Eastport or a professional working near the State House, the goal is the same: Financial Freedom that lasts.

    Close-up of a golden wealth blueprint on a desk for building multi-generational wealth in Annapolis.

    Start Your Annapolis Legacy Today

    Wealth isn't built overnight, but the plan for wealth can be. You don't have to be a financial genius to secure your family's future: you just need the right system and the right team.

    And in Annapolis, that plan should reflect what families are actually facing on the ground: a median sale price near $622,000, an average market pace of about 35 days, and a projected 2% to 4% rise in values this year. Those numbers make it clear that wealth building here isn't just about motivation. It's about strategy, cash flow, protection, and positioning.

    Don't let another year of Maryland taxes and bank interest erode what you're trying to build for your kids and grandkids. It’s time to stop guessing and start growing.

    Ready to Build Your Blueprint?

    If you're ready to take control of your financial destiny and start building a legacy that will be talked about for generations, we invite you to join our community.

    Join our Skool community today for exclusive training, live calls, and the support you need to achieve total financial freedom.

    👉 Start Your Financial Transformation Here

    Let’s make wealth real for you and your family.


    Tweet Draft for Sonny:
    "Annapolis families: Is your wealth built to last, or just for right now? ⛵️ We’re diving deep into the Multi-Generational Wealth Blueprint: covering everything from Maryland tax strategies to Private Reserves. Stop leaving your legacy to chance! 🏛️ Read more: [Link] #MWRFinancial #AnnapolisWealth #FinancialFreedom #LegacyBuilding"

  • Investing in Baltimore: Why Land Banking is the Ultimate Wealth-Building Move

    Investing in Baltimore: Why Land Banking is the Ultimate Wealth-Building Move

    If you’ve been keeping an eye on the East Coast real estate market lately, you know that Baltimore isn't just a city of rowhomes and crabs: it’s a city of immense, untapped potential. For the savvy investor, the "Charm City" offers something much deeper than a quick flip or a standard rental. We’re talking about Land Banking.

    Now, if you haven’t heard the term "land banking" tossed around in your inner circles yet, pay attention. This isn't just about buying a plot of dirt and hoping for the best. In a city like Baltimore, where history and future development are currently colliding, land banking is the ultimate chess move for building legacy wealth.

    Let’s break down why this strategy is a game-changer in 2026 and how you can position yourself to win big in the MD market.

    What Exactly is Land Banking?

    In its simplest form, land banking is the practice of acquiring undervalued land or distressed property in the path of future growth. You buy it, you hold it, and you wait for the market to catch up to your vision.

    In Baltimore, this often takes the form of acquiring vacant properties or lots in neighborhoods that are slated for revitalization. While others are fighting over overpriced "turnkey" properties in fully gentrified areas, land bankers are looking at the 14,000+ vacant properties in Baltimore and seeing a gold mine.

    Real estate investor viewing historic Baltimore rowhomes, identifying land banking opportunities in Maryland.

    The Baltimore Landscape: Where We Are in 2026

    To understand why now is the time to strike, we have to look at what’s been happening over the last couple of years. Back in late 2024, there was a lot of talk about the city creating a formal "Land Bank Authority." While the City Council eventually shifted gears to focus on Tax Increment Financing (TIF) and massive bond packages, the core mission remained: getting vacant properties back into the hands of people who will build something meaningful.

    Mayor Brandon Scott’s $3 billion initiative to eliminate blight has poured fuel on the fire. We are seeing massive investments in areas like Park Heights, East Baltimore, and Sandtown. When the city commits $65 million specifically for renovating vacants and supporting Community Land Trusts (CLTs), that is a signal to investors that the "path of progress" is being paved with taxpayer dollars.

    Why Baltimore? Why Now?

    1. Low Barrier to Entry: You can still find properties in Baltimore for "pennies on the dollar." We’re talking anywhere from $500 to $30,000 for assets that have the potential to be worth ten times that in a few years.
    2. The Blight Elimination Initiative: The city is actively trying to get rid of vacants. This means there are fewer bureaucratic hurdles than there were five years ago.
    3. Legacy Wealth: Land banking isn't a "get rich quick" scheme. It’s a "get wealthy for generations" strategy. By holding these assets, you aren't just betting on a house; you’re betting on the literal footprint of the city.

    The Strategy: How to Bank Land Like a Pro

    Success in land banking requires more than just a checkbook; it requires a local perspective. You need to know which blocks are being targeted for TIF funding and which ones are still ten years away from a turnaround.

    Focus on the "Path of Progress"

    Look at South Baltimore. The South Baltimore Community Land Trust has been a beacon for how to do this right. By acquiring land in areas where the community is actively involved in reinvestment, you ensure that your asset isn't just sitting in a vacuum: it's part of a growing ecosystem.

    Sleek modern property renovation next to traditional brick homes in a revitalized Baltimore neighborhood.

    Diversify Your Hold

    Don't just buy one lot. If you have the capital, "banking" multiple parcels in a specific ZIP code increases your leverage. When a major developer comes in and wants to build a shopping center or a luxury apartment complex, they don't want one lot; they want the whole block. If you own three of those lots, you’ve just become their most important phone call.

    The "Investor Ready" Advantage

    I see a lot of investors jump into the Baltimore market with big dreams and zero preparation. They buy a property in a "hot" ZIP code only to realize they have no idea what the After Repair Value (ARV) actually is, or they get quoted a rehab budget that eats their entire margin.

    This is where I come in. If you’re serious about land banking or investing in Baltimore real estate, you can’t afford to wing it. My Paid Funding Preparation Service is designed to take the guesswork out of the equation.

    When you work with me, I don't just give you a "good luck" pat on the back. We provide a full Investor Ready Package that includes:

    • Deep-Dive Deal Analysis: Is it actually a deal? We run the numbers so you don't have to.
    • ARV Comps: We look at what the market is actually doing in 2026, not what it did three years ago.
    • Rehab Budgets: Real-world estimates so you aren't blindsided by contractor costs.
    • Loan Submission Packages: We have direct lines to Real Brokerage lending partners who understand the Baltimore market. We package your deal so it’s "bank-ready" from day one.

    Investing is about risk management. My goal is to lower your risk and maximize your legacy.

    Pique Meme

    Social Impact Meets Profit

    One of the coolest things about land banking in Baltimore right now is the ability to do well by doing good. By acquiring and eventually developing (or selling to a developer) these vacant spaces, you are helping to heal the scars of redlining and disinvestment that have plagued the city for decades.

    Building wealth shouldn't happen in a vacuum. When you invest in Baltimore’s land, you’re investing in its people, its culture, and its future. That’s the kind of "empowered" investing we talk about at MAKE WEALTH REAL.

    A flourishing tree growing from urban brick foundations representing legacy wealth through Baltimore real estate.

    Final Thoughts

    The window for getting into Baltimore land banking at these price points won't stay open forever. As the $3 billion blight initiative continues to roll out through 2026 and 2027, those $5,000 lots are going to start looking like $50,000 lots very quickly.

    Are you going to be the person who says, "I wish I bought back then," or the person who is collecting the checks?

    If you’re ready to stop browsing and start building, let’s get to work. You can check out my current listings and see what we’re moving in the Maryland area over at my OneReal site. If you’ve got a deal you’re looking at and need that professional "Investor Ready" polish to secure funding, head over to my Wix site and let's get your package started.

    Your legacy starts with the land you stand on. Let’s make sure it’s solid.

    Connect with Me:


    Tweet Draft for Sonny:
    "Baltimore isn't just rowhomes; it's a gold mine for land banking. 🏗️ With $3B in city initiatives, the dirt you buy today is the legacy you leave tomorrow. Check out the latest blog on why land banking is the ultimate move in 2026! 🏠💰 #BaltimoreRealEstate #LandBanking #WealthBuilding #RealBrokerage"

  • The Secret Tax Strategy Maryland Business Owners Use to Keep More Profits

    The Secret Tax Strategy Maryland Business Owners Use to Keep More Profits

    If you’re running a business in Maryland, whether you’re based in the hustle of Baltimore, the tech corridors of Montgomery County, or the waterfront shops in Annapolis, you already know the deal. Our state is a land of opportunity, but it’s also a land of heavy taxation.

    Between state income taxes, local county taxes, and the federal government taking its "fair share," it can feel like you’re working half the year just to pay the IRS and the Comptroller of Maryland. But here’s the thing: the wealthiest business owners aren't necessarily making more money than you; they’re just keeping more of it.

    There is a specific set of strategies, one in particular that acts as a "secret weapon" for Maryland entrepreneurs, that can drastically reduce your tax liability and shift those dollars back into your business growth or your personal wealth.

    At MAKE WEALTH REAL, we’re all about empowering you to stop the "wealth leaks." Today, we’re pulling back the curtain on how Maryland business owners are winning the tax game.

    The "Secret Weapon": The Maryland PTE Tax Election

    If there is one thing you take away from this post, let it be this: The Pass-Through Entity (PTE) Tax Election.

    A few years ago, the federal government capped the amount of State and Local Taxes (SALT) you could deduct on your federal return at $10,000. For many Marylanders, between property taxes and state income taxes, $10,000 is a drop in the bucket. This left business owners paying federal taxes on money they had already paid to the state.

    Maryland stepped up and created a workaround that is perfectly legal and incredibly powerful.

    How It Works

    Normally, as an LLC or an S-Corp, your business profits "pass through" to your personal tax return. You pay the state tax there. However, with the PTE election, your business chooses to pay the state income tax at the entity level.

    Why does this matter? Because taxes paid by a business are a fully deductible business expense on your federal return. By paying the state tax through the business, you effectively bypass the $10,000 SALT cap.

    The Result: You lower your federal taxable income by the entire amount of state tax paid. You get a credit on your Maryland personal return for the taxes the business already paid. It’s a win-win that can save Maryland business owners thousands, if not tens of thousands, of dollars every single year.

    Confident Maryland business owner celebrating tax savings and increased profits in a Baltimore office.

    Beyond the Election: Maximizing the 20% QBI Deduction

    Many Maryland small business owners are still leaving the Qualified Business Income (QBI) deduction on the table. This was a gift from the 2017 Tax Cuts and Jobs Act, and it’s still going strong in 2026.

    If you are structured correctly, usually as a sole proprietorship, partnership, or S-Corp, you may be eligible to deduct up to 20% of your qualified business income from your taxes.

    Think about that for a second. If your business clears $100,000 in profit, you might only be taxed on $80,000. That’s a massive chunk of change that stays in your pocket just for having the right structure and the right documentation. This is why we tell our members at MAKE WEALTH REAL that your business structure isn't just a legal formality; it’s a financial strategy.

    The Section 179 "Fast Track" to Profits

    Are you planning on upgrading your tech, buying new equipment, or investing in furniture for your Maryland office this year? Don’t just depreciate those items over five or seven years. Use Section 179.

    Section 179 allows business owners to deduct the full purchase price of qualifying equipment or software purchased or financed during the tax year. Instead of taking a small deduction every year, you take the whole thing now. If you’re having a high-profit year and you know a big tax bill is coming, Section 179 is your best friend to bring that taxable income down immediately.

    Motivational Finance Prompt Graphic

    Are You Overpaying Your Bills?

    Tax strategy isn't just about what you give to the government; it's about the "silent taxes" you pay every day in the form of overpaid expenses. Most Maryland business owners are so busy running their operations that they don't have time to audit their internet, phone, trash pickup, or merchant processing fees.

    At MAKE WEALTH REAL, we focus on a "Financial Makeover" that looks at every angle. One of the biggest leaks we find is in these recurring bills. When you reduce your overhead, you increase your profit. And because that "found money" was already taxed, it goes straight to your bottom line as pure wealth.

    The MWR Advantage: Tax Experts in Your Pocket

    You might be thinking, "Lamont, this sounds great, but I’m a florist/contractor/consultant, not a CPA."

    We get it. You shouldn't have to be a tax expert to keep your money. That’s why the MWR Financial membership is a game-changer for Maryland business owners. We provide access to Enrolled Agents and tax professionals who do the heavy lifting for you.

    Instead of guessing if you qualify for the PTE election or the QBI deduction, you have experts who review your past three years of tax returns to find money you overpaid and set you up for success moving forward. Our TaxBot app even helps you track every single mile and every single receipt, ensuring that come tax season, you aren't scrambling through shoeboxes of paper.

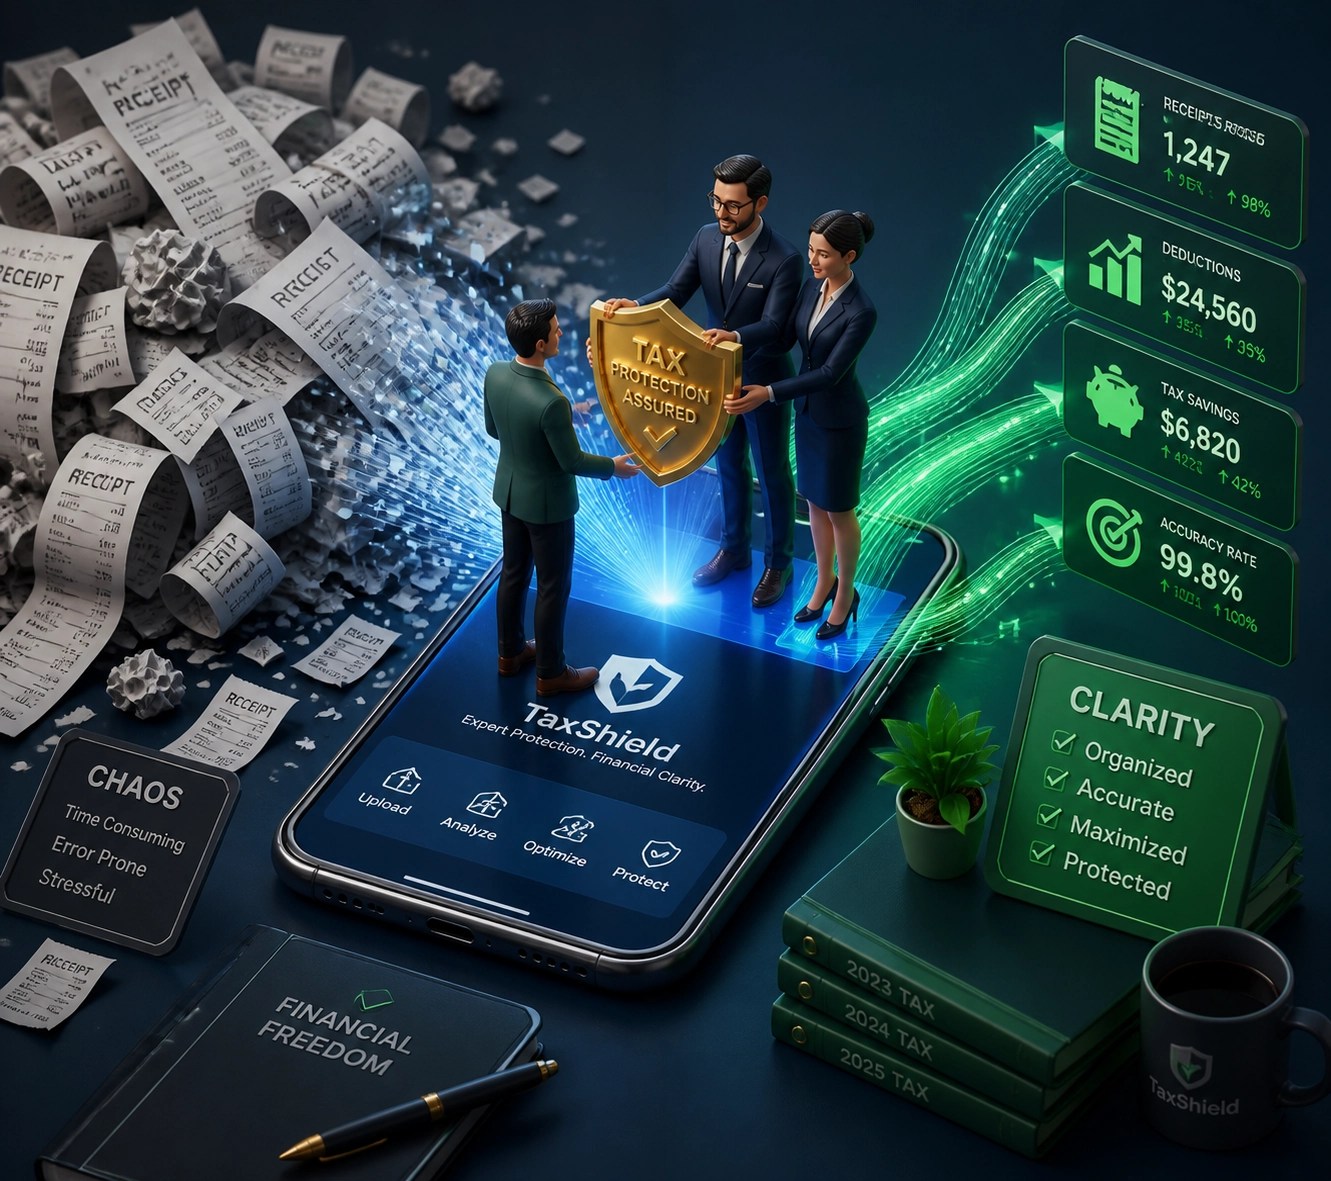
    Professional tax experts helping a business owner organize receipts and protect income with a mobile app.

    Shifting Income to Build Wealth

    The final "secret" isn't a tax loophole, it's a mindset shift. The goal isn't just to "pay less taxes." The goal is to shift that saved money into income-producing assets.

    When you use the strategies mentioned above to save $5,000 or $10,000 on your Maryland tax bill, that money shouldn't just sit in a checking account. It should be "shifted" into private banking strategies or used to eliminate business debt. This is how you go from being a business owner who is "getting by" to a business owner who is building a legacy.

    S.I.M.P.L.E Leverage Everything! Weekly Event Promotional Graphic

    Why Maryland Owners Need to Act Now

    The tax laws in 2026 are complex, and the Maryland Comptroller's office is more diligent than ever. If you aren't proactive, you are essentially leaving a tip for the government, and let's be honest, they've had enough.

    By implementing the PTE tax election, maximizing your QBI deductions, and utilizing Section 179, you aren't doing anything "shady." You are simply using the rules of the game to your advantage. These are the same rules the "big guys" use. It's time the small business owners in the Old Line State started playing by the same playbook.

    Ready to Stop the Leaks?

    If you're tired of seeing your hard-earned profits vanish every April, it’s time for a change. You don't need a more expensive accountant; you need a better system.

    The MAKE WEALTH REAL membership is designed to give you the experts, the tools, and the strategies to keep more of your paycheck, eliminate your debt, and grow your wealth. This is the Financial Transformation you’ve been looking for.

    Take control of your business profits today.

    Join the MWR Membership and Start Your Financial Makeover Here!

    For more information on our programs and how we help business owners like you, visit www.mwrfinancial.com.


    Tweet Draft for Sonny:
    "Maryland business owners: Are you still losing profits to the SALT cap? 🦀 It’s time to use the 'secret' PTE Tax Election and keep your hard-earned cash. Check out our latest blog on how to stop the wealth leaks! 💸 #MarylandBusiness #TaxStrategy #MWRFinancial #WealthBuilding"

    Note to Sonny: Please post this tweet on our social media channels to drive traffic to the new blog post!

  • Why 2026 is the Year for First-Time Buyers in Middle River, MD

    Why 2026 is the Year for First-Time Buyers in Middle River, MD

    Hey there! If you’ve been sitting on the sidelines for the last few years, watching interest rates dance around and home prices skyrocket like they were on a mission to Mars, I have some news that’s going to make your day.

    We are officially in 2026, and the landscape for first-time homebuyers has shifted in a major way, especially right here in Middle River, Maryland.

    For a long time, buying your first home felt less like a milestone and more like a high-stakes hunger game. You had to have your offer in within four hours of a house hitting the market, skip the inspection, and pray to the real estate gods that you weren't outbid by an all-cash corporate investor. Well, I’m happy to tell you those days are cooling off.

    Middle River is currently sitting in a "sweet spot" that makes it one of the best places in the entire Baltimore metro area to plant some roots. Let’s dive into why 2026 is finally the year you can stop paying your landlord’s mortgage and start paying your own.

    The "Baltimore Secret" is Out (But Middle River is Still Affordable)

    Did you know that the Baltimore metro area was recently ranked #9 on Zillow’s top 10 best markets for first-time homebuyers in 2026? It’s true. While people are fleeing high-priced cities like New York and DC, they are realizing that the Baltimore suburbs offer incredible value without sacrificing the perks of East Coast living.

    Middle River, in particular, is the crown jewel for anyone who wants that coastal Maryland lifestyle without the coastal price tag. With an average home value sitting around $335,491, it is significantly more accessible than nearby areas like Towson or White Marsh.

    But here’s the kicker: prices in Middle River have actually dipped about 2.4% compared to last year. While the rest of the country is fighting for scraps, our local market is offering a rare opportunity to buy in at a lower entry point.

    Modern single-family home in Middle River Maryland featuring a sold sign on the front lawn.

    Why 60 is Your New Favorite Number

    In 2024 and 2025, if a house stayed on the market for more than a week, people assumed the basement was haunted or the foundation was made of crackers. It was a "blink and you miss it" market.

    Fast forward to 2026, and the "Median Days to Pending" has shifted. Locally, we are seeing homes stay on the market for an average of 60 days. Compare that to the 34 days we saw just a year ago.

    Why does this matter to you?

    1. Leverage: When a house sits for 60 days, the seller starts to get a little nervous. They are much more likely to entertain offers that include closing cost assistance or repairs found during an inspection.
    2. Breathing Room: You actually have time to walk through the house, go home, sleep on it, and maybe even visit the neighborhood at night to see if the neighbors' dog is a barker. You aren't being pressured to make the biggest financial decision of your life in the time it takes to order a pizza.
    3. Negotiation Power: With homes receiving an average of only three offers: down from the double-digit bidding wars of the past: you aren't just a number in a stack. You have a voice.

    The Lifestyle: Waterfront Vibes and City Access

    If you’re moving to Middle River, you’re not just buying four walls and a roof; you’re buying a lifestyle. We have some of the coolest waterfront access in Baltimore County. Whether you’re grabbing a drink at Carson’s Creek or taking the kids to Rocky Point Park and Beach, the "river life" is real here.

    For first-time buyers, this is huge. Usually, to get near the water, you have to spend half a million dollars. In Middle River, you can find a solid starter home or a renovated townhome for well under $350,000 and still be five minutes away from the marina. Plus, you’re just a quick hop onto I-695 or Route 40, making the commute into Baltimore or up to Aberdeen Proved Ground a breeze.

    The 2026 Financial Edge

    I know, I know: "Lamont, what about the money?"

    Beyond the home prices, 2026 has brought some unique financial advantages. First off, tax law changes have increased bracket thresholds by about 2.7%. While that might sound like "math talk," what it really means is that more of your hard-earned paycheck is staying in your pocket, making it easier to save for that down payment.

    Additionally, interest rates have finally begun to stabilize. We aren't seeing those wild weekly swings anymore, which allows you to lock in a rate with confidence. When you combine stabilizing rates with a 3.4% decrease in the price per square foot locally, your monthly mortgage payment starts looking a lot more attractive than that ever-increasing rent check.

    Pique Meme

    Don't Let "Analysis Paralysis" Stop You

    I see it all the time. People wait for the "perfect" moment. They want prices to hit rock bottom and rates to be 0% (which isn't happening, folks).

    The "perfect" moment is when the market gives you an opening, and right now, Middle River is holding the door open for you. With 80 homes currently for sale and new listings hitting the market every week, the selection is healthy. You aren't being forced to buy a "fixer-upper" that’s actually a "tear-it-downer." You can find move-in-ready homes that fit your style.

    How to Get Started (The Right Way)

    Buying your first home is a big deal, but it doesn't have to be a stressful one. My goal is to make sure you walk into your new home with equity and peace of mind.

    If you’re ready to see what’s out there, I’ve got you covered. You can browse all the latest Middle River listings: and the surrounding areas: on my OneReal site. I keep it updated in real-time so you aren't looking at "zombie listings" that sold three weeks ago.

    Check out the latest listings here: https://onereal.com/lamont-milbourne

    And if you’re feeling overwhelmed or just want to chat about your specific situation: like how much you really need for a down payment or how to get pre-approved: let’s talk. No pressure, no sales pitch, just a real conversation about your goals.

    Schedule a quick consultation on my Calendly: https://calendly.com/

    Silver house keys and a digital tablet representing a first-time homebuyer's journey in Maryland.

    Final Thoughts

    Middle River is changing. The secret is out that it's a fantastic place for families, young professionals, and anyone who loves the Maryland coast. By acting in 2026, you’re getting ahead of the curve before the next big surge.

    Whether you're looking for a cozy spot near Martin State Airport or something closer to the water, the inventory is there, the sellers are ready to talk, and the timing is finally on your side.

    Don't spend another year wondering "what if." Let’s get you into a home you actually love.

    For more resources on local properties and my property management services, visit my site here: https://lmilbourne9.wixsite.com/millisproperty


    Tweet Draft for Sonny:
    "Middle River, MD is officially a top-tier spot for first-time buyers in 2026! 🏠 With prices stabilizing and homes staying on the market longer, the leverage has shifted back to YOU. Check out my latest blog post for the full breakdown and see why now is the time to buy. #MiddleRiverRealEstate #MarylandHomes #FirstTimeHomeBuyer #RealEstate2026"

  • Baltimore’s Best Kept Secret: Debt Elimination and Generational Wealth in 2026

    Baltimore’s Best Kept Secret: Debt Elimination and Generational Wealth in 2026

    Let’s be real for a second, Baltimore is known for a lot of things. We’ve got the best crabs in the world (don’t even bring up Louisiana), the Orioles are holding it down at Camden Yards, and our "grit" is basically a local currency. But there’s a side of Charm City that isn't so charming: the weight of the 2026 economy.

    If you’ve taken a stroll through Fells Point lately or grabbed a coffee in Mt. Vernon, you’ve probably noticed the vibe. The city is growing, but for a lot of us, our bank accounts are feeling like they’re stuck in a perpetual traffic jam on I-95 during rush hour. Prices are up, interest rates are doing backflips, and that "generational wealth" everyone talks about on Instagram feels more like a fairy tale than a financial plan.

    But here’s the thing: there’s a secret circulating through the streets of Baltimore. It’s not a get-rich-quick scheme, and it’s definitely not another "side hustle" that leaves you exhausted and broke. It’s a blueprint for taking back your power. Today, we’re talking about the one-two punch that’s changing lives from West Baltimore to Canton: Debt Elimination and Generational Wealth.

    The Baltimore Struggle: Why "Just Working Harder" Isn't Cutting It

    In 2026, the old advice of "just work hard and save your pennies" is officially dead. Between inflation and the rising cost of living in Maryland, those pennies are basically disappearing before they even hit the jar. We’re living in a city where the municipal government is projecting multi-million dollar deficits, and property taxes are a constant conversation at the dinner table.

    If the city is struggling to balance the books, how are you supposed to do it?

    Most people are trapped in a cycle of "structured poverty." You make money, the government takes their cut (and then some), the banks take interest, and you’re left with the crumbs. We’ve been taught to manage debt, not eliminate it. We’ve been told that a 30-year mortgage is a "blessing" and that carrying a credit card balance is just "part of life."

    Spoiler alert: The banks are getting rich off your "part of life." It’s time to stop being the victim of the system and start being the architect of your own empire.

    ![Empowered person in Baltimore breaking symbolic debt chains at sunset for financial freedom.](A vibrant, high-energy illustration of the Baltimore skyline at sunset, with symbolic golden chains breaking apart in the foreground to represent debt elimination and financial freedom.)

    Step 1: The Great Debt Escape (The MWR Way)

    You can’t build a skyscraper on a swamp. In the same way, you can’t build generational wealth while you’re sinking in high-interest debt.

    At MAKE WEALTH REAL, we don’t believe in "debt management." We believe in Debt Shredding. Think of it as the ultimate Baltimore cleanup. Instead of just paying the minimums and hoping for the best, our strategy uses sophisticated financial algorithms to show you exactly how to pay off every single debt you owe, mortgage, student loans, credit cards, in record time, without you having to spend a penny more than you’re already spending.

    Imagine living in Baltimore and actually owning your home. Not the bank owning it while you pay them for 30 years, but you owning it. Imagine the freedom of looking at your bank statement and seeing $0 owed to anyone. That’s not a dream; it’s a strategy.

    And let’s talk taxes for a second. Most people in Maryland are overpaying their taxes because they don’t have the right "playbook." Through our MWR membership, you get access to experts who help you shift your income. By utilizing over 470 tax deductions available to home-based business owners, you can instantly increase your take-home pay. It’s like giving yourself a raise without asking your boss for permission.

    MWR @Home Opportunity Promotion

    Step 2: From Surviving to Thriving (Building the Empire)

    Once the debt is under control and your cash flow is fixed, that’s when the real fun starts. This is where we move from "keeping the lights on" to building Generational Wealth.

    Generational wealth means your kids’ kids will know your name because of the foundations you laid in 2026. It’s about moving your money out of depreciating assets and into things that multiply.

    In Baltimore, we’ve seen neighborhoods change and evolve. But who usually benefits from that change? Not the people who were there from the start. Why? Because they didn't have the capital or the financial literacy to play the game. We’re changing that.

    Our mission at MAKE WEALTH REAL is to provide the "Big Business" secrets to the "Little Guy." We provide access to:

    • Credit Restoration: Because a high credit score is a tool for wealth, not just a way to get more debt.
    • Private Reserve Accounts: Learn how to become your own bank.
    • Land Banking: Owning a piece of the future.

    We’re not just talking about having a nice savings account. We’re talking about creating a financial fortress that protects your family for decades.

    S.I.M.P.L.E Leverage Everything! Weekly Event Promotional Graphic

    Why Baltimore, Why Now?

    There is a window of opportunity right now in 2026. As the world becomes more digital and traditional jobs become more uncertain, the ability to control your own financial destiny is the ultimate "flex."

    Baltimore has always been a city of innovators and survivors. We know how to hustle. But it’s time to stop hustling harder and start hustling smarter. Why keep 30% of your paycheck when you could keep 70%? Why pay the bank 100% interest over the life of a loan when you could pay 0%?

    The "secret" isn't a secret anymore. It’s a membership. It’s a community of people in Maryland who have decided that "good enough" isn't good enough anymore.

    Motivational Finance Prompt Graphic

    Your Financial Makeover Starts at the Inner Harbor (Or Your Living Room)

    You don't need a PhD in finance to win. You just need the right experts in your corner. When you join the MWR Financial family, you’re not just getting a login to a website; you’re getting a team of Enrolled Agents, CPA’s, and financial strategists who do the heavy lifting for you.

    They look at your taxes. They look at your debt. They look at your credit. And then they give you a step-by-step plan to win. It’s like having a championship coaching staff for your wallet.

    Whether you’re in West Baltimore, the County, or anywhere in between, the time to move is now. Don't let 2026 be another year where you "almost" got ahead. Make this the year you made wealth real.

    Ready to Shred the Debt and Build the Legacy?

    If you’re tired of the "Baltimore Struggle" and ready for the "Baltimore Success Story," let’s talk. I’m helping folks all across Maryland implement these exact strategies to reclaim their time and their money.

    Step 1: Join the movement and start your Financial Transformation today.
    👉 Join MWR Financial Here

    Step 2: Let’s get personal. Schedule a strategy call with me to see how these pillars of wealth can be applied to your specific situation. No fluff, just facts.
    👉 Book Your Call on Calendly

    Stop leaving your legacy to chance. Let’s build something that lasts.


    Hey Sonny! Here is the draft for the tweet. Let’s get this out to the Baltimore crowd:

    "Baltimore isn't just about grit; it's about GROWTH. 🦀 In 2026, debt shouldn't be your shadow. Discover the 'Secret' to debt elimination and building a legacy that lasts for generations. Check out our latest blog! #BaltimoreWealth #MWR #FinancialFreedom #CharmCityHustle"


    For more information on our programs and how we are changing the financial landscape, visit the authoritative source at www.mwrfinancial.com.

  • Top 5 Reasons Your Dundalk Home Isn’t Selling: And How to Fix It Fast

    Top 5 Reasons Your Dundalk Home Isn’t Selling: And How to Fix It Fast

    So, you’ve put your home on the market in Dundalk. You’ve got the “For Sale” sign in the yard, you’ve cleared off the kitchen counters, and you’ve been checking your phone every five minutes for a showing request. But here’s the problem: the phone isn't ringing. Or maybe it is, but the offers are coming in low: or not at all.

    Dundalk is a unique market. From the classic brick rowhomes in the heart of the village to the hidden gems near Bear Creek and the waterfront views near Turner Station, this area has a lot to offer. But in 2026, the real estate landscape has shifted. Buyers are more selective, interest rates are playing a different game, and if your house is sitting on the market for more than 30 days, people start to wonder what’s wrong with it.

    Don't panic. If your home isn't moving, it usually boils down to one of five specific issues. Let’s break down why your Dundalk property might be stuck and: more importantly: exactly how we can fix it fast.

    1. Your Price is Stuck in 2024 (The Reality Check)

    Look, I know you love your home. You’ve put years of memories into it, maybe you just redid the bathroom, and you’ve got the best view of the Heritage Fair fireworks from your backyard. But the market doesn't care about sentiment. It only cares about "Comps": Comparable Sales.

    In 2026, the Dundalk market is seeing a more balanced dynamic. We aren't in the wild bidding-war territory of a few years ago. If you priced your home based on what your neighbor got at the peak of the market, you might be overshooting.

    The Fix:
    You need a fresh Comparative Market Analysis (CMA). We need to look at what has actually closed in the last 90 days within a one-mile radius of your street. If you're priced $20k higher than a similar home three blocks away, buyers won't even step through the door.

    Real estate market data and price comparison for Dundalk Maryland homes for sale.

    Strategic pricing is an art. Sometimes, pricing just under market value creates the buzz you need to get multiple offers that drive the price back up. If you're wondering where your house stands, check out my Dundalk Property Evaluation page to see how we analyze current values.

    2. Your Online "First Impression" is Flop

    In 2026, the "first showing" doesn't happen at your front door. It happens on a smartphone screen while someone is scrolling through Zillow or OneReal at 11:00 PM. If your listing photos look like they were taken with an old flip phone in a dark room, buyers are going to swipe left faster than a bad date.

    I see it all the time in Dundalk: great houses with photos that show piles of laundry, dark hallways, or: the classic: the photographer's reflection in the bathroom mirror.

    The Fix:
    Professional photography is non-negotiable. Period. We’re talking high-dynamic-range (HDR) images, wide-angle lenses that make rooms look spacious without looking distorted, and proper lighting.

    But let’s take it a step further. To stand out in the Maryland market today, you need:

    • Drone Footage: Especially if you’re near the water or have a decent-sized lot.
    • Virtual Tours: Let buyers "walk" through the house from their couch.
    • Floor Plans: Buyers in 2026 want to see the layout before they commit to a drive.

    If your current agent didn't provide these, that’s a red flag. You can see how I showcase listings over at my OneReal portal. We make sure every house looks like a cover model.

    3. The "Curb Appeal" Isn't Appealing

    Dundalk is famous for its porches and its tight-knit streetscapes. When a buyer pulls up to your curb, they make a decision within seven seconds. If the grass is overgrown, the porch railings are peeling, or the front door looks weathered, they’re already looking for flaws before they even turn the key.

    The Fix:
    You don't need a $10,000 landscaping budget. You need a "Saturday Morning Refresh."

    • Power Wash Everything: The siding, the sidewalk, and the porch.
    • Fresh Mulch: It’s the cheapest way to make a yard look "done."
    • The Front Door: Paint it a bold, inviting color and replace old house numbers.
    • Lighting: Make sure your exterior lights are clean and bright for those evening drive-bys.

    Remember, you aren't just selling a house; you're selling a "homecoming." If it looks neglected on the outside, buyers assume it’s neglected on the inside.

    4. You’re Selling a "Life," Not a House (The Staging Problem)

    I know you love your collection of vintage Baltimore sports memorabilia or your family photo wall that spans three decades. But when a buyer walks into your Dundalk home, they need to see their life there, not yours.

    If your rooms are crowded with furniture or the walls are painted "Ravens Purple" (as much as we love the team), it’s hard for a buyer to visualize their own furniture in the space.

    The Fix:
    Neutralize and Declutter.

    1. The 50% Rule: Take half of the stuff out of your closets and kitchen cabinets. It makes the storage space look huge.
    2. Paint it "Greige": Neutral tones reflect light and make rooms feel bigger and cleaner.
    3. Depersonalize: Pack away the family photos and the eccentric decor.

    If you're an investor looking to flip a property in Dundalk, staging is even more critical. You want that "model home" feel. Speaking of investors, if you’re trying to get a deal ready for sale and need to ensure your rehab budget and ARV (After Repair Value) are on point, I offer a Paid Funding Preparation Service. I’ll handle the deal analysis, provide the ARV comps, and build a loan submission package through our Real Brokerage lending partners to make sure your project is "Investor Ready."

    Pique Meme.webp

    5. Your Marketing is Too Local (Or Not Local Enough)

    Is your home just sitting on the MLS waiting for a miracle? In 2026, that’s a recipe for a "stale" listing. Dundalk attracts a wide range of buyers: young professionals moving out of the city, families looking for more space, and investors looking for solid rental yields.

    If your marketing isn't specifically targeting these groups where they hang out (Instagram, Facebook, YouTube, and localized Google searches), you’re missing out on 80% of your potential pool.

    The Fix:
    We use hyper-targeted social media ads. We don't just "post" your house; we advertise it to people who have recently searched for "homes for sale in 21222" or "waterfront property in Maryland."

    We also leverage the power of The Real Brokerage. My network isn't just local; it’s national. We get your property in front of agents across the country who have clients relocating to the Baltimore area for jobs at the Port or the local medical centers.

    The Bonus Reason: Showing Friction

    Is it hard to see your house? If you require 24-hour notice and only allow showings between 2 PM and 4 PM on Tuesdays, you aren't going to sell. Buyers are busy. If they can't see your house when they're available, they’ll just go see the one next door that has a lockbox.

    The Fix:
    Be as flexible as possible for the first two weeks. I know it’s a pain to keep the house "show-ready" all the time, but the faster we get people through the door, the faster you can move on to your next chapter.


    Ready to Get That "SOLD" Sign?

    Selling a home in Dundalk doesn't have to be a headache. It just takes a strategic approach, a little bit of elbow grease, and the right partner to navigate the 2026 market.

    If you’re tired of waiting and ready to see some action, let’s talk. Whether you’re a homeowner looking to upgrade or an investor needing a professional package to move your inventory, I’ve got the tools to make it happen.

    Step 1: Check out my Real Estate Portfolio and Selling Options here.
    Step 2: List with me through OneReal and let’s get your property the exposure it deserves.

    Let’s get your Dundalk home off the market and put the check in your hand.


    Tweet Draft for Sonny:
    "Is your Dundalk home sitting on the market? 🏠 From pricing blunders to bad lighting, we're breaking down the top 5 reasons homes aren't selling in 2026 and how to fix them FAST. Check out the latest blog for the blueprint! #DundalkRE #MarylandRealEstate #SellingTips"

  • How Maryland Entrepreneurs Can Secure $50k in Funding Without Personal Credit

    How Maryland Entrepreneurs Can Secure $50k in Funding Without Personal Credit

    Listen, if you’re running a business in Maryland, whether you’re grinding in Baltimore, setting up shop in Silver Spring, or scaling a tech startup in Columbia, you know that cash flow is the lifeblood of your dream. But there’s a massive roadblock that stops most entrepreneurs dead in their tracks: the "Personal Credit Trap."

    Most people think that to get $50,000 for their business, they need a pristine 800 credit score and a stack of personal assets to put on the line. They think the bank wants to see their personal car, their home, and their kid’s college fund before they’ll even look at a business loan application.

    I’m here to tell you that’s old-school thinking. In 2026, the game has changed. You can secure $50,000 in unsecured business funding without tying it to your personal credit score. At MAKE WEALTH REAL, we call this financial sovereignty. It’s about building a business that stands on its own two feet.

    The Myth of the Personal Guarantee

    Let’s get real for a second. When you started your business, you probably did it for freedom. But if every dollar you borrow for your company is tied to your Social Security number, you aren't actually free. You’re just an employee of your own debt.

    Most Maryland entrepreneurs are stuck in a cycle where they use personal credit cards to buy inventory or pay for marketing. This tanks their personal credit utilization, drops their score, and makes it impossible to get a mortgage or a personal loan later.

    The alternative? Unsecured Business Funding. This is money granted to your business entity (your LLC or Corporation) based on the business’s own merit, credit history, and revenue, not your personal FICO score.

    Motivational Finance Prompt Graphic

    What Exactly is "Unsecured" Funding?

    "Unsecured" is a beautiful word for an entrepreneur. It means the lender isn't asking for collateral. They aren't asking for the keys to your house if things go south. Instead, they are looking at the strength of your business profile.

    For a Maryland business owner, securing $50k in unsecured funding means you have the capital to:

    • Hire that executive assistant you’ve been needing.
    • Launch a massive digital ad campaign across the DMV area.
    • Upgrade your equipment without draining your savings.
    • Bridge the gap during slow seasons.

    The best part? Because it’s unsecured and tied to your EIN (Employer Identification Number), it doesn't show up on your personal credit report. You keep your personal life and your business life completely separate, just like the big corporations do.

    The Blueprint: How to Get to $50k Without the Stress

    You might be wondering, "If they aren't looking at my personal credit, what ARE they looking at?" Great question. Lenders look at your Business Credibility. If you want the bag, you have to look the part.

    1. Setup for Success

    Before you ask for a dime, your business needs to look "fundable." This means having a professional business address (not your home address), a business phone number listed in the 411 directory, and a professional email and website. Lenders in Maryland are tech-savvy; if they Google your business and see a Gmail address and a residential photo, they’re going to pass.

    2. The Power of the EIN

    Your EIN is like a Social Security number for your business. You need to start treating it that way. You build business credit by opening "Trade Lines" with vendors who report to business credit bureaus like Dun & Bradstreet, Experian Business, and Equifax Business.

    3. Tiered Credit Building

    You don't just walk into a bank and ask for $50k on day one. You build tiers.

    • Tier 1: Net-30 accounts with vendors like Uline or Grainger. You buy what you need, pay it off in 30 days, and they report your on-time payment.
    • Tier 2: Store credit cards (think Best Buy or Amazon Business) that are linked only to your EIN.
    • Tier 3: High-limit, unsecured business credit cards and lines of credit.

    This is where the $50k lives. Once you’ve proven your business can handle small amounts, the floodgates open.

    Maryland entrepreneur in a Baltimore office viewing a growth chart for $50k unsecured business funding success.

    Why Maryland Entrepreneurs Have an Edge

    Maryland is a unique beast. We have a high concentration of government contractors, service-based businesses, and a booming retail sector. Because of our proximity to D.C., there is a lot of capital moving through the state.

    However, local banks can be traditional. That’s why we focus on the MWR Financial Makeover approach. We don't just tell you to go to a bank; we help you build the financial foundation so that lenders are competing for your business.

    Imagine walking into a meeting knowing your business credit is solid, your cash flow is optimized, and you don't have to break a sweat about your personal credit score. That’s the "Empowered Entrepreneur" vibe we’re building here at MAKE WEALTH REAL.

    How MAKE WEALTH REAL Levels the Playing Field

    At MWR, we specialize in the "Financial Makeover." We realize that as a business owner, you’re busy running the show. You don't have time to spend 40 hours a week deciphering credit bureau algorithms.

    Our experts help you:

    1. Clean up the personal side: If your personal credit is holding you back, we help restore it so you have a safety net.
    2. Build the business side: we provide the roadmap to getting your business credit accounts established and reporting correctly.
    3. Access Funding: We connect you with the right paths to secure that $50k (and more) without the personal liability.

    S.I.M.P.L.E Leverage Everything! Weekly Event Promotional Graphic

    Stop Playing Small

    The biggest mistake Maryland entrepreneurs make is "playing small" because they’re afraid of debt. But there is a difference between bad debt (buying things that lose value) and leverage (using capital to grow your income).

    Securing $50,000 in unsecured funding is about leverage. It’s about having the "dry powder" ready to strike when an opportunity hits the Maryland market. Whether it's a new contract in Annapolis or a storefront opening in Bethesda, you need to be ready.

    Don't let a "fair" or "poor" personal credit score stop you from building a legacy. The systems are already in place for you to win; you just need the keys to the kingdom.

    Ready to Secure Your $50k?

    You’ve spent enough time wondering "what if." It’s time to take action. Whether you’re just starting out or you’ve been in business for years and are ready to scale, the path to unsecured funding is open to you.

    Your Next Steps:

    1. Get Educated: Join the MWR membership to start your full Financial Transformation. We provide the tools, the experts, and the strategy to make wealth real for you and your family.

    2. Get Personalized Advice: Every business is different. Let’s look at your specific situation and map out a plan to get you funded.

      • Book a 1-on-1 Consultation: [Insert Calendly Link Here]

    Maryland is full of opportunity, but only for those who have the capital to seize it. Let’s get your business fundable, get your credit right, and get you the $50k you need to dominate your industry.

    See you at the top!


    Tweet Draft for Sonny:
    Hey Maryland Entrepreneurs! 🦀 Stop risking your personal credit for business growth. You can secure $50k in UNSECURED funding using just your EIN. No personal guarantee, no stress. Check out the blueprint on the blog: [Link] #MarylandBusiness #EntrepreneurLife #MWRFinancial #BusinessCredit

  • The Beginner’s Guide to Real Estate Flipping in 2026

    The Beginner’s Guide to Real Estate Flipping in 2026

    So, you’ve been watching the 2026 housing market from the sidelines, and you’re finally ready to jump into the house-flipping game. First off, welcome to the hustle! Flipping houses isn't just about demo days and picking out trendy subway tiles (though that part is pretty fun). In 2026, it’s a high-stakes chess match where the players who have the best data and the strongest funding usually win.

    If you’re looking to turn a distressed property into a $60,000 profit: the current median gross profit for a successful flip: you need more than a hammer and a dream. You need a strategy that works in today’s specific economic climate.

    Let’s break down the essential guide for flipping houses in 2026.

    1. The 2026 Reality Check: It’s a Business, Not a Hobby

    Gone are the days when you could buy any "ugly" house and expect it to sell for a premium just because you painted the walls gray. In 2026, buyers are savvy. They want energy efficiency, smart home integration, and functional layouts.

    Flipping is a high-risk, high-reward strategy. While rental properties provide long-term wealth, flipping is about active income. It requires capital, construction knowledge, and, most importantly, timing. Most flips take anywhere from 8 to 12 months from purchase to closing. If you aren't prepared to hold a property for a year, you aren't ready to flip.

    House flipping renovation showing a modern living room transformation with hardwood floors and smart home features.

    2. Get Your Funding Ready (Before You Find the House)

    One of the biggest mistakes beginners make is finding a "deal" and then scrambling for the money. In a market where off-market deals are snatched up in hours, you need to be "Investor Ready."

    You’ll typically need:

    • A Down Payment: Usually 20-30% for fix-and-flip loans.
    • Closing Costs: Budget 3-5% of the purchase price.
    • Renovation Capital: You need the cash to pay contractors before the loan draws kick in.
    • Holding Costs: Expect to pay $1,500–$3,000 per month for taxes, insurance, and interest.

    Pro-Tip: This is where most beginners fail. To help you bridge the gap, I offer a Paid Funding Preparation Service. We don’t just tell you to "go get a loan." We provide a full loan submission package through our Real Brokerage lending partners, including deep-dive deal analysis, ARV (After Renovation Value) comps, and detailed rehab budgets. Don't go to a lender with a "maybe": go with a professional package that demands a "yes."

    3. Finding the "Gold Mine" Neighborhood

    In 2026, the best flips aren't necessarily in the most expensive zip codes. They are in the "transition" zones. Look for these signs:

    • New Infrastructure: Are there new bike paths, transit lines, or tech hubs moving in?
    • The "Starbucks Effect": Large commercial retailers moving in is a signal of local economic confidence.
    • Low Days on Market: If houses in a neighborhood sell in under 20 days, demand is high.
    • Renovation Clusters: If you see three other dumpsters on the block, you’re in the right place.

    Use tools like Zillow, Redfin, and neighborhood analytics to track appreciation trends. You’re looking for 3-5% annual growth to ensure your exit price holds up.

    Aerial view of a profitable house flipping neighborhood showing urban growth and renovated properties.

    4. Master the 70% Rule (The 2026 Version)

    The "70% Rule" is the holy grail of flipping. It states that you should never pay more than 70% of the After Renovation Value (ARV) minus the costs of repairs.

    The Formula:
    (ARV x 0.70) – Estimated Repair Costs = Your Maximum Allowable Offer (MAO)

    For example, if a house will be worth $500,000 after it's fixed up, and it needs $50,000 in work:

    • $500,000 x 0.70 = $350,000
    • $350,000 – $50,000 = $300,000 Max Purchase Price

    In 2026, some investors are tightening this to 65% because of fluctuating material costs. Accuracy in your rehab budget is everything. If you underestimate the cost of a roof or HVAC system, your profit disappears.

    5. Build Your "Triple Threat" Team

    You cannot flip a house alone. You need a team that moves as fast as the market.

    • The Contractor: Someone who shows up, provides line-item bids, and understands permits.
    • The Agent: You need a realtor who understands investor needs, not just someone who likes pretty kitchens.
    • The Lender: Whether it's a hard money lender or a private partner, they need to be ready to fund in days, not weeks.

    Pique Meme3.png

    6. The Exit Strategy: Selling for Top Dollar

    The flip isn't over until the wire hits your bank account. In 2026, "good enough" won't get you the appraisal you need.

    • Professional Staging: This is non-negotiable. Empty houses look smaller and colder.
    • High-End Media: Use 4K drone footage and 3D virtual tours.
    • Energy Efficiency: Mentioning "New HVAC" and "Smart Insulation" in your listing descriptions adds massive value for 2026 buyers.

    7. Common Pitfalls to Avoid

    • Over-Improving: Don't put $100,000 into a house in a neighborhood where the ceiling price is only $300,000.
    • Skipping Inspections: Even if you’re buying "as-is," get an inspection for your own knowledge. Foundation issues are profit killers.
    • Doing it Yourself: Unless you are a licensed plumber or electrician, put down the tools. Your time is better spent finding the next deal.

    Professional home inspection using thermal imaging to detect hidden issues during a house flip.

    Ready to Level Up Your Real Estate Game?

    Whether you are looking to sell your current property for top dollar, buy your first investment, or scale your flipping business, we have the tools to make it happen.

    The "Triple Threat" Opportunity:

    • SELLERS: Get a data-backed valuation and a marketing strategy that beats the 2026 averages. List with us here.
    • BUYERS: Access off-market inventory and get represented by experts who know how to win in multiple-offer scenarios.
    • INVESTORS: Stop guessing. Use our Paid Funding Prep Service for deal analysis, ARV comps, and rehab budgeting to ensure your next flip is a winner. Check out our property services.

    Join the Movement:
    Don't do this alone. Join our Skool Community today to connect with other investors, share deal flow, and get the latest 2026 market updates. Let’s build that legacy together.


    Tweet Draft for Sonny:
    "The 2026 flipping market is a different beast! 🏠💰 Just dropped 'The Beginner's Guide to Real Estate Flipping' on the blog. We’re talking the 70% rule, funding prep, and how to snag that $60k median profit. Check it out & let's get to work! #RealEstateInvesting #HouseFlipping #2026Market"