Category: Uncategorized

  • Selling vs. Renting: Maximizing Your Property Value in 2026

    Selling vs. Renting: Maximizing Your Property Value in 2026

    So, here we are in April 2026, and the real estate market is doing that thing it does: making everyone second-guess their next move. If you own a property right now, you’re likely sitting on a decent chunk of equity, but you’re also seeing the headlines about the "Great Affordability Correction."

    The big question on every homeowner's and investor’s mind is: Should I sell now and cash out, or should I hold on and rent it out?

    There isn't a one-size-fits-all answer, but there is a strategic way to look at the numbers so you don't leave money on the table. Whether you’re a long-term investor or a homeowner looking to level up, let’s break down the pros, the cons, and the "secret sauce" for maximizing your property value this year.

    The State of the Market in 2026

    Before we dive into the "sell vs. rent" debate, we have to look at the environment we’re playing in. We’re currently seeing home price growth stabilize at around 1%. While that sounds slow compared to the wild hikes of the early 2020s, it’s actually a sign of a maturing market. Household incomes are finally starting to catch up to housing costs, creating a more balanced playing field.

    For sellers, this means you aren’t necessarily in a "rush" to beat a crash, but you also shouldn't expect your home value to double overnight. For investors, the rental market is tighter than ever. A lot of "accidental landlords" have exited the game, leaving a supply gap that is pushing rents higher across the board.
    Modern suburban neighborhood at golden hour showcasing stable property values in the 2026 real estate market.


    Case #1: The Argument for Selling (Locking in the Win)

    Selling in 2026 is all about liquidity and leverage. If you’ve got a specific goal: like buying a larger primary residence, diversifying into commercial real estate, or just clearing out debt: selling is your fastest path to a massive cash injection.

    The Pros of Selling Now:

    1. Immediate Liquidity: You turn that "paper wealth" (equity) into cold, hard cash. In a market where price appreciation is modest, having that cash ready to deploy into a higher-yielding asset can be a massive win.
    2. Avoiding the "Landlord Headache": Let’s be real: being a landlord isn't for everyone. If you don't want to deal with midnight plumbing emergencies or chasing down rent, selling lets you walk away clean.
    3. The Affordability Window: With the "Great Affordability Correction" in full swing, there are more buyers entering the market who were previously priced out. This keeps demand steady for well-maintained starter and mid-tier homes.

    The Cons of Selling Now:

    1. Transaction Costs: Between agent commissions, closing costs, staging, and repairs, you can easily lose 8-10% of your sale price before you even see a dime.
    2. Tax Man Cometh: Unless you’re doing a 1031 exchange (for investors) or you fall under the primary residence capital gains exclusion, Uncle Sam is going to want his cut.
    3. Missing Future Gains: If your property is in a high-growth corridor, selling now means you miss out on the compounding appreciation over the next decade.

    Case #2: The Argument for Renting (Building the Legacy)

    If you don't need the cash right this second, renting the property is often the superior move for long-term wealth building. In 2026, the "renter nation" trend hasn't slowed down. People need places to live, and high-quality rentals are at a premium.

    The Pros of Renting in 2026:

    1. Passive Income (Cash Flow): If your mortgage is locked in at a lower rate than current market rents, you’re looking at monthly "mailbox money."
    2. Tax Benefits: This is the big one. You get to deduct mortgage interest, property taxes, repairs, and: the holy grail: depreciation. Depreciation allows you to write off a portion of the building's value against your income, even if the property is actually going up in value.
    3. Loan Paydown: Your tenants are essentially buying the house for you. Every month they pay rent, your equity grows without you moving a finger.

    The Cons of Renting:

    1. Concentrated Risk: All your eggs are in one basket. If the neighborhood goes downhill or a major employer leaves town, your asset takes a hit.
    2. Maintenance CapEx: Roofs leak. HVACs die. You need a financial buffer to handle the "unexpecteds."
    3. Management Stress: Even with a property manager, you still have to manage the manager.
    A house key and wallet on a desk representing the choice between property rental and immediate liquidity.


    How to Make the Decision: The "Math" Test

    To decide which path is right for you, you need to look at your Return on Equity (ROE).

    If you have $200,000 in equity and the property only nets you $200 a month in cash flow after all expenses, that’s a terrible return on your money. You’d be better off selling, taking that $200k, and putting it into a more productive asset.

    However, if that same property is in an area where rents are jumping 5% year-over-year and the neighborhood is getting a new tech hub, holding is the move.

    The Investor-Ready Edge

    If you decide to hold and maybe even expand your portfolio, you can’t just "wing it" anymore. The 2026 market demands precision. This is where I come in to help you get Investor Ready.

    One of the biggest hurdles for investors right now isn't finding the property: it's the funding and analysis. I offer a dedicated funding preparation service designed to take the guesswork out of the process. When you work with me, we don't just look at a house; we build a submission package that lenders can't ignore.

    My Funding Prep Service includes:

    • Deep-Dive Deal Analysis: Is it actually a good deal? We look at the real numbers, not the "hopeful" ones.
    • ARV Comps: After-Repair Value is everything. We use real-time 2026 data to see what the property will be worth once it's polished.
    • Rehab Budgets: No more guessing on contractor costs. We build a realistic budget so you don't run out of cash mid-project.
    • Loan Submission Packages: Through our Real Brokerage lending partners, we package your deal so it’s "turnkey" for underwriters.

    S.I.M.P.L.E Leverage Everything! Weekly Event Promotional Graphic


    Maximizing Value: The Hybrid Strategy

    Sometimes the answer isn't "sell" or "rent": it's "fix and then decide."

    If your property is outdated, you’re losing money on both sides of the coin. An outdated house sells for less and rents for less. In 2026, small, high-impact renovations (think smart home tech, energy-efficient windows, and modern flooring) are yielding the highest ROI.

    If you’re looking to sell, these upgrades help you hit the top of the "Affordability Correction" bracket. If you’re looking to rent, they attract high-quality tenants who stay longer and take better care of the place.


    The Verdict

    In 2026, the "win" goes to the person with the best information. Selling is great for a quick exit and a fresh start. Renting is the engine for long-term legacy.

    If you’re feeling stuck, don't forget that you don't have to figure this out alone. Whether you want to list your home for top dollar, find your next investment, or get your funding ready for a big move, we have the tools to make it happen.

    The "Triple Threat" Call to Action

    At MAKE WEALTH REAL, we don't just talk about real estate; we live it. No matter which lane you’re in, we’ve got a path for you:

    • FOR SELLERS: Ready to see what your home is worth in today’s market? Let’s get you a precision valuation and a marketing plan that kills. Check your home value here.
    • FOR BUYERS: Want to find the best deals in the "Affordability Correction"? Browse the latest listings and off-market opportunities. Start your search here.
    • FOR INVESTORS: Stop guessing and start scaling. If you need a professional deal analysis, rehab budget, or a loan submission package that gets funded, let’s get you Investor Ready.

    PLUS: If you want to surround yourself with other high-level investors and learners who are actually doing the work in 2026, come join our Skool Community. It’s the place where we break down deals, share resources, and help you maximize your property value in real-time.

    [Join the Community & Scale Your Wealth]


    Tweet Draft for Sonny:
    "Sell or Rent in 2026? 🏠 The market has shifted, and the 'Great Affordability Correction' is here. Don't leave your equity to chance. Learn how to maximize your property value and get Investor Ready. Check the latest blog! 🚀 #RealEstate2026 #InvestorReady #WealthBuilding"
  • The Real Estate Investor’s Guide to Land Banking at Any Budget

    The Real Estate Investor’s Guide to Land Banking at Any Budget

    Let’s be real for a second: when most people think about real estate investing, they immediately picture a "Fixer Upper" episode. They see themselves knocking down walls, dealing with contractors who don’t show up, and praying the plumbing holds together long enough to find a tenant.

    But what if I told you there’s a way to grow massive wealth in real estate without ever picking up a hammer or taking a midnight call about a broken toilet?

    Welcome to the world of Land Banking.

    Land banking is one of the oldest and most proven ways to build a legacy, yet it’s often overlooked because it’s not "flashy." But at MAKE WEALTH REAL, we aren't about the flash; we’re about the results. Whether you have $5,000 or $500,000, land banking is a strategy that can fit your budget and set your family up for generations.

    What Exactly is Land Banking?

    In the simplest terms, land banking is the practice of purchasing undeveloped land and holding it until it becomes more valuable.

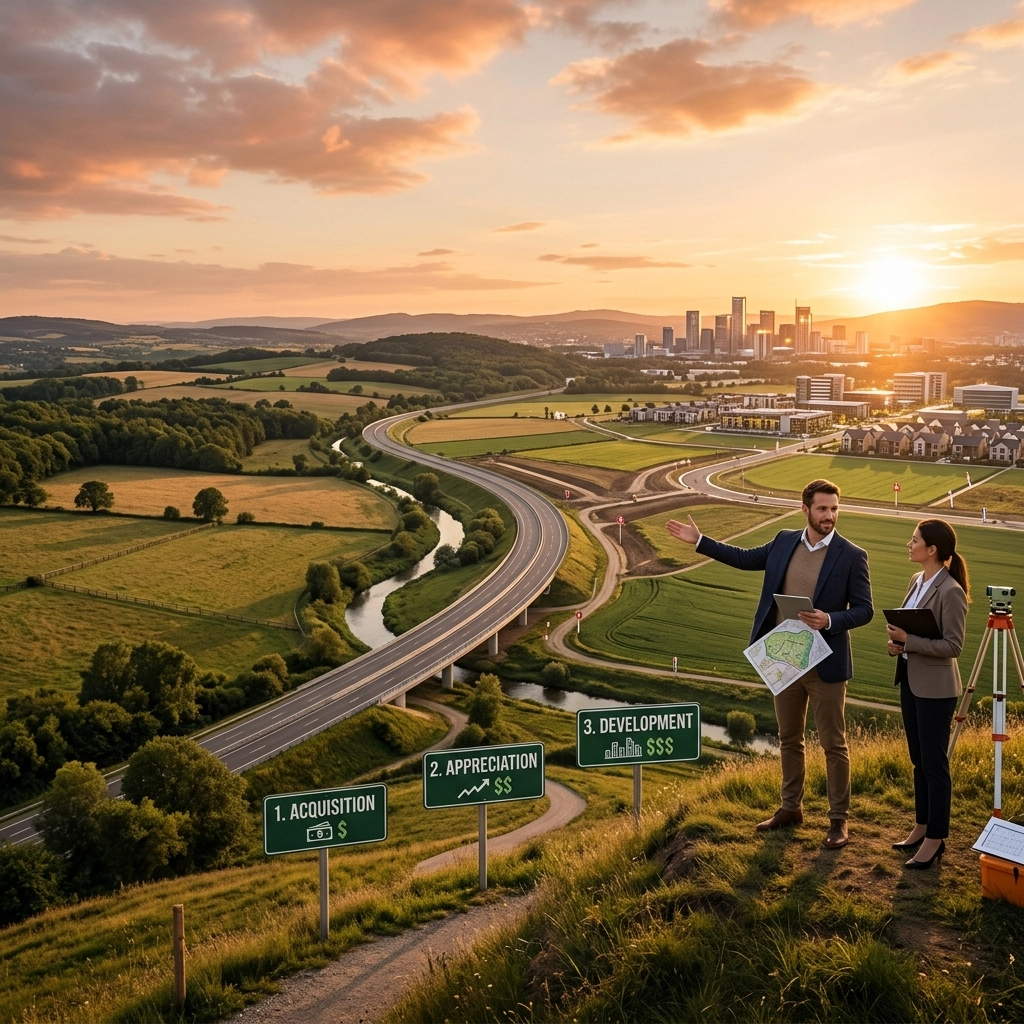
    Think of it like buying a "stock" in a piece of the earth. You aren't buying the land to build a house on it tomorrow. You’re buying it because you’ve identified that, in 5, 10, or 20 years, a developer is going to need that exact spot for a shopping mall, a housing subdivision, or a highway expansion.

    The beauty of land is that they aren't making any more of it. As populations grow and cities expand, that "useless" patch of dirt on the outskirts of town suddenly becomes the most coveted piece of the puzzle.

    Raw land field in the path of progress near a growing modern city skyline.

    Why Land Banking Wins Every Time

    If you’re looking for a low-stress, high-reward investment, land banking checks all the boxes. Here is why savvy investors love it:

    1. Low Entry Costs

    Unlike buying a multi-family unit or a commercial building, raw land is incredibly affordable. You can find parcels of land in the path of growth for a fraction of the cost of a developed property. This makes it the perfect entry point for new investors who want to get their feet wet without taking on a massive mortgage.

    2. Zero Maintenance

    Land doesn’t have a roof that leaks. It doesn’t have carpets that need cleaning. It doesn’t have "tenants from hell." Once you buy it, you essentially just pay the property taxes and wait. It is the ultimate "set it and forget it" investment.

    3. Forced Appreciation through Scarcity

    As urban sprawl continues, the demand for land increases while the supply stays exactly the same. When you hold land in a high-growth area, you aren't just hoping it goes up in value; you are waiting for the market to catch up to your foresight.

    How to Start Land Banking on Your Budget

    You don't need to be a billionaire to start land banking. Here is how you can approach it based on where you are financially right now.

    The "Starter" Budget ($2,000 – $10,000)

    At this level, you’re looking for raw land in rural areas that are just starting to see interest. Look for land near emerging recreational areas or small towns that are seeing a slow but steady population increase. You might even look into tax lien sales or distressed land auctions to pick up property for pennies on the dollar.

    The "Growth" Budget ($10,000 – $50,000)

    With a bit more capital, you can start looking at the "path of progress." This means identifying the outer edges of a major metropolitan area. Look at where the newest suburbs are being built and go two exits further down the highway. At this budget, you can often negotiate Seller Financing, which allows you to control a larger piece of land with a smaller down payment.

    The "Strategic" Budget ($50,000+)

    Now you’re playing with the big dogs. At this level, you can look for land that is already zoned (or can be re-zoned) for commercial or high-density residential use. You can also look into Land Syndication, where you pool your money with other investors to buy massive tracts of land that can eventually be sold to major developers.

    Real estate investor using a digital map to evaluate rural land for banking.

    Financing Your Land Investment

    One common myth is that you can’t get a loan for land. While it’s true that big banks are more cautious about raw land (because they can’t exactly foreclose on a house that isn't there), you still have options:

    • Self-Financing: If you have the cash, this is the cleanest way. You own the asset outright and have no debt hanging over your head.
    • Seller Financing: This is the "secret sauce" of land banking. Many land owners are happy to take a down payment and monthly interest, essentially acting as the bank for you.
    • Real Brokerage Lending Partners: This is where having the right team comes in. Through our partnerships, we can help you navigate loan submission packages that are specifically designed for investors.

    Maximizing Your Returns: The Research Phase

    You don't just buy any piece of dirt. To make land banking work, you have to be a bit of a detective.

    1. Check Zoning Laws: Is the land zoned for what you think it’s for? Don't buy "residential" land hoping to sell it to a Walmart developer.
    2. Infrastructure is King: Is the city planning to run water and sewer lines to that area? Is there a new highway on-ramp planned nearby? Infrastructure drives value.
    3. Passive Income While You Hold: Just because there isn't a building doesn't mean the land can't make money. You can lease the land to farmers, use it for billboard placement, or even lease it to cellular companies for towers. This helps cover your property taxes while you wait for the big payday.

    Strategic plot of undeveloped land near major highway infrastructure and development.

    Getting Investor Ready

    At MAKE WEALTH REAL, we know that the biggest hurdle for most investors isn't finding the land, it’s getting the funding and doing the due diligence.

    This is exactly why Lamont Milbourne offers a specialized Funding Preparation Service. If you’re serious about land banking or any real estate investment, you need to be "Investor Ready." Our package isn't just a "good luck" pat on the back; it’s a full-scale strategy that includes:

    • Detailed Deal Analysis: We look at the numbers to make sure the "path of progress" actually leads to profit.
    • ARV Comps & Rehab Budgets: Even if you’re just holding land, knowing the After Repair Value of the potential development is key to your exit strategy.
    • Loan Submission Packages: We work with our Real Brokerage lending partners to put together professional packages that get lenders to say "Yes."

    If you’re looking to scale your portfolio, you shouldn't be doing this alone. You need the strategies and the data to back up your moves.

    Your Path to a Real Estate Legacy

    Land banking is about patience, but it’s also about action. Every day you wait is a day that the land in the path of growth gets more expensive. You don't have to be an expert developer to win; you just have to have the foresight to own the ground they want to build on.

    Whether you are looking to secure a small parcel for your kids' future or you're ready to move on a multi-acre tract for a major flip, the principles remain the same: buy low, hold steady, and let the market do the heavy lifting for you.

    For more information on properties and to see what we're working on, check out:
    👉 Millis Property
    👉 Lamont Milbourne on Real

    Whether you're looking to Sell, Buy, or Invest, we have the strategies you need.


    Tweet Draft for Sonny:
    "Stop chasing tenants and start banking land! 🌍 Land banking is the ultimate low-maintenance real estate play for any budget. Check out our latest guide on how to build a legacy with raw land. #RealEstateInvesting #LandBanking #MakeWealthReal #InvestorReady"

  • How to Buy a House with Bad Credit in Maryland: Fixing Your Score First

    How to Buy a House with Bad Credit in Maryland: Fixing Your Score First

    Let’s be real for a second: the Maryland real estate market is moving fast. Whether you’re looking at a cozy rowhome in Dundalk, a waterfront spot in Middle River, or a family nest in Essex, the competition is stiff. You’ve probably spent hours scrolling through listings, imagining where your furniture would go, only to hit a brick wall the moment you think about your credit score.

    If your score is sitting in the 500s or low 600s, you’ve likely heard a lot of "nos." Maybe a lender told you to come back in a year. Maybe you’re tired of paying rent that’s higher than a mortgage payment would be.

    Here is the truth: You can find ways to buy a house with bad credit in Maryland, but the real question is, should you?

    At MAKE WEALTH REAL, we believe in building legacies, not just signing contracts. Buying a home with a bottom-tier credit score often means settling for predatory interest rates and massive down payments that drain your savings. Today, we’re going to talk about why fixing your score first is the ultimate power move and how our MWR Financial membership can get you to the closing table faster than you think.

    The Reality of Buying a House with Bad Credit in Maryland

    In Maryland, the "minimum" score to get a mortgage depends heavily on the type of loan you’re chasing.

    1. FHA Loans: These are the most popular for first-time buyers. Technically, you can qualify with a 500 score, but there's a catch, you’ll need a 10% down payment. If you can get that score up to 580, your down payment drops to just 3.5%.
    2. Conventional Loans: Most lenders won’t even look at you unless you’re at a 620 or higher.
    3. VA and USDA Loans: These are great because they often require $0 down, but lenders still usually "overlay" a requirement for a score around 600-640.

    But here is what the lenders don't always tell you: The lower the score, the higher the cost.

    A 1% difference in your mortgage interest rate might not sound like much, but over 30 years, it can cost you $50,000 to $100,000 extra. That is money that should be in your retirement account or your kid’s college fund, not the bank's pocket.

    A golden staircase representing a high credit score leading to a Maryland colonial home. A graph showing the massive difference in total interest paid over 30 years between a 580 credit score and a 720 credit score.

    Why "Fixing Your Score First" is the Ultimate Strategy

    When you focus on credit restoration before you start house hunting, you aren't just "cleaning up" your past; you are maximizing your future buying power.

    1. Lower Interest Rates = More House

    When your credit is healthy (think 700+), lenders compete for your business. You get the lowest rates available, which means your monthly payment is lower. This allows you to qualify for a higher loan amount. That extra bedroom or that finished basement becomes a reality simply because your credit score did the heavy lifting.

    2. Elimination of High Private Mortgage Insurance (PMI)

    If you have a lower score, your PMI (the insurance you pay to protect the lender) is usually much higher. By raising your score, you can significantly reduce this monthly "dead money" expense.

    3. Negotiating Power

    In Maryland markets like Middle River or Essex, you might be competing with multiple offers. A pre-approval letter backed by a strong credit score tells the seller you are a "sure thing." Sellers hate deals that fall through because of financing issues. A high score is your badge of financial reliability.

    Hand holding a mortgage approval letter in front of a sold brick home in Dundalk, Maryland.

    How MWR Financial Turns "No" into "Approved"

    Most people think fixing their credit means sending a few angry letters to the credit bureaus and hoping for the best. That’s not how we do it. At MAKE WEALTH REAL, we provide a comprehensive Financial Makeover.

    Through our MWR Financial Membership, you get access to experts who handle the heavy lifting for you. We don't just "fix" credit; we manage your entire wealth profile.

    Credit Restoration (The Financial Edge)

    Our experts work directly with the credit bureaus to challenge inaccuracies, outdated information, and unfair reporting. We’ve seen members see significant jumps in their scores in a fraction of the time it would take to do it alone. We focus on the "Big Five" of credit: payment history, credit utilization, length of credit history, new credit, and credit mix.

    Debt Shredder

    One of the biggest hurdles to buying a house with bad credit in Maryland is your Debt-to-Income (DTI) ratio. Even if your score is "okay," if you have too much credit card debt or a massive car note, the bank will say no. Our Debt Shredder program uses a powerful algorithm to show you exactly how to eliminate your debt in record time without spending a penny more than you currently do.

    Cash Flow Management

    We help you find "lost" money in your current budget through tax reduction and bill negotiation. Imagine taking $300-$500 a month that you were overpaying in taxes and redirecting it toward your down payment fund.

    Financial command center illustrating credit restoration and saving for a Maryland home down payment. Promotional graphic for MWR Financial showing the benefits of credit restoration and debt elimination for future homeowners.

    The Steps to Your Maryland Home

    If you're ready to stop renting and start owning, here is the roadmap we recommend:

    1. Assess the Damage: Get a full look at your credit report. Don’t just look at the number; look at the "why." Are there late payments? High balances?
    2. Join the MWR Movement: Don’t try to DIY your financial future. Our membership gives you a team of experts for less than the cost of a daily latte.
    3. Build Your Down Payment: While we work on your score, use our Cash Flow strategies to stack your cash.
    4. Get Pre-Approved: Once your score is in the "Green Zone," we’ll help you get in front of the right lenders who value your new financial strength.

    Stop Settling for "Bad Credit" Loans

    You deserve a home that represents a fresh start, not a financial burden. Buying a house with bad credit in Maryland is possible, but buying a house with excellent credit is a game-changer.

    Don't let a three-digit number dictate where your family lives. Take control of your financial narrative today. Whether you are in Baltimore County, Harford County, or anywhere in the Old Line State, the path to homeownership starts with a solid financial foundation.

    Ready to start your Financial Makeover and get "lender-ready"?

    👉 Join MWR Financial Today and let our experts start working on your credit restoration and debt elimination.

    👉 Still have questions? Let's talk about your goals. Schedule a 30-minute consultation on my calendar here and let’s map out your path to the closing table.


    🐦 Tweet Draft for Sonny:

    "Maryland homeowners-to-be: Stop letting a low credit score hold you back! 🏠 MD is competitive: get the edge by fixing your score FIRST. Lower rates, lower fees, and a better home. Check out our latest guide on buying with credit confidence: [Link] #MarylandRealEstate #MWRFinancial #CreditRestoration"

  • How to Get $50k in Business Funding Without Personal Credit

    How to Get $50k in Business Funding Without Personal Credit

    Let’s be real for a second: the traditional banking system isn't exactly set up for the "little guy" to win. If you’ve ever tried to get a business loan, you know the drill. They want to see your tax returns for the last three years, they want to know what your house is worth in case you default, and most importantly, they want to see a personal credit score that's basically perfect.

    It feels like you’re being punished for wanting to build something of your own. You’re told that to grow your business, you need capital. But to get capital, you already need to be wealthy or have a flawless financial history. It’s a "chicken and the egg" scenario that leaves most entrepreneurs stuck in the mud.

    But what if I told you there’s a way to bypass that entire headache? What if you could secure $50,000 in unsecured business funding without ever having to put your personal credit on the line?

    At MAKE WEALTH REAL, we believe in empowering you to create a legacy that isn't tied to your Social Security number. It’s time to stop playing by the banks' old rules and start using the strategies that big corporations use to scale.

    The Trap of the Personal Guarantee

    Most small business owners make one massive mistake early on: they use their personal credit to fund their business. They swipe their personal Visa for office supplies, they take out personal loans for inventory, and they put their personal assets up as collateral.

    This is a recipe for disaster. When you tie your personal credit to your business, your debt-to-income ratio sky-rockets. Suddenly, even though your business is doing okay, you can’t get a car loan or a mortgage because your personal credit report says you’re "over-extended."

    Worst of all, if the business hits a rough patch, your personal life takes the hit. Your house, your car, and your family's security are all on the chopping block. That isn’t freedom; that’s a trap.

    A briefcase chained to house keys representing the personal guarantee trap in business funding.

    Enter the MWR Funding Concierge

    This is where things get exciting. Through the Lifestyle & Legacy Membership, we provide access to a dedicated Funding Concierge. We don’t just give you a PDF and wish you luck; we provide a high-level, "done-with-you" service that guides you through the process of building a business entity that stands on its own two feet.

    The goal? To get you a guaranteed $50,000 in unsecured business funding.

    Wait, did I say guaranteed? Yes. And did I say unsecured? Absolutely. That means no collateral: no putting up your home or your 401(k) to get the cash you need to grow. And the best part? It’s done with no personal credit check. We focus on building your business credit profile so the business gets funded based on its own merit, not yours.

    How Business Credit Actually Works

    Most people don't realize that your business is its own "person" in the eyes of the law and the credit bureaus. Just like you have a Social Security number, your business has an EIN (Employer Identification Number). And just like you have a FICO score, your business has a Paydex score (through Dun & Bradstreet) and other business credit ratings.

    The secret to getting $50k (and eventually much more) is making your business look "fundable" to lenders. Banks aren't necessarily looking for how much money you have; they’re looking for compliance.

    Phase 1: The Compliance Check

    Lenders have a secret checklist. If your business address is a P.O. Box, you might get a red flag. If your phone number is just your personal cell, that’s another red flag. Our Funding Concierge helps you ensure your business is set up correctly from day one so you don't get auto-declined by a computer algorithm.

    Phase 2: Building the Profile

    You can't just walk into a bank and ask for $50k with a brand-new EIN. You need to build a history. We show you how to work with "Tier 1" vendors: companies that will give you net-30 terms and, more importantly, report those payments to the business credit bureaus. Once you have a few of these reporting, your business credit score starts to climb.

    Phase 3: The Funding Round

    Once the foundation is solid, our experts step in to help you navigate the funding landscape. Whether it's through no-doc business loans, lines of credit, or SBA microloans, we help you secure that $50,000.

    MWR @Home Opportunity Promotion

    Why Revenue and Cash Flow are King

    As mentioned in recent financial research, many modern lenders are shifting away from personal credit scores and moving toward revenue-based financing. They want to see that your business has consistent cash flow.

    For businesses already generating revenue, we can often accelerate the funding process. If you can show 3 to 6 months of solid bank statements, lenders are much more likely to hand over the keys to a $50k line of credit because they can see the money moving through your accounts.

    But even if you’re just starting out, the Lifestyle & Legacy Membership gives you the roadmap to get there. We focus on the "Triple Threat" of financial success: reducing your taxes, eliminating your debt, and building your credit (both personal and business).

    Digital gold coins flowing on a desk symbolizing strong business cash flow and revenue-based funding.

    It’s About More Than Just the Money

    Look, $50,000 is a game-changer for most businesses. It’s the ability to hire that key employee, invest in that marketing campaign, or buy the equipment that doubles your production. But at MAKE WEALTH REAL, we know that money is just a tool.

    The real goal is Legacy.

    When you build business credit that isn't tied to your personal life, you are building an asset that can be sold, passed down, or scaled infinitely. You are separating your personal identity from your professional liabilities. That is true financial sophistication.

    The Lifestyle & Legacy Membership is designed to take the stress out of this process. Instead of spending hundreds of hours on YouTube trying to figure out which vendors report to which bureaus, you get a direct line to experts who do this every single day.

    S.I.M.P.L.E Leverage Everything! Weekly Event Promotional Graphic

    Common Myths About Business Funding

    Myth #1: "I need to be in business for 2 years."
    While traditional banks love the 2-year mark, many alternative lenders and business credit strategies allow you to get funded much sooner: sometimes in as little as 6 months: if your compliance and Tier 1 reporting are handled correctly.

    Myth #2: "I need to show a profit on my tax returns."
    This is the ultimate catch-22. Your accountant tells you to write everything off so you don't pay taxes, but then the bank tells you that you don't "make enough money" to qualify for a loan. Business credit ignores this. It’s about creditworthiness and cash flow, not just the bottom line on your 1040.

    Myth #3: "High interest rates make it not worth it."
    While it's true that no-doc or low-credit loans can have higher rates, you have to look at the ROI. If $50k in funding allows you to generate an extra $100k in profit, the interest is just a small cost of doing business. Plus, as your business credit improves, your rates go down.

    Motivational Finance Prompt Graphic

    Take the First Step Toward Your $50k

    You don’t have to stay stuck. You don't have to keep praying that your personal credit score jumps 20 points so you can finally grow your dream. There is a system, a process, and a team ready to help you execute.

    The MWR Financial Lifestyle & Legacy Membership is your gateway to the Funding Concierge and the guaranteed $50,000 path. It’s time to stop being a "business owner" who is just an employee of their own debt and start being a true entrepreneur.

    Ready to get started?

    Your financial makeover begins now. Don’t let another year go by where you’re held back by personal credit limitations. Join the movement and start building the wealth you and your family deserve.

    1. Join the Membership: Head over to www.mwrfinancial.com/krnrstn21 to sign up and get immediate access to our Funding Concierge and financial experts.
    2. Join the Community: Connect with other like-minded wealth builders in our Skool Community. Share your wins, ask questions, and get the support you need to reach that $50k goal.

    Stop dreaming about growth and start funding it. Let’s Make Wealth Real!


    Tweet Draft for Sonny:
    🚀 Stop risking your personal assets for your business! Learn how to secure $50,000 in UNSECURED business funding with NO personal credit check. Our Funding Concierge makes it easy. Read the full guide here: [Link] #BusinessCredit #FinancialFreedom #MWRFinancial #SmallBizTips

  • Looking For $50k in Business Funding? Here Are 10 Things You Should Know

    Looking For $50k in Business Funding? Here Are 10 Things You Should Know

    Let’s be real for a second. You have a vision. You have the drive. You might even have the perfect business plan sitting on your laptop right now. But there is one giant, annoying wall standing between you and your empire: Capital.

    Most entrepreneurs think that getting $50,000 to scale their business requires a perfect 800 credit score, a lung to give as collateral, and a five-year history of massive profits. We’re here to tell you that the "old way" of doing things is dead. At MAKE WEALTH REAL, we believe in empowering you to build a legacy without the gatekeepers holding you back.

    If you’re looking to secure at least $50,000 in business funding, here are 10 things you absolutely need to know to win the game in 2026.

    1. Traditional Banks Are Not Your Friends (Right Now)

    Look, we love a good local bank for a checking account, but when it comes to business funding, they are often the hardest door to kick down. Most traditional banks want to see two-plus years of tax returns, consistent high revenue, and a personal credit score that looks like a high-score on a video game.

    The rejection rate for small business loans at big banks is notoriously high. If you’ve been told "no" by a bank, don’t take it personally. They are built on old-school risk models. Our MWR Financial Business Funding concierge exists because we know there’s a better way to get the cash you need without the "banker's headache."

    2. The $50,000 Guarantee is Real

    One of the biggest hurdles in business is the "maybe." Maybe I’ll get funded, maybe I won’t. That uncertainty keeps you from ordering inventory, hiring that key employee, or launching that marketing campaign.

    With MWR Financial, we don't do "maybe." We offer a guaranteed minimum of $50,000 in business funding. When you have a concierge service that knows the landscape, we can navigate the system to ensure you get the capital you deserve. This isn't just a "hope and pray" strategy; it’s a calculated, expert-led path to capital.

    3. Your Personal Credit Score Doesn't Have to Be the Boss

    This is where most people get stuck. They think, "My personal credit isn't great, so I can't start a business."

    Stop right there.

    One of the most powerful aspects of our funding concierge is that we focus on Business Funding that doesn't require personal credit or collateral. We help you separate your personal life from your business life. Why should a medical bill from three years ago stop you from opening a successful boutique or consulting firm today? It shouldn't. We focus on the strength of the business entity and the funding pathways that don't lean on your personal FICO score.

    Professional transformation from personal credit cards to business funding on an executive office desk.

    4. Collateral is Overrated

    Back in the day, if you wanted $50k, you had to put up your house, your car, or your first-born child (okay, maybe not the kid, but it felt like it). This is called "collateral," and it’s a massive risk for any business owner. If the business hits a bump in the road, you lose your personal assets.

    The MWR approach focuses on unsecured business funding. This means you aren't putting your home on the line to grow your dream. By leveraging business credit and specific funding vehicles, we get you the $50k+ without the "give me your house" requirements of traditional lenders.

    5. Consistency in Your "Digital Footprint" Matters

    Lenders in 2026 are using algorithms to verify your business. If your business address on Google doesn't match your address on your Secretary of State filing, or if your phone number is different on your IRS records than it is on your website, you get flagged.

    These "mismatches" are the number one reason for automated denials. Part of the expert guidance you get with MWR is ensuring your business is "fundable" from an administrative standpoint. We make sure you look like a pro on paper so the money flows easier.

    6. The Concierge Advantage vs. The DIY Struggle

    You could spend the next six months watching YouTube videos and trying to figure out how to build business credit and apply for loans yourself. But as a business owner, your time is your most valuable asset.

    Why struggle alone when you can have a Business Funding Concierge do the heavy lifting? Our experts know which lenders are "hot" and which ones are "cold." They know the specific "hooks" that get applications approved. Having a concierge is like having a VIP pass to the front of the line.

    S.I.M.P.L.E Leverage Everything!

    7. Speed is a Competitive Advantage

    In business, timing is everything. If you see a deal on inventory that expires in 48 hours, a bank loan that takes 60 days to process is useless to you.

    Many "no-doc" or alternative funding routes prioritize speed. While traditional routes move at the speed of a turtle, our concierge helps you find the fast-track options. Getting that $50k in weeks instead of months can be the difference between a record-breaking year and just "getting by."

    8. You Can Use the Funds for (Almost) Anything

    When you get $50,000 through the right channels, you have the flexibility to use it where it counts.

    • Payroll: Hire the talent that frees up your time.
    • Inventory: Bulk buy to increase your margins.
    • Marketing: Turn on the lead-generation faucet.
    • Technology: Get the tools that automate your workflow.

    We don't micromanage how you build your empire. We just provide the fuel for the engine.

    9. Business Credit is Your "Legacy" Financial Profile

    Getting $50k now is great, but building a business credit profile that can access $500k later is even better. This is part of the "Legacy" in our Lifestyle & Legacy Membership.

    We don't just want to get you a one-time check. We want to help you establish a business entity that stands on its own two feet. When your business has its own credit score (think Paydex scores), it becomes an asset that can eventually be sold or passed down, independent of your personal financial situation.

    10. The Barrier to Entry is Lower Than You Think

    Most people count themselves out before they even try. They assume they aren't "big enough" or "ready enough."

    The truth? You don't need a massive office and 20 employees to qualify for business funding. You just need the right structure and the right experts in your corner. Whether you are a solo-preneur or a growing team, the capital is out there. You just need the key to unlock it.

    Successful entrepreneur viewing business growth charts and achieving financial freedom in a modern office.

    Stop Searching, Start Funding

    You've spent enough time wondering "what if." What if you had the capital to really go for it? What if you didn't have to worry about your personal credit holding your business back?

    At MAKE WEALTH REAL, we are in the business of turning "what if" into "what's next." Our Business Funding Concierge is just one piece of the puzzle, but it’s a massive one. We handle the technicalities, the lender relationships, and the strategy, so you can stay focused on being the CEO.

    If you’re ready to secure your $50,000 minimum guarantee and stop playing small, it’s time to join the movement.

    Join the Lifestyle & Legacy Membership today for expert funding guidance and start building the wealth you were meant to have.

    👉 Sign up for your Financial Transformation here!

    For more information on all our life-changing programs, visit www.mwrfinancial.com.


    Tweet Draft for Sonny:
    🚀 Stop letting personal credit hold your business back! We’re talking $50k MINIMUM business funding with NO personal credit or collateral needed. 💰 Stop guessing and start growing. Check the blog for 10 things you need to know! #BusinessFunding #MWRFinancial #WealthBuilding #EntrepreneurLife @LamontMilbourne

  • Looking For Off-Market Deals? Here Are 10 Things You Should Know

    Looking For Off-Market Deals? Here Are 10 Things You Should Know

    In the current real estate climate, the Multiple Listing Service (MLS) often feels like a digital battlefield. You find a property, you run the numbers, and before you can even schedule a walkthrough, there are fifteen offers on the table: most of them over asking price. If you want to build real wealth through property, you have to look where everyone else isn’t looking.

    Welcome to the world of off-market deals. Often referred to as "pocket listings," these properties are the hidden gems of the real estate industry. They offer the potential for better margins, less stress, and deeper equity from day one. But finding them isn’t as simple as refreshing a browser window. It takes a strategy, a network, and a specific set of skills.

    At MAKE WEALTH REAL, we believe in empowering you with the tools to take control of your financial future. Whether you are a first-time buyer or a seasoned investor, understanding the off-market landscape is a game-changer.

    Here are 10 things you need to know about finding and closing off-market real estate deals.

    1. What "Off-Market" Really Means

    An off-market property is simply a home or commercial building for sale that is not listed on the public MLS. These transactions happen behind closed doors through private networks, direct negotiations, or word-of-mouth. Because they aren't broadcast to the general public, the "frenzy" factor is removed. For an investor, this is the difference between a high-pressure bidding war and a professional business negotiation.

    2. The Power of Privacy for Sellers

    Why would someone sell off-market? It’s a common question. Often, it comes down to privacy. High-net-worth individuals, celebrities, or even families going through sensitive situations like divorce or probate may not want a "For Sale" sign in the yard or hundreds of strangers walking through their bedrooms. By tapping into these deals, you are often providing a service to the seller by offering a discreet, professional exit strategy.

    Luxury home at twilight representing private, off-market real estate deals and discreet property sales. A quiet, exclusive residential neighborhood symbolizing private, off-market real estate opportunities.

    3. Less Competition, Better Pricing

    The most obvious benefit is the lack of competition. When a property is on Zillow, you are competing with the world. When it’s off-market, you might be the only person at the table. This allows for a much more realistic purchase price. Without the "emotional" bidding that happens in public auctions or open houses, the price remains tethered to the actual value of the asset and the specific needs of the seller.

    4. Transactional Flexibility

    Off-market deals are famous for their flexible terms. Because you are dealing directly with the seller (or through a single intermediary), you can often negotiate timelines that the MLS wouldn't allow. Need a 60-day close because you're waiting on other funds? Or perhaps the seller needs to stay in the home for three months after the sale? These nuances are much easier to navigate when there aren't ten other "standard" offers breathing down the seller's neck.

    5. Building Your Insider Network

    You cannot find off-market deals sitting on your couch. This is a contact sport. You need to build relationships with:

    • Wholesalers: People who specialize in finding distressed properties and "assigning" the contracts to investors.
    • Estate Attorneys: They often know when a property needs to be liquidated to settle an estate.
    • Contractors: They see the homes that are falling apart before the owners even decide to sell.

    Working with an agent who has a "deep bench" is also vital. At The Real Brokerage, we pride ourselves on having the boots-on-the-ground intelligence to find these opportunities before they hit the general market.

    6. Direct Outreach: The "Old School" Way

    Don't underestimate the power of direct mail or "driving for dollars." Many of the best deals come from identifying a property that looks neglected and reaching out to the owner directly. Whether it's a handwritten note or a targeted mail campaign, direct outreach shows the owner that you are a serious, proactive buyer.

    Motivational Finance Prompt Graphic

    7. Digital Hunting and Social Platforms

    In 2026, the "digital neighborhood" is a goldmine. Facebook Marketplace, local community groups, and specialized real estate forums often have owners posting "thinking of selling" messages. Monitoring these channels requires consistency, but the rewards are high. You can often connect with a seller before they’ve even spoken to a listing agent.

    8. Due Diligence is Non-Negotiable

    Because off-market deals aren't vetted by a traditional listing process, the burden of due diligence falls entirely on you. You must be rigorous. This includes:

    • Title Searches: Ensure there are no hidden liens or ownership disputes.
    • Zoning Verification: Confirm the property can actually be used for your intended purpose.
    • Comprehensive Inspections: Off-market often means "as-is." You need to know exactly what the rehab costs will be before you sign.

    9. The Critical Need for Professional Funding Prep

    This is where most investors stumble. You find a great off-market deal, but because the seller wants a quick, hassle-free close, you need your financing locked and loaded. If you come to the table disorganized, the deal will go to the person with the "cleanest" offer.

    To help you bridge this gap, Lamont Milbourne offers a Paid Funding Preparation Service. We don’t just "look" at deals; we prepare them for battle. This service includes:

    • Comprehensive Deal Analysis: Is it actually a good deal?
    • ARV (After Repair Value) Comps: Knowing exactly what it's worth once the work is done.
    • Rehab Budgets: Detailed estimates so you don't overspend.
    • Loan Submission Packages: Professional presentations for our lending partners at The Real Brokerage.

    When you use a professional package, lenders take you seriously, and sellers see you as a "sure thing."

    Explore our property services here: Millis Property Group and see how we represent you at Real Brokerage – Lamont Milbourne.

    10. Multi-Stream Income: Leveraging the Deal

    An off-market deal isn't just a house; it's a vehicle for wealth. At MAKE WEALTH REAL, we focus on how these real estate moves fit into your larger financial makeover. Are you using the equity to eliminate debt? Are you leveraging the cash flow to build a private reserve account? Real estate is one piece of the puzzle, but the goal is total financial transformation.

    MWR @Home Opportunity Promotion


    The Triple Threat: A Call to Action

    No matter where you sit in the real estate market, off-market strategies offer a path forward:

    • For SELLERS: Want to sell your property without the circus of open houses and signs? We provide a discreet, professional way to connect with qualified buyers and investors who value your privacy.
    • For BUYERS: Tired of losing out on your dream home? Let us help you find the "hidden" inventory that isn't on the apps.
    • For INVESTORS: If you want to scale, you need a pipeline. Let us help you analyze your deals and prepare your funding packages so you can close more often and more profitably.

    The secret to consistent deal flow is maintaining multiple paths to ownership. Don't limit yourself to what's "available" to everyone else. Go where the wealth is being made.

    Start Your Financial Transformation

    Finding the deal is only half the battle; keeping the wealth you create is the other. Join the MWR Financial membership today to begin your comprehensive Financial Transformation. From tax reduction to credit restoration and debt elimination, we give you the foundation to ensure that every real estate deal you close actually moves the needle for your family’s future.

    Start Your Financial Makeover Here

    For more information on our programs and how we help you Make Wealth Real, visit www.mwrfinancial.com.


    Tweet Draft for Sonny:
    🚀 Want to beat the MLS madness? Off-market deals are the secret to real estate wealth. Check out our latest guide on how to find "hidden" properties and why professional funding prep is your #1 advantage. 🏠💰 Read more: [Link to Blog] #RealEstateInvesting #OffMarketDeals #MakeWealthReal #FinancialFreedom

  • The Ultimate Guide to Financial Resilience: Everything You Need to Succeed Right Now

    The Ultimate Guide to Financial Resilience: Everything You Need to Succeed Right Now

    Let’s be real for a second: life has a funny way of throwing curveballs when you least expect them. One day you’re cruising along, and the next, your car needs a new transmission, the roof starts leaking, or the economy decides to take a rollercoaster dip. Most people hear the word "resilience" and think of emotional strength, but there is another side to that coin that is just as vital: Financial Resilience.

    Financial resilience isn't just about having a few extra bucks under your mattress. It’s about building a fortress around your lifestyle so that when the world gets loud, your bank account stays quiet. It’s the ability to handle unexpected challenges and bounce back from disruptions without feeling like your entire world is ending.

    At MAKE WEALTH REAL, we believe wealth isn’t just a destination: it’s a mindset and a system. If you want to succeed right now, you need more than a "savings account." You need a strategy. This guide is going to break down exactly how you can build that fortress using the power of the Lifestyle & Legacy Membership and the proven principles of financial freedom.

    Step 1: Face the Music (The Honest Audit)

    You can’t fix what you don’t measure. To build resilience, you have to understand exactly where you stand. Most people have a "vague idea" of their finances, which is essentially the same as having no idea at all.

    Start by creating a net worth statement. On one side, list your assets: what you own (cash, investments, home equity). On the other, list your liabilities: what you owe (credit cards, student loans, mortgage). Subtract the liabilities from the assets, and that’s your starting line.

    But resilience goes deeper. You need to know your total household income flow. This isn't just your 9-to-5 paycheck; it’s side hustles, dividends, or even that family venture you've got brewing. When you know exactly what’s coming in and what’s going out, the "monsters" in your finances start to look a lot smaller.

    Motivational Finance Prompt Graphic

    Step 2: Stop the Bleed with Debt Elimination

    If you want to be resilient, you have to stop paying "interest taxes" to the big banks. Debt is the biggest anchor holding back your financial ship. Every dollar you pay in interest is a dollar that isn't working for you.

    Building resilience means moving strategically to pay down existing debt. We’re not just talking about "pinching pennies" to pay off a credit card. We’re talking about a systematic approach to debt elimination. When you free up that monthly cash flow, you suddenly find yourself with a massive buffer. That buffer is the beginning of your resilience.

    Imagine having an extra $500, $1,000, or $2,000 a month because you no longer owe it to a lender. That money becomes your emergency reserve, your investment capital, and your peace of mind.

    Step 3: The MWR Financial Lifestyle & Legacy Membership

    This is where the magic happens. Many people try to do this alone: tracking spreadsheets, guessing on tax deductions, and trying to negotiate with creditors themselves. The Lifestyle & Legacy Membership from MWR Financial is designed to put a team of experts in your corner to do the heavy lifting for you.

    Resilience is built on four pillars that the membership addresses directly:

    1. Shift: Moving your money from the government’s pocket back into yours through tax reduction.
    2. Increase: Boosting your credit score and your immediate cash flow.
    3. Multiply: Learning how to make your money work as hard for you as you do for it.
    4. Protect: Ensuring your assets are shielded from lawsuits, inflation, and market volatility.

    Modern home with a golden shield symbolizing asset protection and financial resilience for wealth management.

    Step 4: Asset Protection & Tax Strategy

    You can’t be resilient if you’re losing 30-40% of your income to taxes and potential liabilities. Most people think of "wealth management" as something only for the super-rich, but the truth is, the middle class is the most vulnerable to financial shocks.

    Asset protection is about making sure that what you build, you keep. This involves setting up the right structures and using tax strategies that the wealthy have used for decades. By maximizing your deductions (especially if you have a home-based business), you’re effectively giving yourself a raise without having to ask a boss for permission. That "found money" is the fuel for your financial fortress.

    Step 5: Leverage Everything

    One of the core concepts we teach is the "S.I.M.P.L.E" method. Resilience doesn't come from working harder; it comes from leveraging better. You need to leverage experts, leverage systems, and leverage time.

    S.I.M.P.L.E Leverage Everything! Weekly Event

    When you attend events like our weekly "S.I.M.P.L.E Leverage Everything!" sessions, you start to see the bigger picture. You learn how to shift your mindset from "saving" to "multiplying." A resilient person doesn't just have a stash of cash; they have multiple streams of income and a system that grows regardless of what the headlines say.

    Step 6: Create Multiple Streams of Income

    True resilience means if one income stream dries up, you have three others still flowing. This is why the MWR @Home Opportunity is such a game-changer. In today's world, relying on a single paycheck is a high-risk strategy.

    By starting a home-based business with MWR, you aren't just opening up a way to get paid daily, weekly, and monthly; you’re also unlocking over 470 tax deductions that are only available to business owners. You’re taking control of your time and your income. This is the ultimate "insurance policy" against job loss or economic downturns.

    MWR @Home Opportunity Promotion

    Step 7: Build a Real Emergency Reserve

    Experts often suggest having 3-6 months of expenses saved up. While that’s a great start, financial resilience is about having access to capital. An emergency fund is essential for those immediate shocks: like a medical bill or a car repair: but resilience is about the long game.

    As you eliminate debt and increase your cash flow through the Lifestyle & Legacy Membership, you should be funneling those funds into a cash cushion. But don't just let it sit in a traditional savings account where inflation eats it alive. Work with professionals to find safe, liquid places where your money can stay protected but still grow.

    The Resilience Mindset: Waiting is Not a Wealth Strategy

    The biggest enemy of financial resilience is procrastination. Many people wait for "the right time" to start, but the right time was yesterday. The second best time is right now.

    Building wealth and resilience is a journey, but you don't have to walk it alone. You need the tools, the experts, and the community to make it happen. Whether it’s fixing your credit, slashing your debt, or starting a business that pays you while you sleep, every step you take today is a brick in your wall of financial security.

    Are you ready to stop worrying about the "what ifs" and start building a legacy that lasts?

    Your Transformation Starts Here

    Don't leave your financial future to chance. Join the MWR membership today and begin your Financial Transformation. Our experts are ready to help you eliminate debt, reduce taxes, and build the wealth you deserve.

    Start Your Financial Makeover Now at www.mwrfinancial.com/krnrstn21

    For more information on our programs and how we help people across the country, visit www.mwrfinancial.com.


    Tweet Draft for Sonny:
    🚨 Financial resilience isn't a luxury, it's a necessity! Stop living one "curveball" away from disaster. Our latest guide breaks down how to build a fortress around your money using the MWR Lifestyle & Legacy Membership. 🛡️💰 Read more here: [Link] #FinancialFreedom #MWRFinancial #WealthBuilding #DebtFree

  • Are Fix-and-Flips Bad? The Truth About Investing in Today’s Market

    Are Fix-and-Flips Bad? The Truth About Investing in Today’s Market

    If you’ve spent any time on TikTok or HGTV lately, you’ve seen the "Fixer Upper" dream: buy a wreck, spend a weekend painting it, and walk away with a $100,000 check. It looks easy, glamorous, and, most importantly, fast.

    But if you talk to seasoned investors in today’s market, you’ll hear a different story. You’ll hear about soaring interest rates, supply chain hiccups, and holding costs that eat profits faster than a termite infestation. This has led many to ask a blunt question: Are fix-and-flips bad investments now?

    The short answer: No, they aren't "bad." But the "easy money" era is over. To win in 2026, you can’t just be a hobbyist with a hammer; you have to be a strategist with a spreadsheet. At MAKE WEALTH REAL, we believe in empowering you with the truth, not the hype. Let’s dive into the reality of the fix-and-flip market and how you can still build massive wealth if you play the game correctly.

    The Reality Check: Why the Pros are Pivoting

    It’s true that many experienced flippers are stepping back. Even industry leaders like Ryan Pineda have shifted focus toward wholesaling or long-term rentals. Why? Because the "carrying cost" of a property: the loan payments, property taxes, insurance, and utilities you pay while the house is being renovated: has skyrocketed.

    When interest rates are high, every day a contractor is late is money coming directly out of your pocket. In today’s market, market volatility means the price you think you can sell for today might not be the same six months from now.

    S.I.M.P.L.E Leverage Everything! Weekly Event Promotional Graphic

    However, while some are exiting, others are seeing their profits nearly double. How? By focusing on the massive gap in the market. There is an estimated $60 billion to $80 billion worth of unlivable housing stock hitting the market every year. Most modern buyers don't want a "project." They want a move-in-ready sanctuary. If you can provide that efficiently, the demand is still through the roof.

    The Hidden Risks (And How to Avoid Them)

    To succeed, you have to look past the fresh paint and see the financial architecture. Most failed flips don't happen because of a bad color choice; they happen because of bad math.

    1. The "Dealer" Trap

    One of the biggest shocks for new flippers is the tax bill. If the IRS decides you are a "dealer" rather than an "investor," your profits are taxed as ordinary income instead of capital gains. This can wipe out a huge chunk of your return. This is why having a wealth management mindset: like the one we teach at MAKE WEALTH REAL: is vital before you ever swing a sledgehammer.

    2. Over-Renovating

    Investors often fall in love with the property. They put Italian marble in a neighborhood where the buyers are looking for durable laminate. You have to renovate for the market, not for your own ego.

    3. The 70% Rule

    This is the gold standard: your purchase price plus renovation costs should not exceed 70% of the home’s After Repair Value (ARV). In a volatile market, some pros are even aiming for 65%.

    Real estate investor analyzing fix-and-flip profitability using a house model and financial spreadsheets on a desk.

    The Secret Sauce: Professional Funding Preparation

    The difference between a "bad" flip and a wealth-generating machine is the preparation. This is where most solo investors stumble. They find a house, get an "estimate" from a contractor, and hope for the best.

    That is not a business plan; it’s a gamble.

    To bridge this gap, Lamont Milbourne offers a specialized Funding Preparation Service. This isn't just about getting a loan; it’s about presenting a professional-grade package to lenders that proves the deal works. When you work with us through our Real Brokerage lending partners, you aren't just getting "money": you’re getting a roadmap to success.

    Our Funding Prep Package includes:

    • Deep Deal Analysis: We crunch the numbers to ensure the margins are real.
    • Accurate ARV Comps: No guessing. We look at what is actually selling in today's micro-market.
    • Detailed Rehab Budgets: Line-item budgets that lenders trust and contractors can follow.
    • Loan Submission Packages: Professional presentations that get you to the closing table faster.

    If you want to stop guessing and start investing like a pro, you can explore these resources at Millis Property and see how we leverage the Real Brokerage to get deals funded.

    The Triple Threat: Why This Matters to YOU

    Whether you are looking to sell, buy, or invest, the "fix-and-flip" cycle affects you.

    • For Sellers: Do you have a "distressed" property that you think won't sell? You don't need a traditional buyer; you need an investor. We help sellers understand the true value of their property in its current state so they can walk away with cash and no headaches.
    • For Buyers: Looking for your dream home but keep getting outbid? Sometimes the best "move-in ready" home is the one that was just professionally flipped. We help buyers identify quality renovations that won't fall apart after a year.
    • For Investors: You need more than a house; you need a system. From funding prep to deal analysis, we provide the tools to ensure your flip is a financial win, not a nightmare.

    Motivational Finance Prompt Graphic

    Success is a Choice, Not a Gamble

    Are fix-and-flips bad? Only if your strategy is bad. If you are disciplined, use data-driven analysis, and have a team of experts backing your funding and strategy, flipping houses remains one of the most powerful ways to generate active wealth in real estate.

    But remember, real estate is just one piece of the puzzle. To truly make wealth real, you need to protect what you earn, eliminate debt, and multiply your income.

    Ready to transform your financial future?
    Whether you’re looking to close your first flip or simply want to stop living paycheck to paycheck, we are here to help. Join the MAKE WEALTH REAL movement today.

    Begin your Financial Transformation or Financial Makeover right here:
    www.mwrfinancial.com/krnrstn21

    For more information on our specific wealth-building programs, visit www.mwrfinancial.com.


    🐦 Tweet Draft for Sonny:

    "Is house flipping dead in 2026? 🏠 Not even close. But the 'easy money' is gone. To win now, you need data, not just dreams. 📊 Check out our latest blog on the truth about fix-and-flips and how to get your deals professionally funded! #RealEstateInvesting #MakeWealthReal #HouseFlipping #WealthBuilding"

  • 7 Mistakes You’re Making with Business Credit Lines (and How to Fix Them)

    7 Mistakes You’re Making with Business Credit Lines (and How to Fix Them)

    As a business owner, you know that capital is the lifeblood of your operation. When you finally land that business line of credit, it feels like a massive win, and it is! It’s the ultimate safety net and the fuel you need to scale your vision. But here’s the reality: a line of credit is a double-edged sword. Used correctly, it builds a legacy; used poorly, it can sink your ship before you even leave the harbor.

    At MAKE WEALTH REAL, we see entrepreneurs every day who have the drive but lack the roadmap to manage their credit effectively. If you’re making these seven common mistakes, don’t panic. We’re going to show you how to fix them and how our Lifestyle & Legacy Membership can help you turn your financial struggles into a wealth-building machine.


    1. Treating Your Credit Line Like a Personal Windfall

    One of the most dangerous mindsets a business owner can have is viewing a business credit line as "extra income." It’s tempting to see that available balance and think, "I can finally afford that new truck" or "Let's upgrade the office furniture just because."

    The Mistake: Using credit for non-essential luxury items or personal expenses that don’t generate a return on investment (ROI). This adds debt without increasing revenue, leaving you stuck with interest payments on things that aren't growing your business.

    The Fix: Every dollar drawn from your line of credit should have a job. Before you touch a cent, ask yourself: Will this expenditure help me generate more cash flow? If the answer isn't a resounding "Yes," put the card down. Align your withdrawals with a specific business plan.

    Entrepreneur strategically planning business credit usage while reviewing growth charts in a modern office.

    2. Ignoring the Fine Print (Terms and Fees)

    Let’s be real: reading through a 40-page lender agreement is nobody’s idea of a good time. But "skipping to the end" is a mistake that could cost you thousands. Lenders aren't just giving you money out of the goodness of their hearts; they have draw fees, annual maintenance fees, and penalty charges hidden in the weeds.

    The Mistake: Not knowing your interest rate or what triggers a penalty. Some lines of credit have "draw periods" followed by "repayment periods," and if you aren't prepared for the transition, your monthly overhead could suddenly double.

    The Fix: Do your due diligence. Review the interest rates, late payment penalties, and renewal costs before you sign. If you’re already in a deal, sit down this weekend and actually read your statement. Knowledge is power, and knowing your costs helps you budget more effectively.

    3. Borrowing More Than You Actually Need

    It’s the "buffet effect." Just because you’re approved for a $250,000 credit line doesn't mean you should spend $250,000. High credit limits are great for your ego, but high debt loads are terrible for your stress levels.

    The Mistake: Over-leveraging. Borrowing more than necessary increases your interest expenses and puts unnecessary pressure on your monthly cash flow. If your business hits a slow month, that high debt becomes a lead weight.

    The Fix: Only draw what is required for your immediate business needs. By keeping your utilization lower, you not only save on interest but also keep your creditworthiness high. This makes it easier to ask for more money later when a truly massive opportunity arises.

    Motivational Finance Prompt Graphic

    4. Letting Payments Slide (Even by a Day)

    We get it: you’re busy. You’re managing employees, hunting for leads, and putting out fires. Sometimes a bill gets buried on your desk. But in the world of business credit, "close enough" isn't good enough.

    The Mistake: Missing or delaying repayments. Late payments are the fastest way to tank your business credit score. A lower score means higher interest rates in the future, and in some cases, the lender can even freeze your line of credit entirely.

    The Fix: Automation is your best friend. Set up automatic minimum payments at the very least. If you prefer to pay manually, set three different calendar reminders. Consistent, on-time payments demonstrate financial discipline and build trust with your lenders, which is essential for long-term growth.

    5. The "Great Mismatch": Mixing Personal and Business Finances

    This is the big one. If you’re still using your personal credit card for business supplies or: even worse: using your business line of credit to pay your personal mortgage, you are headed for a financial nightmare.

    The Mistake: Co-mingling funds. This creates a mess for your bookkeeper, but more importantly, it’s a massive red flag for the IRS. If you’re audited and your accounts are a tangled web of personal and professional spending, you could lose your corporate veil protection and your tax deductions.

    The Fix: Separate everything. Now. Open a dedicated business checking account and use your business credit line only for business expenses.

    Why this matters for your Legacy: Part of our Lifestyle & Legacy Membership at MWR Financial focuses heavily on Tax Reduction. When you separate your finances properly, our experts can help you tap into over 470 tax deductions that most business owners miss. You can’t claim what you haven't tracked! By organizing your finances, you keep more of your hard-earned money in your pocket instead of handing it to Uncle Sam.

    S.I.M.P.L.E Leverage Everything! Weekly Event Promotional Graphic

    6. Falling for the First Offer You See

    When you need capital, you usually need it now. This urgency often leads business owners to take the first offer that comes their way, even if the terms are predatory.

    The Mistake: Failing to shop around. Not all lenders are created equal. Some specialize in specific industries, while others offer better terms for businesses with high-value equipment.

    The Fix: Compare interest rates, repayment flexibility, and customer service across multiple lenders. A difference of even 2% in your APR can save you tens of thousands of dollars over the life of your business. Take the time to do your homework: your future self will thank you.

    7. Treating Credit Monitoring Like an Option

    Most business owners check their bank balance every day, but they haven't checked their business credit report in a year. This "out of sight, out of mind" approach is a recipe for disaster.

    The Mistake: Ignoring credit monitoring. Errors on credit reports are incredibly common. If a vendor reports a late payment that was actually on time, or if your identity is stolen, you won’t know until you go to apply for a loan and get rejected.

    The Fix: Regularly monitor your reports through Experian, Equifax, and Dun & Bradstreet. Accurate reports are the foundation of your borrowing power.

    The MWR Advantage: If your credit isn't where it needs to be, don't sweat it. As part of the Lifestyle & Legacy Membership, we offer Business Credit Restoration services. We don't just tell you what's wrong; our experts work to help restore your credit, giving you the leverage you need to secure the best rates possible.

    MWR @Home Opportunity Promotion


    How to Turn Your Business Into a Wealth Machine

    Managing a business line of credit is about more than just "having money." It’s about strategy. It’s about knowing how to shift your income, increase your cash flow, and protect your assets.

    At MAKE WEALTH REAL, we believe you shouldn't have to be a financial expert to build a legacy. You just need the right team behind you. Our Lifestyle & Legacy Membership is designed to give business owners like you the tools to succeed:

    • Tax Reduction: Keep more of your paycheck by leveraging the same strategies the wealthy use.
    • Credit Restoration: Clean up your personal and business credit to unlock better opportunities.
    • Debt Elimination: Get a clear path to becoming 100% debt-free in record time.
    • Wealth Generation: Learn how to multiply your money once you’ve saved it.

    You’ve done the hard work of building a business. Now, let’s do the smart work of making sure that business builds wealth for your family for generations to come.

    Ready to start your Financial Makeover?
    Join the movement and start your transformation today.

    👉 Join the MWR Membership Here
    For more information on our programs, visit www.mwrfinancial.com.


    Tweet Draft for Sonny:
    "Stop making these 7 business credit mistakes! 🛑 From mixing personal/business funds to ignoring the fine print, we're breaking down how to fix your finances and build a legacy. Check out the latest blog from MAKE WEALTH REAL! 📈 #BusinessCredit #WealthBuilding #MWRFinancial"

  • Home Equity vs. Private Reserves: Which Is Better For Your Next Property?

    Home Equity vs. Private Reserves: Which Is Better For Your Next Property?

    You’ve found it. The perfect property. Maybe it’s a fixer-upper with massive ARV (After Repair Value) potential, a steady rental in a growing neighborhood, or your next dream home. But as the excitement settles, the big question looms: How are you going to pay for it?

    In the world of real estate investing and strategic home buying, your "how" is just as important as your "what." Two of the most common heavy hitters in the funding world are Home Equity and Private Reserves. Both have the power to close a deal, but they play very different roles in your long-term wealth strategy.

    At MAKE WEALTH REAL, we believe in empowering you with the knowledge to make your money work harder than you do. Today, we’re breaking down the pros, cons, and strategic "why" behind choosing between your own cash and the equity sitting in your walls.

    The Power of Private Reserves: Cash is King (With a Catch)

    When we talk about "private reserves," we’re talking about liquid cash: money sitting in savings, money market accounts, or a highly liquid investment account. Using your own cash to fund a property purchase is the ultimate "clean" deal.

    The Advantages of Cash

    1. Speed and Simplicity: In a competitive market, a cash offer is a nuclear weapon. There are no appraisals required by a lender, no underwriting delays, and no "loan commitment" letters. You can close in days, not weeks.
    2. Zero Interest Costs: When you use your own money, your interest rate is 0%. You aren't paying a bank for the privilege of using their capital.
    3. Positive Cash Flow: If you are buying a rental property, your monthly cash-on-cash return will be significantly higher because you don’t have a monthly mortgage payment eating into your profits.

    The Risks of Cash

    The biggest risk of using private reserves is opportunity cost. If you tie up $200,000 in one property, that money is no longer "liquid." If an even better deal comes along tomorrow, or if you have a medical emergency, that money is stuck in the foundation of your house.

    Furthermore, as our research suggests, if your investment generates returns below the cost of borrowing, cash is preferable. But if you could borrow at 7% and invest that same cash elsewhere for 10%, you’re actually "losing" 3% by using your own money.

    S.I.M.P.L.E Leverage Everything!

    Tapping into the Walls: The Home Equity Strategy

    Home equity is the difference between what your home is worth and what you owe on it. If your home is worth $500,000 and your mortgage is $300,000, you have $200,000 in equity. Through a HELOC (Home Equity Line of Credit) or a Cash-Out Refinance, you can pull that money out to fund your next deal.

    Why Equity Often Wins for Investors

    Home equity is the cornerstone of leverage. Instead of using $100,000 of your own cash to buy one property, you could use $100,000 from a HELOC as down payments for three properties. This allows you to control more real estate with less of your "out of pocket" money.

    1. Preserving Liquidity: You keep your private reserves in the bank for emergencies while using the "lazy money" in your house to grow your portfolio.
    2. Tax Advantages: In many cases, the interest paid on debt used for investment purposes can be tax-deductible (always consult with a tax professional).
    3. Flexibility: A HELOC works like a credit card for your house. You only pay interest on what you use. If you need $20k for a renovation, you take it. When the renovation is done and the value goes up, you pay it back.

    Modern luxury home transforming into a growing real estate portfolio using home equity leverage.

    Comparing the Two: When to Use Which?

    Deciding between equity and reserves isn't a "one-size-fits-all" answer. It depends on the current economic climate and your personal financial standing.

    Use Private Reserves When:

    • Interest rates are high: If a HELOC is sitting at 9% or 10%, but your projected rental yield is only 6%, you are "bleeding" money every month.
    • You want to minimize risk: If you are nearing retirement or have a lower risk tolerance, debt can be a heavy burden. Paying cash ensures that even if the property sits vacant for a month, you aren't scrambling to pay a bank.
    • The market is volatile: If property values are expected to drop, borrowing against your equity could leave you "underwater": owing more than the property is worth.

    Use Home Equity When:

    • You want to scale fast: Leverage is the fastest way to build wealth. If you can borrow at 7% and the property appreciates at 5% while providing a 4% yield, you are winning.
    • You need a revolving fund: For fix-and-flip investors, a HELOC is a dream tool. You use the equity to buy and rehab, sell the flip, pay back the HELOC, and do it again.
    • Interest rates are low: When borrowing is cheap, it makes almost no sense to use your own cash. Keep your cash in a high-yield environment and use the bank's money to buy assets.

    The "Investor Ready" Advantage: Don't Go It Alone

    Whether you choose cash or equity, the success of your deal hinges on the math. This is where most investors stumble. They guess on the rehab costs, they "feel" the ARV is right, and they hope the bank approves them.

    At MAKE WEALTH REAL, we don't believe in "hope" as a strategy.

    Lamont Milbourne offers a specialized Paid Funding Preparation Service designed to get you across the finish line with confidence. When you are looking to secure funding: whether through traditional lenders or our Real Brokerage lending partners: you need a professional package.

    Our Funding Prep includes:

    • Deep-Dive Deal Analysis: Is it actually a good deal? We run the numbers so you don't have to.
    • Accurate ARV Comps: We use professional tools to determine exactly what that property will be worth once it's polished.
    • Detailed Rehab Budgets: No more "guesstimating." We help you outline the costs so your margins stay fat.
    • Loan Submission Packages: We package your deal so it’s "bank-ready," significantly increasing your chances of approval through our lending partners.

    Before you tap into your equity or drain your savings, make sure the deal is worth the move. Visit Millis Property to get your funding prep started.

    MWR @Home Opportunity Promotion

    The Triple Threat: A Strategy for Everyone

    No matter where you are in your real estate journey, the choice between reserves and equity impacts you.

    • For Sellers: You are currently sitting on a mountain of equity. Before you sell and move that money into your next home, consider if a portion of that equity could be used to start an investment portfolio. Don't just "move" your wealth: multiply it.
    • For Buyers: If you’re struggling with high down payment requirements, your current home’s equity might be the key to unlocking your next move without touching your retirement savings.
    • For Investors: The secret is balance. Successful investors often use a mix: private reserves for the "earnest money" and quick fixes, and equity/leverage for the heavy lifting.

    Real estate investors and buyers analyzing property models and wealth growth charts in a modern office.

    Final Thoughts: Building a Solid Foundation

    Choosing between home equity and private reserves is a "good problem" to have. It means you’ve built value and you’ve saved money. But to truly Make Wealth Real, you need to understand how to protect those assets while you grow.

    This is why we advocate for a full Financial Transformation. Real estate is just one piece of the puzzle. You also need to minimize your taxes, eliminate high-interest debt, and ensure your credit score is high enough to snag the best HELOC rates available.

    Ready for Your Financial Makeover?

    If you're ready to stop guessing and start growing, it’s time to join the MWR membership. Whether you need to boost your credit score to access that home equity or you want to find more "hidden money" in your paycheck to build your private reserves, we have the tools to make it happen.

    Start your Financial Transformation here!

    For more information on our programs and how we help thousands of people daily, visit www.mwrfinancial.com.


    Tweet Draft for Sonny:
    "Cash is King, but Equity is the Emperor! 🏠💰 Are you using the right tool for your next property deal? We're diving deep into Home Equity vs. Private Reserves. Plus, see how Lamont's Funding Prep can get you investor-ready!
    Read more: [Link] #RealEstateInvesting #WealthBuilding #MWRFinancial"

    Pique Meme