Category: Uncategorized

  • Land Banking 101: Building Wealth With the Power of Real Estate

    Land Banking 101: Building Wealth With the Power of Real Estate

    Ever wondered how the wealthy keep getting wealthier? One of their best-kept secrets is land banking – and here's the kicker: you don't need millions to get started. Through MWR's land banking program, regular folks are building serious wealth by owning pieces of America's future growth.

    Let's break this down in plain English and show you exactly how this wealth-building strategy can work for you.

    What Is Land Banking, Really?

    Think of land banking as buying a ticket to tomorrow's prosperity. Instead of purchasing developed property with buildings and infrastructure, you're acquiring raw land in areas poised for future growth. It's like buying Apple stock in 1985 – except you're buying actual dirt that people will desperately need later.

    The concept is beautifully simple: buy land today at current prices, hold it while the area develops around it, then sell it years later for significantly more money. No tenants to manage, no midnight repair calls, no property management headaches. Just patient, strategic ownership of one of the most finite resources on earth.
    image_1

    How MWR's Land Banking Program Changes the Game

    Here's where most people get stuck: "I don't have $100,000 lying around to buy land." That's exactly why MWR created their land banking program – to democratize this wealth-building strategy for everyday people.

    Through MWR's program, members gain access to carefully vetted land opportunities that would typically require massive individual investments. The program works by pooling member resources, allowing you to participate in high-quality land banking deals with significantly lower entry points.

    MWR's team of real estate experts does the heavy lifting: they identify promising locations, handle due diligence, manage the acquisition process, and monitor development trends. You get the benefits of professional land banking expertise without needing a real estate license or decades of market experience.

    Why Land Banking Works (Especially Now)

    America isn't making any more land, but it's definitely making more people. Population growth, urbanization, and infrastructure expansion create consistent demand for developable land. Here's what makes this strategy so powerful:

    Inflation Hedge: While your dollars lose buying power, land values typically rise with or above inflation rates. Your dirt becomes more valuable while your debt (if any) becomes cheaper to pay off.

    Limited Supply: Unlike stocks or bonds, there's a finite amount of quality developable land. As cities expand and populations grow, competition for well-positioned parcels intensifies.

    Passive Appreciation: You don't need to actively manage land like rental properties. The value grows while you sleep, work, or focus on other investments.

    Development Catalyst: When infrastructure projects like highways, shopping centers, or residential developments announce nearby construction, your land values can increase dramatically.
    image_2

    Breaking Down the Member Benefits

    MWR's land banking program offers different advantages depending on your financial situation and goals:

    For Beginning Investors: Lower entry costs mean you can start building wealth in real estate without enormous upfront capital. You're learning valuable investment principles while your money grows.

    For Intermediate Members: Land banking diversifies your investment portfolio beyond stocks and bonds. It's tangible wealth you can drive out and see, providing psychological comfort during market volatility.

    For Advanced Wealth Builders: Land banking offers substantial appreciation potential with minimal active management. It complements other wealth-building strategies while requiring little time or attention.

    For Retirement Planning: Long-term land appreciation can provide significant wealth transfer opportunities for your children and grandchildren. Land is generational wealth that families can build upon.

    The MWR Advantage: Professional Management Made Simple

    Most individual investors struggle with land banking because they lack access to quality deals and professional expertise. MWR eliminates these barriers through:

    Market Research: Their team continuously analyzes growth patterns, zoning changes, and infrastructure development plans to identify promising opportunities.

    Due Diligence: Every potential land purchase undergoes thorough investigation including title searches, environmental assessments, and regulatory compliance checks.

    Strategic Timing: Knowing when to buy, hold, and sell requires market expertise that takes years to develop. MWR's professionals handle these critical timing decisions.

    Legal Protection: Proper land banking involves complex legal considerations. MWR ensures all acquisitions meet regulatory requirements and protect member interests.
    image_3

    Getting Started: Your Land Banking Journey

    The beauty of MWR's program is its accessibility. You don't need extensive real estate knowledge or massive capital to begin. Here's typically how it works:

    Education First: MWR provides comprehensive training on land banking principles, helping you understand the strategy before investing your hard-earned money.

    Risk Assessment: Every member receives personalized guidance on how land banking fits their overall wealth-building plan and risk tolerance.

    Opportunity Selection: When quality land banking opportunities arise, qualified members receive detailed presentations explaining the investment thesis and projected returns.

    Ongoing Monitoring: MWR continuously tracks your land investments, providing regular updates on market conditions and value appreciation.

    Real Wealth Creation for Real People

    Land banking isn't just for millionaires anymore. Through MWR's program, teachers, small business owners, and working families are participating in one of the most reliable wealth-building strategies in America.

    The key is starting now and thinking long-term. While day traders chase quick profits and lose their shirts, land banking members are quietly accumulating wealth that could fund their children's education, their own retirement, or their family's financial freedom.
    image_4

    Remember, every major city in America was once empty land. Someone owned that dirt before it became valuable real estate. Today's opportunities exist in tomorrow's growth corridors – places where smart money is quietly positioning itself for future prosperity.

    Your Wealth-Building Future Starts Here

    Land banking through MWR isn't about get-rich-quick schemes or complicated financial engineering. It's about participating in America's growth story through strategic land ownership, professional management, and patient wealth building.

    Whether you're just starting your financial journey or looking to diversify existing wealth, land banking offers a tangible, understandable path to long-term prosperity. And through MWR's program, this opportunity is more accessible than ever before.

    The question isn't whether land values will continue appreciating over time – history shows they will. The question is whether you'll be positioned to benefit from that appreciation.

    Ready to explore how land banking can accelerate your wealth-building journey?

    Start Your Financial Makeover Today (CTA)

    If you’re serious about building real, lasting wealth—and you want a proven game plan with expert support—now’s the time to plug into the MWR Lifestyle & Legacy Membership. Let MWR do the financial heavy lifting while you focus on transforming your income, your options, and your family’s future.

    Start your financial makeover today at www.mwrfinancial.com/krnrstn21.


    Tweet Draft for Sonny:
    "Land banking isn’t just for millionaires. It’s a long-term play for everyday people who want real wealth without tenants, repairs, or constant headaches. Ready to start your financial makeover? www.mwrfinancial.com/krnrstn21 #LandBanking #RealEstate #WealthBuilding #FinancialFreedom"

    Note for Sonny: Please post the tweet to social media to match the blog drop.

  • Mastering the Rehab: How to Budget for Your Next Fix & Flip

    Mastering the Rehab: How to Budget for Your Next Fix & Flip

    Listen, we’ve all seen those home renovation shows where a couple buys a crumbling shack, spends thirty minutes of screen time picking out marble countertops, and walks away with a $100,000 profit. It looks easy, right? But here’s the reality: the profit isn't actually made when you sell the house. It’s made the moment you buy it: and more importantly, it’s preserved by how well you manage your rehab budget.

    At MAKE WEALTH REAL, we’re all about empowering you to build a legacy that lasts. Real estate is one of the most powerful vehicles for that, but if your budget isn't tight, your "investment" can quickly turn into an expensive hobby. Whether you’re a seasoned pro or looking for your first flip, mastering the rehab budget is the difference between a massive payday and a massive headache.

    Let’s break down how to budget like a pro so you can keep your cash flowing and your wealth growing.

    The Golden Rule: The 70% Rule

    Before you even pick up a hammer or hire a contractor, you need to understand the math. In the world of fix-and-flips, we live and die by the 70% Rule.

    The rule is simple: You should never pay more than 70% of the After-Repair Value (ARV) of the property, minus the cost of the renovations.

    Formula: (ARV x 0.70) – Rehab Costs = Your Max Purchase Price.

    If a house will be worth $400,000 once it’s beautiful (that’s your ARV), and it needs $50,000 in work, the math looks like this:

    • $400,000 x 0.70 = $280,000
    • $280,000 – $50,000 = $230,000

    If the seller wants $250,000, you walk away. Why? Because that 30% gap isn't just "extra profit": it covers your holding costs, closing costs, selling fees, and the inevitable "oops" moments that happen in every flip.

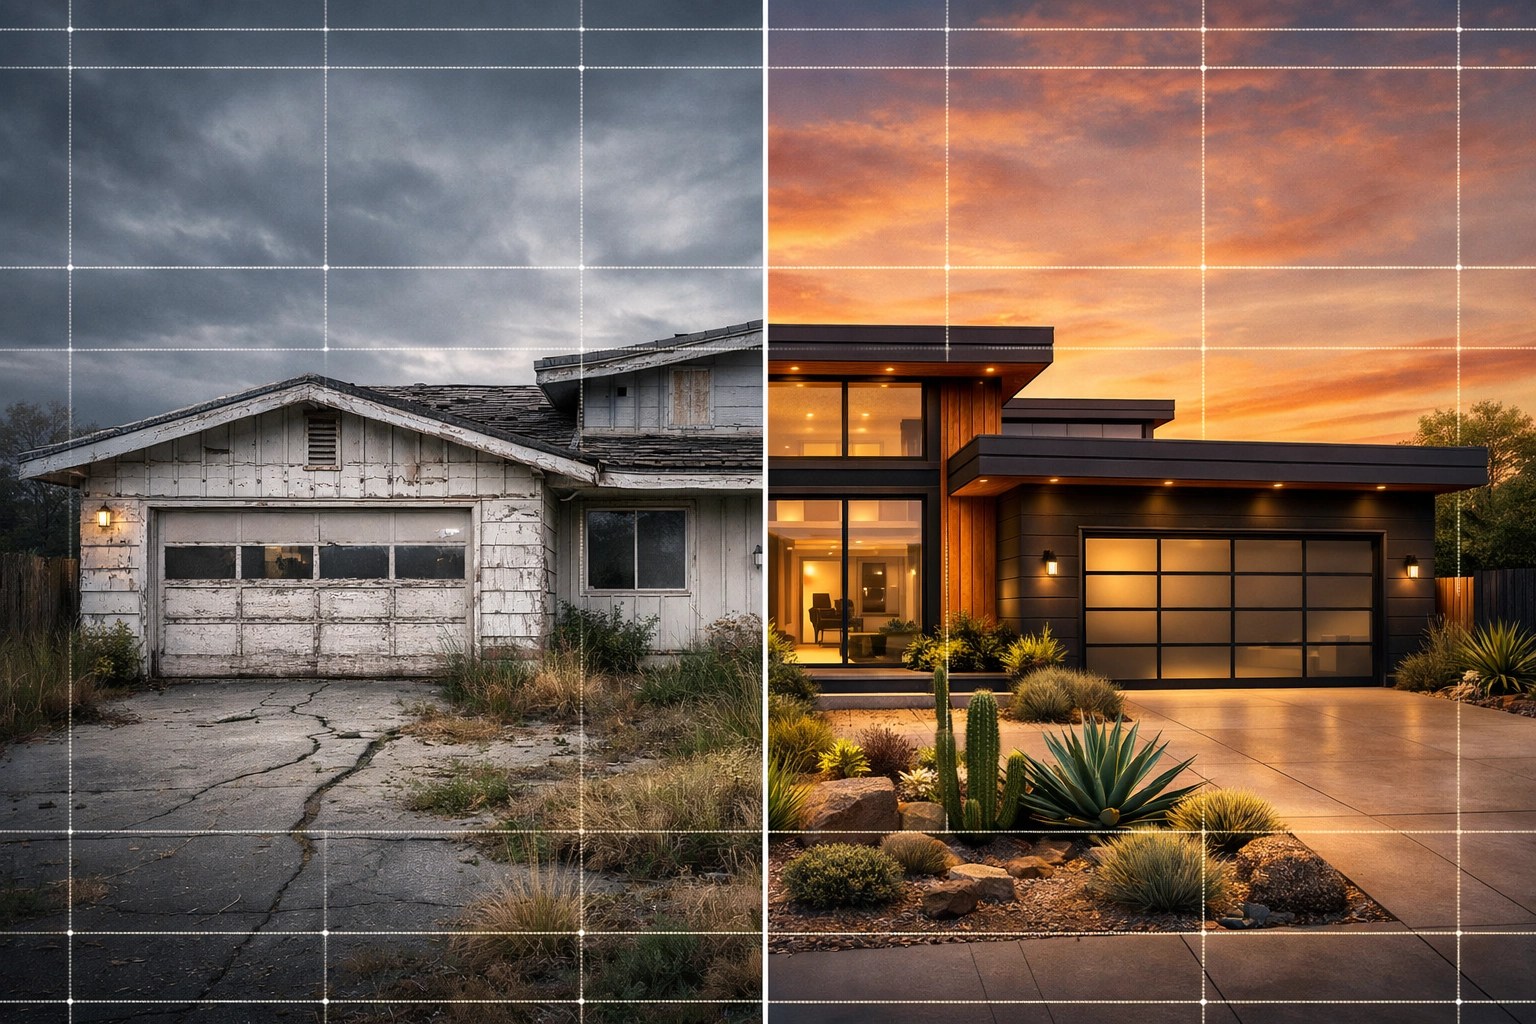
    Split screen showing a dilapidated fixer-upper property next to a modern luxury renovation for real estate investing.

    Categorizing Your Costs: The Big Three

    To build a budget that actually works, you have to stop guessing and start calculating. Professional investors break their budgets down into three distinct buckets: Hard Costs, Soft Costs, and Holding Costs.

    1. Hard Costs (The "Sticks and Bricks")

    These are the most obvious expenses. It’s the labor and the materials.

    • Materials: We’re talking lumber, flooring, paint, cabinets, and those energy-efficient windows that buyers love. Depending on the scope, you might spend anywhere from $5,000 on a light "lipstick" rehab to $20,000+ for a full gut.
    • Labor: Unless you’re doing the work yourself (which we don't usually recommend if you’re trying to scale), labor will be your biggest expense. Budgeting $10,000 to $30,000 for a standard crew is common.

    2. Soft Costs (The Paperwork)

    People always forget these, and they add up fast.

    • Permits and Fees: Depending on your city, permits can range from $500 to $2,000. Don't skip these. Unpermitted work is a nightmare when you try to sell.
    • Architectural/Engineering Plans: If you’re moving walls or adding square footage, you’ll need professional drawings.

    3. Holding Costs (The Silent Profit Killers)

    Every day you own the house and aren't selling it, it’s costing you money.

    • Loan Payments: If you’re using a hard money loan, your interest might be $1,000 to $2,000 a month.
    • Taxes and Insurance: You still have to pay the taxman and keep the property insured while it’s a construction zone.
    • Utilities: You need the lights on and the water running for the crew.

    The Non-Negotiable: The Contingency Fund

    If I’ve learned anything in real estate, it’s that houses have secrets. You rip out a tub and find out the subfloor is rotted. You open a wall and find "creative" 1950s wiring.

    This is why you must have a contingency fund. We recommend reserving 10–20% of your total renovation budget for the unexpected. If your rehab is $50,000, you should have at least $5,000 to $10,000 set aside that you hope you don't use. Treating your contingency fund as a "last resort" rather than extra money for "better cabinets" is what keeps your project in the green.

    MWR @Home Opportunity Promotion

    Prioritizing Your Spend: Where the ROI Lives

    Not all renovations are created equal. If you want to maximize your After-Repair Value, you have to spend money where buyers actually care.

    • Kitchens and Bathrooms: This is where the deal is won. These rooms typically offer ROI rates up to 80%. New cabinets, modern hardware, and clean tiling are non-negotiable.
    • Curb Appeal: First impressions matter. A fresh coat of paint on the front door and some basic landscaping can add thousands to the perceived value for very little cost.
    • Energy Efficiency: In 2026, buyers are savvy. New HVAC systems or energy-efficient windows aren't just "nice to haves": they are major selling points that reduce long-term costs for the buyer.

    Pro-Tip: Don't over-improve! If the neighborhood has laminate countertops, putting in high-end Calacatta marble might feel good, but you won't get that money back. Match the neighborhood standard, then go just 5% better.

    Tracking Everything in Real-Time

    You can't manage what you don't measure. Use a spreadsheet or software like QuickBooks to track every single nail and hour of labor. Compare your actual spending against your budget every single week.

    If a contractor says they need an extra $2,000 for "unforeseen issues," get it in writing. Change orders should always be signed by both parties. Verbal agreements are where budgets go to die.

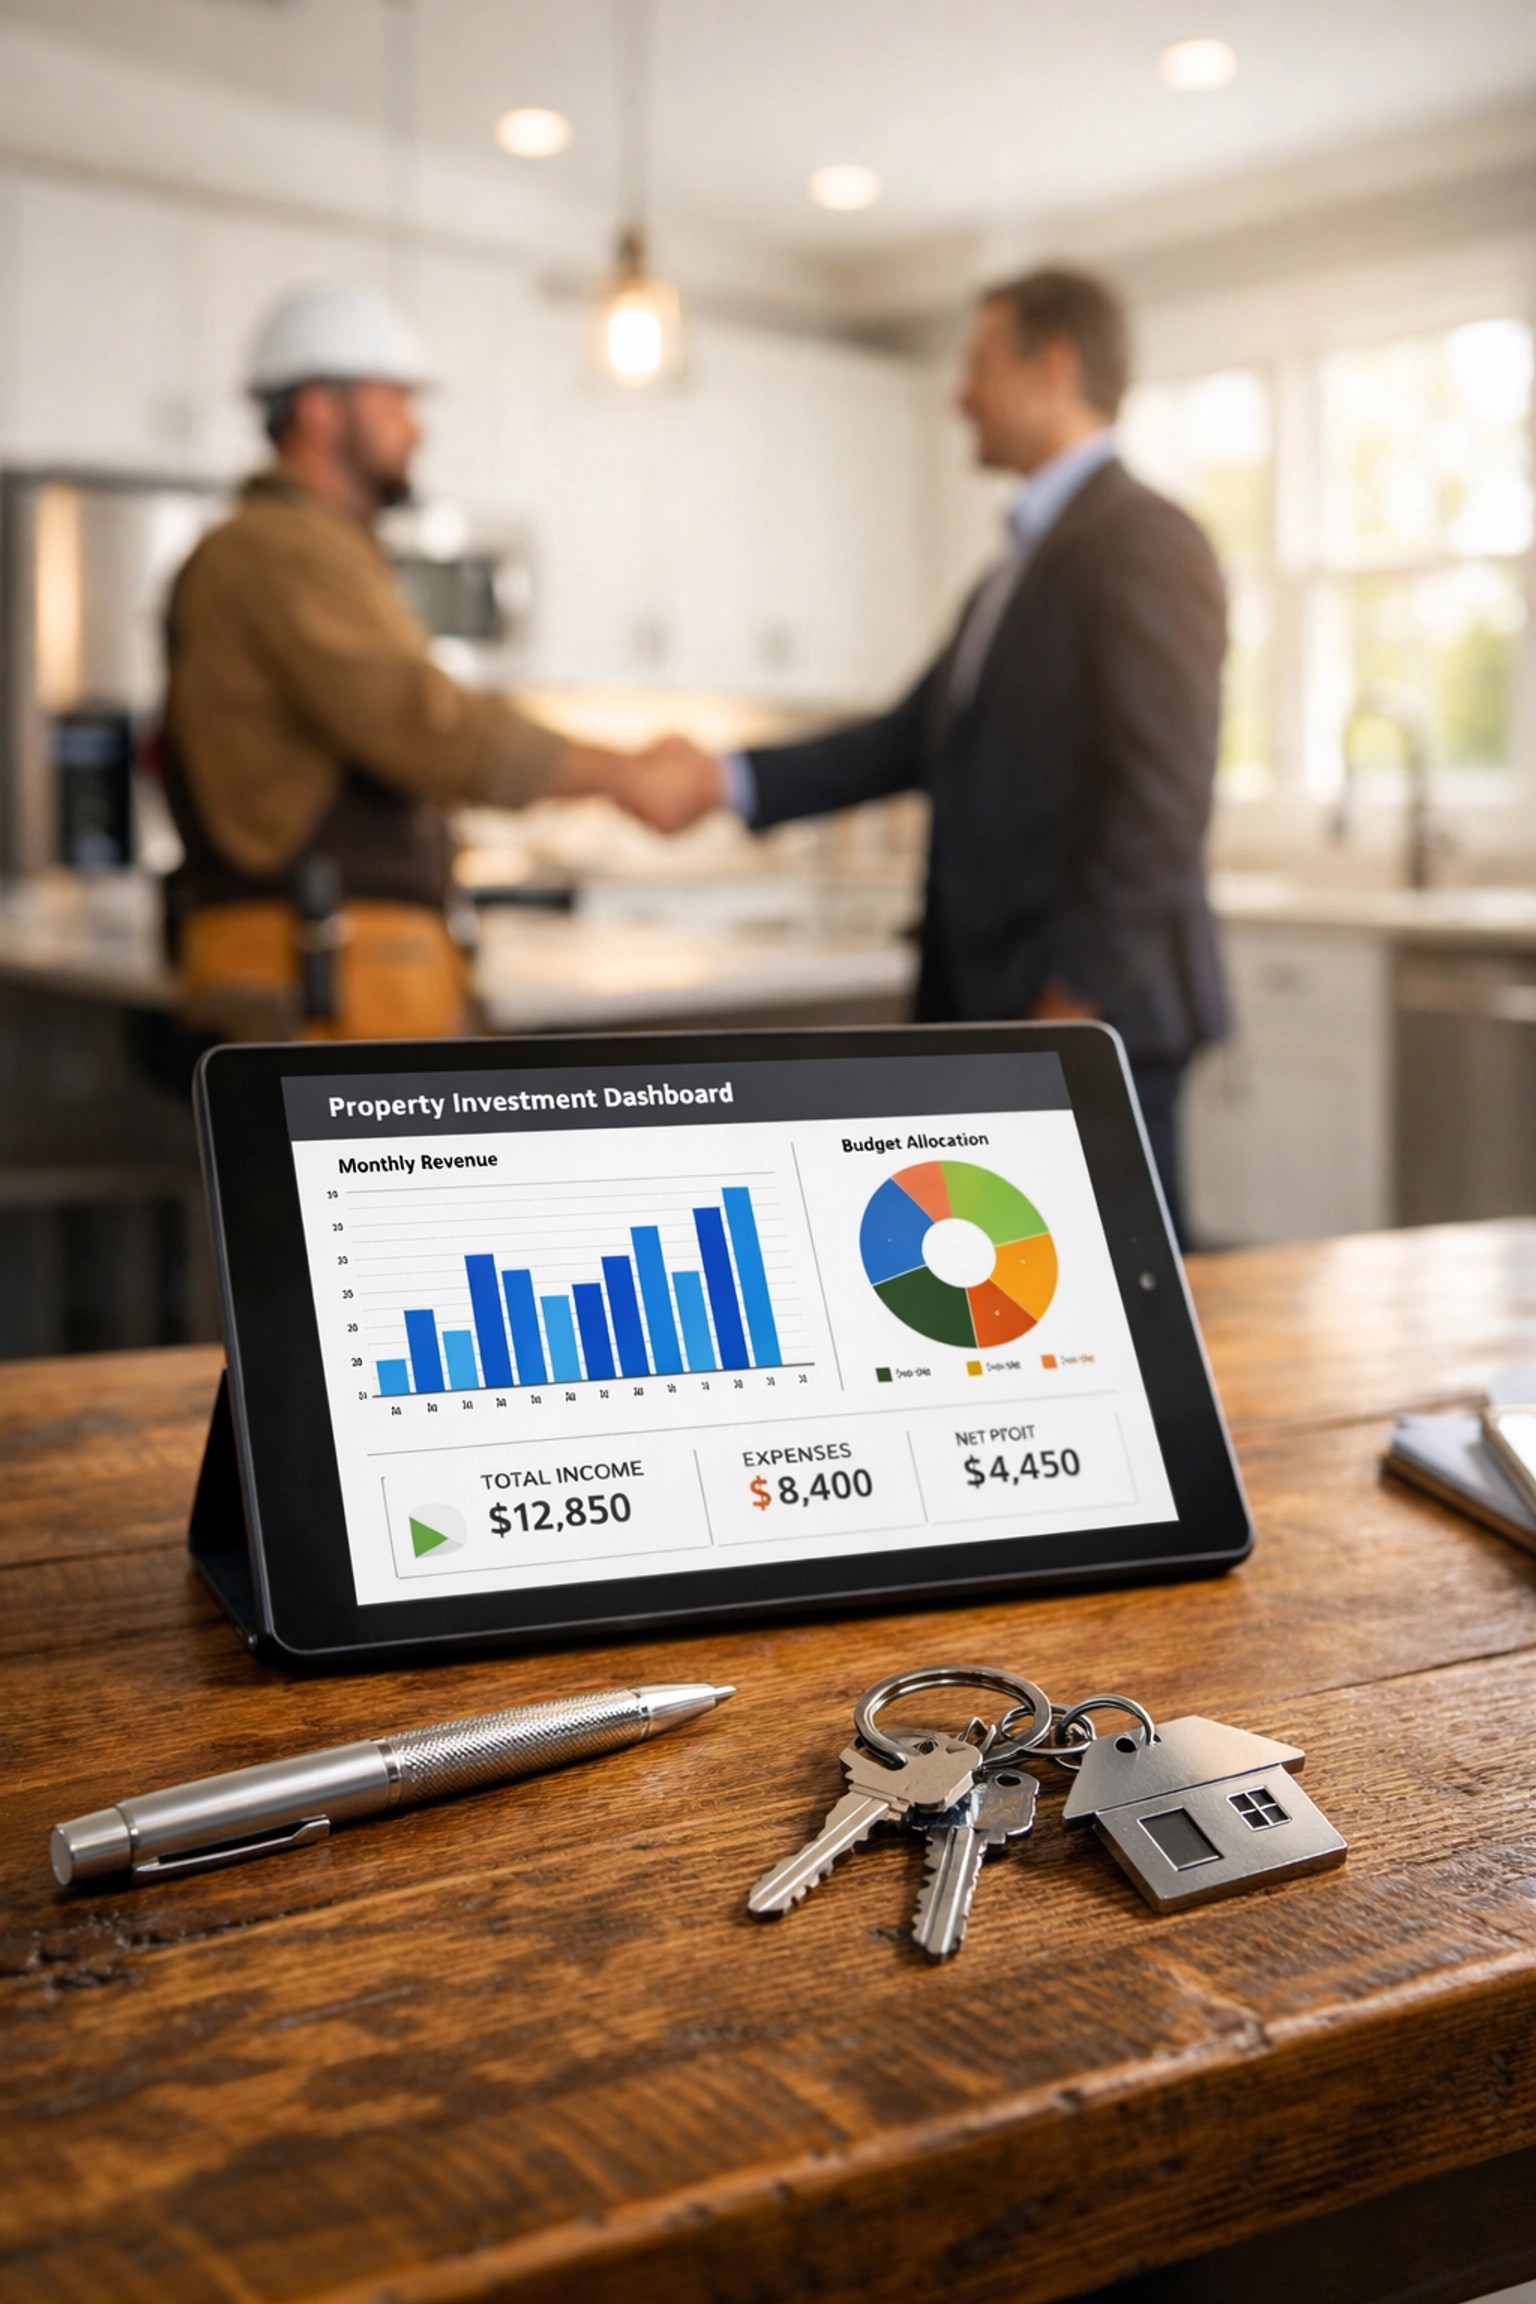
    A financial dashboard on a tablet used for tracking a house rehab budget in a newly renovated kitchen workspace.

    Take the Guesswork Out with Professional Funding Prep

    Budgeting for a rehab is a skill, and it takes time to master. If you’re feeling overwhelmed or you want to make sure your next deal is actually "investor-ready," let’s work together.

    I offer a Paid Funding Preparation Service specifically designed to help you get the capital you need. We don't just "look" at your deal; we dive deep. My package includes:

    • Detailed Deal Analysis: Making sure the numbers actually work.
    • ARV Comps: Professional analysis of what the house will really be worth.
    • Rehab Budgeting: Helping you nail down those hard and soft costs.
    • Loan Submission Packages: We work with Real Brokerage lending partners to get your deal in front of the right people.

    If you’re ready to scale your real estate business without the "guessing game," check out my resources at Millis Property or see how we’re changing the game at Real Brokerage.

    Join the Community

    Wealth isn't just about money; it’s about the people you surround yourself with. We’ve built an incredible community over on Skool where we share daily tips, deal breakdowns, and strategies to help you make wealth real. Whether you’re looking for your first flip or your fiftieth, you don’t have to do it alone. Join us and let’s grow together!


    🏠 The Triple Threat: How Can We Help You Today?

    • FOR SELLERS: Need to offload a property fast? We buy houses in any condition. Let us take the stress off your hands.
    • FOR BUYERS: Looking for your dream home or a turnkey rental? Check out our latest listings and find your next move.
    • FOR INVESTORS: Ready to put your capital to work? Let’s talk about deal flow and how we can partner on the next big win.

    Ready for a full Financial Transformation?
    Real estate is just one piece of the puzzle. To truly protect and multiply your wealth, you need a complete strategy. Join the MWR membership today to start your Financial Makeover. From credit restoration to tax reduction, we give you the tools to win.

    👉 Start Your Financial Transformation Here


    Tweet Draft for Sonny:
    "Stop guessing on your rehab costs! 🏠 Real profit in fix-and-flips is made at the purchase, but kept through a rock-solid budget. From the 70% rule to contingency funds, we’re breaking down how to master the rehab. Check the blog! #RealEstateInvesting #FixAndFlip #MakeWealthReal"

  • The Harford County Outlook: Why This Real Estate Gem is Key to Your 2026 Wealth Strategy

    The Harford County Outlook: Why This Real Estate Gem is Key to Your 2026 Wealth Strategy

    If you’ve been sitting on the sidelines of the Maryland real estate market for the last couple of years, waiting for a sign, consider this your green light. We’ve officially moved through the chaotic "bidding war" era of the early 2020s and landed in a space that is much more favorable for long-term wealth builders.

    While everyone else is looking at the high-priced suburbs of D.C. or the hustle of Baltimore City, savvy investors and families looking for financial relief are turning their eyes toward Harford County. As of March 2026, Harford isn’t just a "nice place to live", it’s a cornerstone for anyone looking to make wealth real.

    At MAKE WEALTH REAL, we believe that true financial freedom comes from a mix of smart cash flow management and strategic asset acquisition. Today, let's dive into why Harford County is the "Goldilocks" zone of Maryland real estate and how you can use it to anchor your legacy.

    The State of the Market: Stability is the New Sexy

    For a long time, people thought "good" real estate meant 15% growth in a single year. But as any seasoned investor will tell you, that kind of volatility is a double-edged sword. In 2026, Harford County has found its rhythm.

    Currently, we are seeing median home prices in the $400,000–$425,000 range. What’s even better? The appreciation is holding steady at about 1.2% to 2% year-over-year.

    Why is this a good thing? Because it signals a "normalized" market. We aren't in a bubble, and we aren't in a crash. We are in a growth phase that is sustainable. For those seeking financial relief from the high cost of living in other Maryland corridors, Harford offers a breather without sacrificing the equity growth that builds wealth over time.

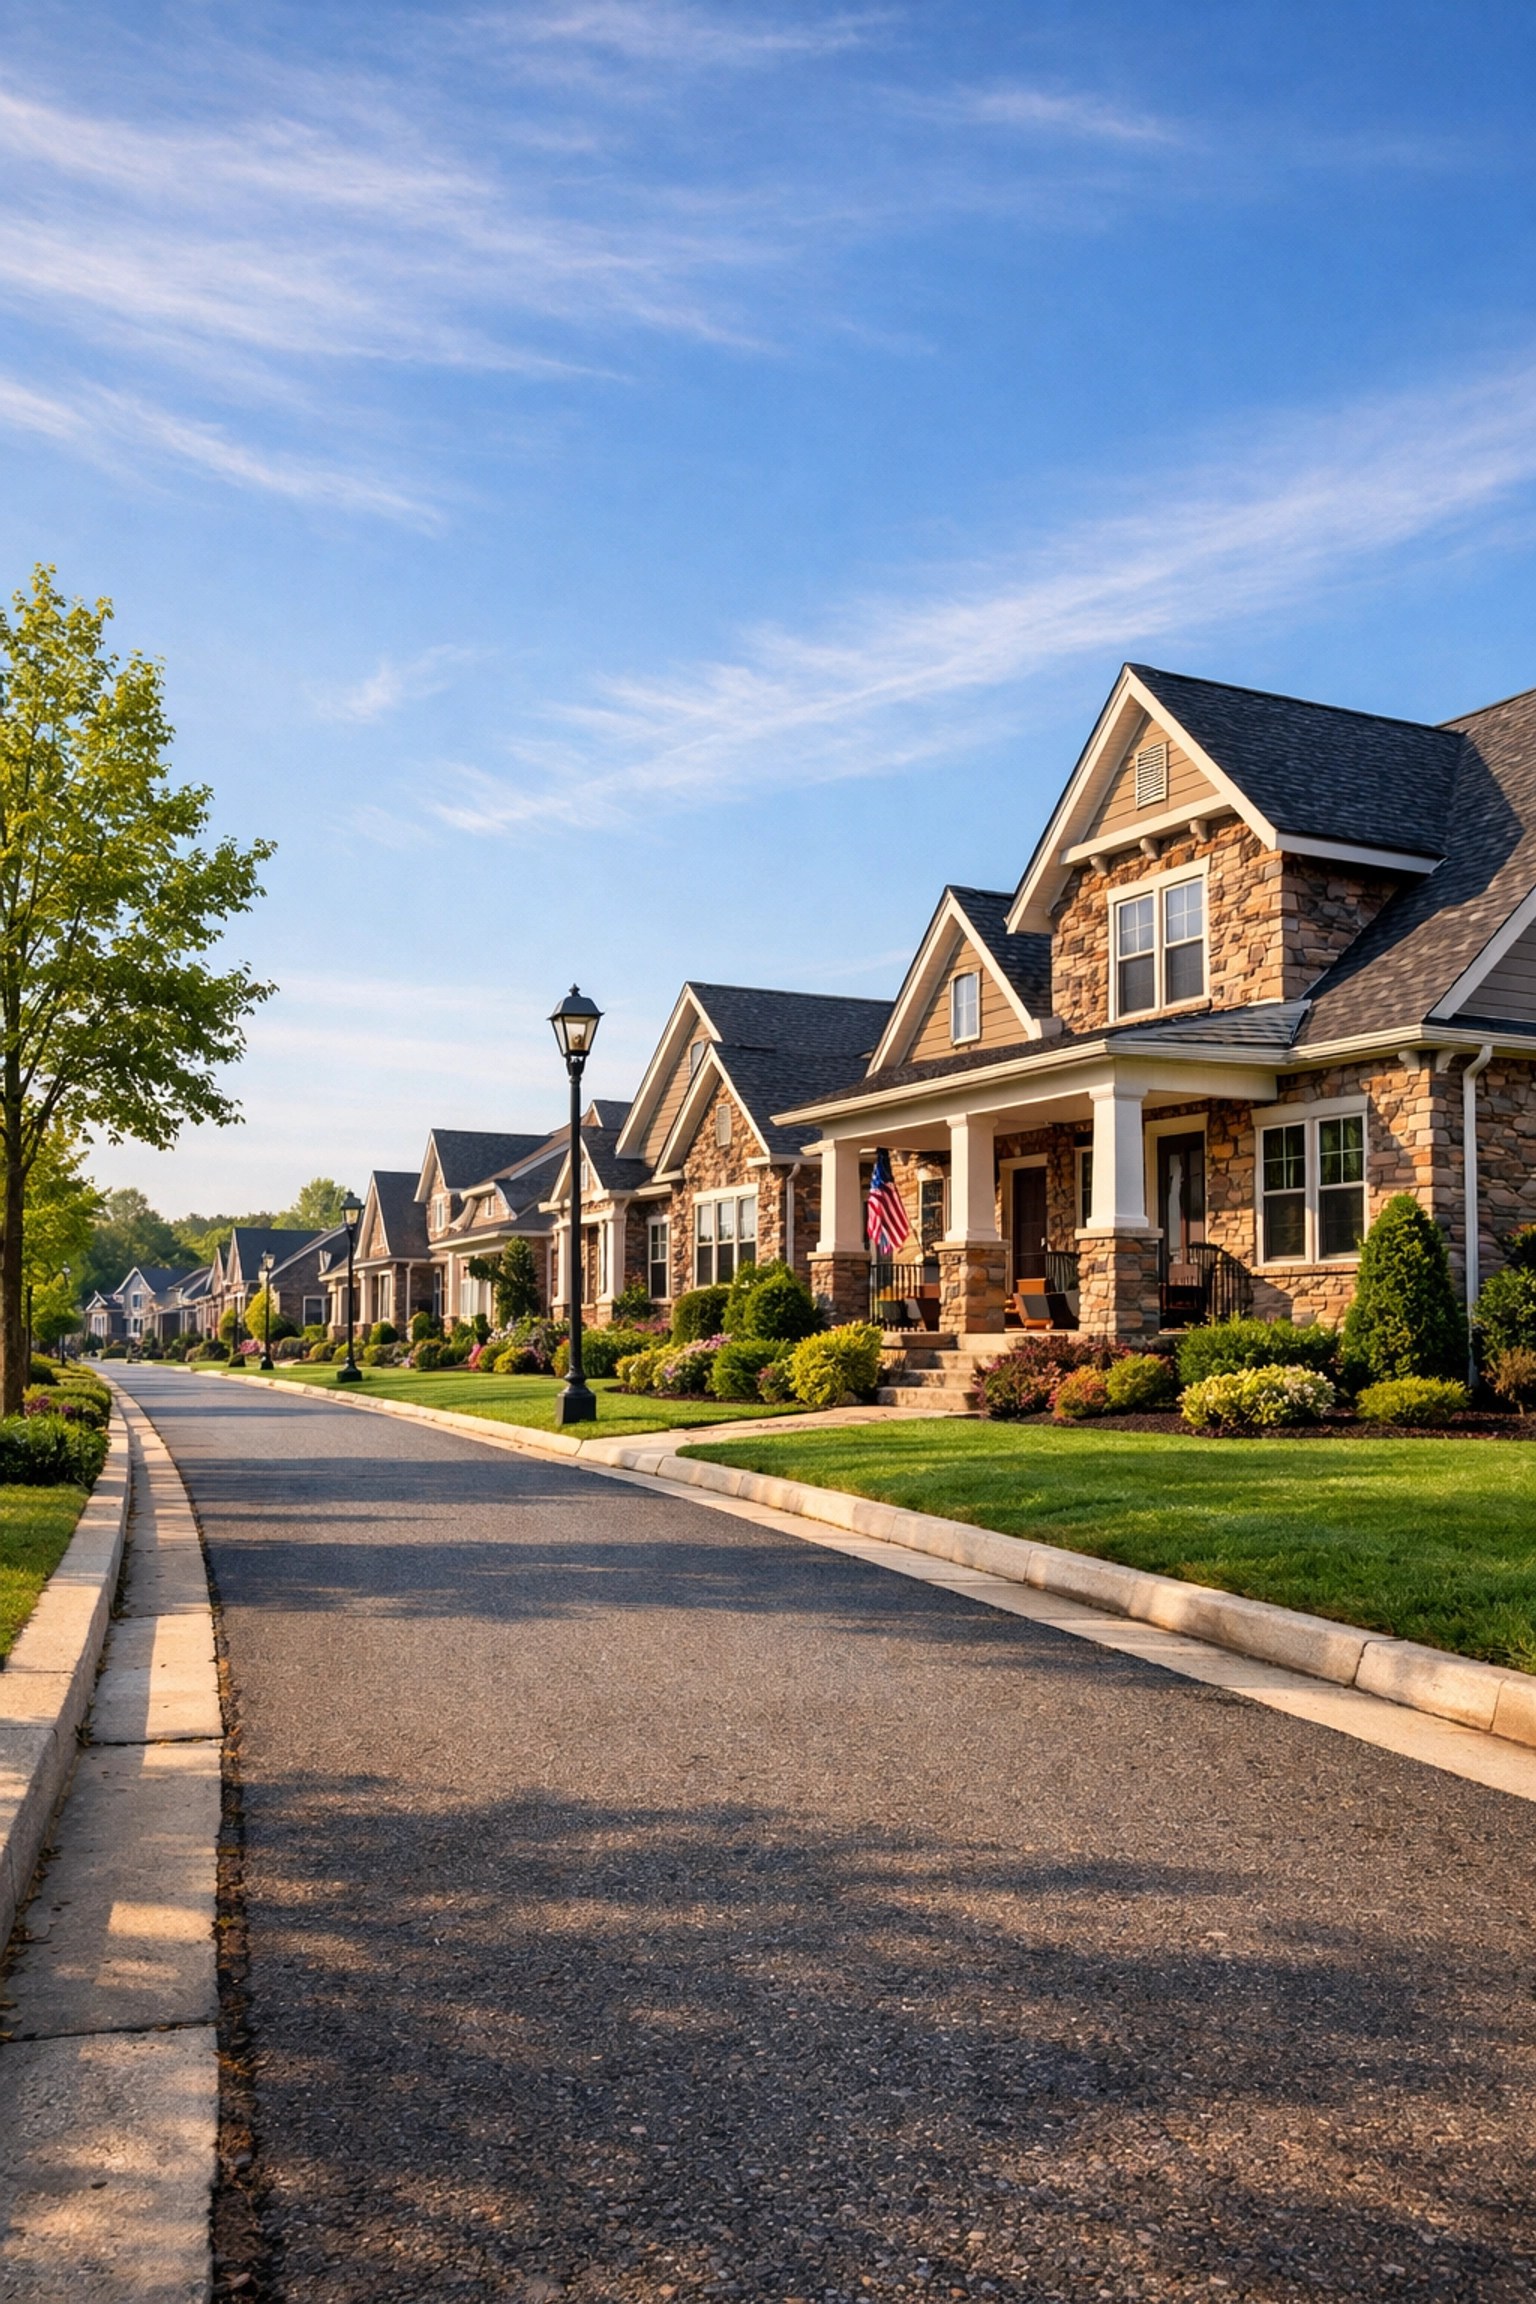
    Modern craftsman homes in Harford County, Maryland showing stable real estate growth for 2026.

    Inventory is Finally Breathing

    One of the biggest hurdles for aspiring investors over the last five years was the lack of inventory. You couldn't buy what wasn't there. In 2024 and 2025, we saw inventory levels hovering around 385 active listings.

    Fast forward to today, March 2026, and we are looking at roughly 585 active listings. We are steadily marching back toward that pre-shortage "sweet spot" of 900 homes.

    For you, this means choice. It means you can actually negotiate. It means you don’t have to waive every inspection and offer $50k over asking just to get a roof over your head. This inventory recovery is a buyer’s advantage that supports healthy, stable equity building.

    The Interest Rate Environment: Planning Your Move

    We know the question on everyone's mind: "What about the rates?"

    As we move through 2026, mortgage rates have settled into the 6% range. While we all miss the 3% rates of the past, we have to look at the bigger picture. The cooling inflation we've experienced is expected to lead to even more favorable conditions later this year.

    A modest decline in rates doesn't just lower your monthly payment; it increases your purchasing power. In a market like Harford County, where demand remains high (homes sell in about 30-35 days), having that extra purchasing power can be the difference between getting a starter home and getting a wealth-generating property.

    Motivational Finance Prompt Graphic

    Why Harford? The Suburban Allure

    Real estate value is driven by "location, location, location," but wealth is driven by "demand, demand, demand."

    Harford County remains a high-demand area because it hits the trifecta of suburban living:

    1. Quality Education: The school systems continue to be a major draw for families.
    2. Space and Quality of Life: You get more square footage and "green" for your dollar here than in Howard or Montgomery County.
    3. Proximity: You’re close enough to Baltimore for work or play, but far enough away to enjoy a quieter, safer environment.

    Whether it’s the historic charm of Havre de Grace, the bustling growth of Bel Air, or the family-friendly vibe of Abingdon, Harford County is insulated from the wild speculation seen in other markets. It’s a "lagging indicator" market, which means it moves conservatively, and for a wealth-building strategy, conservative and predictable beats risky and volatile every single time.

    Integrating Real Estate into Your Wealth Strategy

    At MAKE WEALTH REAL, we don't just talk about buying houses. We talk about Financial Transformation.

    Buying a property in Harford County shouldn't just be about having a place to sleep. It’s about:

    • Asset Leveraging: Using the equity in your home to fund further investments.
    • Tax Advantages: Owning real estate opens up a world of deductions that keep more of your hard-earned money in your pocket.
    • Legacy Building: This is about creating something that lasts beyond your own lifetime.

    However, we know that for many, the hurdle isn't the desire to buy; it's the ability. High debt, low credit scores, or a lack of cash flow can make even a $400k home feel out of reach.

    Strategic financial planning for homeownership and long-term legacy wealth building.

    How MWR Financial Clears the Path

    This is where the MWR Financial membership becomes your greatest ally. We help people bridge the gap between where they are and where they want to be.

    If you’re looking at Harford County and thinking, "I’d love to buy, but my debt is too high," or "My credit score isn't where it needs to be for those 6% rates," we have the tools to help. Our "Financial Makeover" approach focuses on:

    • Credit Restoration: Getting your score into the "Prime" territory so you get the best possible terms on your mortgage.
    • Debt Elimination: Freeing up your monthly cash flow so you can actually afford the home of your dreams.
    • Tax Reduction: Helping you keep more of your paycheck to put toward your down payment.

    When you combine a stable, growing real estate market like Harford County with the financial strategies provided by MWR, you aren't just buying a house, you’re executing a wealth-building masterplan.

    MWR @Home Opportunity Promotion

    The 2026 Outlook: Don't Wait to Buy, Buy and Wait

    The old saying goes, "Don't wait to buy real estate; buy real estate and wait." In Harford County, this couldn't be truer.

    With prices holding steady and inventory rising, 2026 is the year of the strategic buyer. You have the time to find the right property. You have the stability to know your investment is safe. And you have the growth potential to ensure that five or ten years from now, you’ll be looking back at this "gem" of a county as the best financial decision you ever made.

    Wealth isn't just for the "lucky" or the already rich. It’s for the people who see the opportunity in the data and take action. Harford County is showing us the path. Are you ready to walk it?


    Ready to Start Your Financial Transformation?

    If you're ready to stop dreaming about wealth and start building it, we're here to help. Whether you need to fix your credit, lower your taxes, or eliminate debt to get into your next home, the MWR Financial membership is the key to your makeover.

    Here’s your next step: start your Financial Makeover today.
    Lock in your membership, get the expert support, and start building real momentum toward ownership and generational wealth in 2026.

    Start your Financial Makeover now:
    www.mwrfinancial.com/krnrstn21

    To learn more about our programs and how we help people across the country make wealth real, visit our main site at www.mwrfinancial.com.


    Tweet Draft for Sonny:
    "Harford County is the Maryland real estate 'sweet spot' in 2026! 🏡 Stable growth, rising inventory, and 6% rates make it the perfect time to build your legacy. Start your Financial Makeover today: www.mwrfinancial.com/krnrstn21 #HarfordCounty #WealthBuilding #MWRFinancial"

    Sonny, please post this tweet to our social channels to drive traffic to the new blog post!

  • Do You Really Need a Complex Trust? Here’s the Truth About Protecting Your Legacy

    Do You Really Need a Complex Trust? Here’s the Truth About Protecting Your Legacy

    Let’s be real for a second. When most people hear the word "trust," they picture a mahogany-row boardroom, guys in tailored suits, and a family name etched into the side of a skyscraper. There’s this massive myth floating around that trusts: especially "complex" ones: are only for the billionaires of the world.

    But at MAKE WEALTH REAL, we’re all about breaking down those walls. We believe that wealth isn’t just about how much is in your bank account today; it’s about the legacy you’re building for tomorrow. And a huge part of that is making sure your hard-earned assets actually stay with the people you love, rather than getting swallowed up by taxes, probate, or creditors.

    So, the big question: Do you actually need a complex trust? Or are you overcomplicating things? Let’s dive into the truth about protecting your legacy.

    Simple vs. Complex: What’s the Real Difference?

    In the world of estate planning, the terms "simple" and "complex" aren't just descriptions of how many pages the document has. They are specific legal and tax classifications used by the IRS.

    The Simple Trust

    A simple trust is pretty much what it sounds like. It’s designed to be a pass-through. By law, it must distribute all of its annual income to the beneficiaries. It can’t hold onto that money, and it generally can’t distribute the "principal" (the original assets you put in) or give money to charities. Because the income goes straight to the people named in the trust, the tax burden usually follows the person receiving the money.

    The Complex Trust

    A complex trust is the "Swiss Army Knife" of estate planning. It can do everything a simple trust can’t. It can keep (accumulate) income instead of paying it out. It can distribute the principal assets to beneficiaries. It can make charitable donations.

    Because it has more "moving parts," it’s treated as its own legal entity for tax purposes. This means the trust itself might pay taxes on the money it keeps, but it also opens up a massive world of strategy for those looking to protect high-value assets or manage complicated family dynamics.

    Motivational Finance Prompt Graphic

    When Does a Complex Trust Actually Make Sense?

    You don't buy a semi-truck to pick up groceries, and you don't set up a complex trust if a basic will or a simple revocable living trust will do the job. However, there are four specific scenarios where going "complex" is one of the smartest moves you can make.

    1. You Have "Unique" Beneficiary Needs

    Not every beneficiary is ready to handle a lump sum of cash. If you have a child with special needs, a complex trust is essential. It allows the trustee to provide for their lifestyle without disqualifying them from necessary government benefits. Similarly, if you have a family member who struggles with money management (we all have that one cousin, right?), a complex trust lets you "drip-feed" their inheritance over time rather than handing them the keys to the kingdom all at once.

    2. You’re Playing the Long-Term Tax Game

    This is where the "Wealth" in MAKE WEALTH REAL really shines. Complex trusts allow for something called "income shifting." If the trust earns a significant amount of money, you might be able to distribute that income to beneficiaries who are in lower tax brackets, effectively lowering the total amount of money the government takes from your family’s pot.

    3. You’ve Got Serious Assets or Multi-State Property

    If you own a business, multiple rental properties, or assets across different states, things get messy fast. Probate: the legal process of "proving" a will: is a nightmare that eats up time and money. A complex trust can hold these assets, allowing them to pass to your heirs seamlessly without the court getting involved in every single state where you own a piece of dirt.

    4. You Want Bulletproof Asset Protection

    We live in a litigious world. If you’re a business owner or an investor, you’re a target. A properly structured complex trust can act as a shield. Since the trust owns the assets (and not you personally), it’s much harder for a creditor or a frivolous lawsuit to come after your legacy.

    A golden shield protecting a luxury home, symbolizing asset protection and a complex trust securing a family legacy.

    The Trade-Off: It’s Not All Sunshine and Dividends

    I’m going to give it to you straight: Complex trusts come with more "homework."
    Because the trust is its own entity, it needs its own tax ID (EIN) and has to file its own tax returns (Form 1041). The administrative costs are higher because you’ll likely need an accountant and an attorney to make sure you’re staying within the lines.

    If your estate is straightforward and your primary goal is just avoiding probate, a Simple Trust or a Revocable Living Trust is usually your best bet. But if you’re looking to build an empire that lasts for generations, the complexity is the price of admission for the protection you get.

    How to Know What You Need

    You shouldn’t be making these decisions based on a Google search or what your neighbor told you at a BBQ. At MAKE WEALTH REAL, we believe in getting the experts in your corner.

    The first step is always an assessment of your "Financial Makeover" goals. Are you trying to eliminate debt? Are you trying to find safe investments? Or are you at the stage where you need to wrap your arms around what you’ve built and protect it?

    This is exactly why we created the MWR Lifestyle & Legacy Membership. We don't just give you a PDF and wish you luck. We provide the strategies and the access to experts who help you determine if a complex trust is the right tool for your specific legacy.

    S.I.M.P.L.E Leverage Everything Weekly Event

    Take Control of Your Financial Future

    Legacy isn’t an accident; it’s a choice. Whether you need a simple plan to protect your home or a complex structure to protect a multi-million dollar portfolio, the key is to start now.

    Waiting until "someday" is how wealth gets lost. It’s how the government ends up with a bigger cut of your life’s work than your kids do. We want to empower you to take the driver's seat.

    Your Next Steps:

    1. Get Educated: Join our Skool community. It’s where we drop the real gems, share stories, and help you navigate the world of wealth management without the corporate jargon.
    2. Get the Membership: If you’re ready to stop guessing and start growing, the MWR Lifestyle & Legacy Membership is your blueprint. We cover everything from tax reduction and debt elimination to the heavy-hitting asset protection we talked about today.
    3. Audit Your Assets: Take a look at what you own. If you disappeared tomorrow, would your family be protected? If the answer is "I don't know," then it's time to get to work.

    You’ve worked too hard to let your legacy be left to chance. Let’s make wealth real together.

    Ready to start your Financial Makeover?
    Click here to join the MWR Membership and secure your legacy today!

    For more information on our programs and how we can help you shift, increase, and protect your wealth, visit www.mwrfinancial.com.


    Tweet Draft for Sonny:
    Do you really need a "Complex Trust," or are you just overcomplicating your legacy? 🧐 We’re breaking down the simple vs. complex debate in our latest blog. Don't let taxes and probate eat your hard-earned wealth! Read more: http://makewealthreal.com/krnrstn21 #MakeWealthReal #AssetProtection #FinancialFreedom

  • Is Your Money Just Sitting There? The Beginner’s Guide to Diversified Cashflow Accounts

    Is Your Money Just Sitting There? The Beginner’s Guide to Diversified Cashflow Accounts

    Let's be real, most people have money sitting in a checking or savings account earning basically nothing. Maybe 0.5% interest if you're lucky. Meanwhile, inflation is eating away at your purchasing power every single day.

    You work hard for your money. Shouldn't your money work hard for you?

    That's where Diversified Cashflow Accounts (DCAs) come in. And no, this isn't some complicated Wall Street mumbo jumbo. It's actually a strategy designed to put you back in control of your finances while your money grows: safely and predictably.

    Ready to stop leaving money on the table? Join MWR's Financial Transformation Program and discover how diversified cashflow accounts can revolutionize the way you build wealth.

    What Exactly Is a Diversified Cashflow Account?

    Think of a DCA as your personal financial command center. It's a specially structured life insurance policy that creates a reserve of money you control and can access for whatever you need: investments, emergencies, major purchases, business opportunities, you name it.

    Here's the thing most people don't realize: traditional savings accounts are designed to keep your money locked away, earning pennies while the bank uses it to make serious profits. A DCA flips that script entirely.

    Savings growing with diversified cashflow account strategy and upward trending financial charts

    Instead of letting your cash sit idle, you position it to grow tax-free, stay protected from market crashes, and remain accessible when opportunities knock. It's like having your own personal bank: except you're the one collecting the interest.

    How Does It Actually Work?

    The concept is simpler than you think. Remember how building equity in your home works? You make payments, and over time, you build ownership you can borrow against. A DCA operates on a similar principle.

    When you make premium payments into your policy, a substantial chunk goes toward building cash value. This isn't some theoretical number: it's guaranteed, locked-in money that can never decrease. No market crashes. No bad investment decisions. Just steady, predictable growth.

    Here's where it gets powerful: this cash value sits inside a mutually owned life insurance company. That means you: the policy owner: have a stake in the company. There are no outside shareholders taking profits. The company works for its members.

    MWR @Home Opportunity Promotion

    Need to access your money? You take a policy loan collateralized against your cash value. No credit checks. No applications. No one asking what you plan to do with your money. You create your own repayment schedule, giving you complete flexibility in how and when you pay it back.

    The best part? While you're using that borrowed money for investments or whatever else you need, your cash value continues growing as if you never touched it. Your money is literally working in two places at once.

    Want to learn exactly how to set this up for yourself? Start your Financial Makeover with MWR today and get personalized guidance from experts who've helped thousands build real wealth.

    The Real Benefits (No Fluff, Just Facts)

    Let's break down why DCAs are becoming the go-to strategy for people serious about building wealth:

    Control: You own it. You manage it. No bank telling you when or how you can access your funds. It's your money on your terms.

    Guaranteed Growth: Your cash value is contractually guaranteed to grow every single year. While the stock market does its rollercoaster thing, your foundation stays rock solid. Zero losses. Ever.

    Tax Efficiency: Growth happens completely tax-free. Loans are tax-free. And when structured properly, the death benefit passes to your beneficiaries tax-free. The IRS doesn't get a cut.

    Protection: Not only does your policy provide a death benefit for your loved ones, but in most states, your cash value has creditor protection. Lawsuit? Bankruptcy? Your DCA stays protected.

    Liquidity: Unlike retirement accounts that lock your money away until you're 59½ (with penalties for early access), you can tap into your DCA anytime, for any reason, without penalties.

    Leverage: This is the game-changer. You can use policy loans to invest in real estate, start a business, or seize opportunities while your cash value continues earning guaranteed growth. Your money works twice as hard.

    Money leverage comparison showing idle cash versus diversified cashflow streams and investments

    Motivational Finance Prompt Graphic

    Who Should Consider a Diversified Cashflow Account?

    Honestly? Almost anyone who's tired of watching their money do nothing.

    But DCAs are especially powerful if you:

    • Have money sitting in savings earning practically zero interest
    • Want to invest but don't want to risk everything in the market
    • Are building a business and need flexible access to capital
    • Want tax-free growth without the restrictions of traditional retirement accounts
    • Are looking for ways to create multiple income streams
    • Need protection for your family while building wealth for yourself
    • Want to be your own bank instead of making lenders rich

    If you're nodding along thinking "that's me," then a DCA deserves serious consideration.

    The beauty is that you don't need to be wealthy to start. You just need to be intentional about making your money work as hard as you do.

    Getting Started: The Path Forward

    Here's the truth: understanding DCAs intellectually is one thing. Actually implementing them correctly is another.

    The structure matters. The policy design matters. The company you choose matters. Get it wrong, and you end up with an expensive life insurance policy that doesn't deliver the benefits we're talking about.

    Get it right, and you've created a financial foundation that compounds wealth for decades while giving you control and flexibility most people only dream about.

    This is where working with experts who specialize in DCAs becomes crucial. At MAKE WEALTH REAL, we've helped thousands of members structure diversified cashflow accounts that actually deliver results. We're not selling policies: we're building wealth strategies.

    Financial protection shield with diversified wealth-building assets and family security symbols

    Our Financial Transformation Program walks you through:

    • Determining if a DCA is right for your specific situation
    • Structuring your policy for maximum cash value and minimum fees
    • Understanding exactly how to use policy loans strategically
    • Integrating your DCA into a broader wealth-building plan
    • Accessing tax deductions you didn't know existed (over 470 of them)
    • Creating multiple income streams that put money in your pocket daily, weekly, and monthly

    Plus, you get ongoing education through events like our S.I.M.P.L.E. Leverage Everything! weekly sessions where we dive deep into shifting, increasing, multiplying, protecting, and leveraging your wealth.

    S.I.M.P.L.E Leverage Everything! Weekly Event Promotional Graphic

    Your Money Deserves Better

    Look, your money is either working for you or working for someone else. There's no neutral position. Every day your cash sits in a traditional bank account, you're funding their profits while watching inflation chip away at your purchasing power.

    Diversified cashflow accounts offer something different: a proven strategy that puts you in the driver's seat, protects your wealth, and creates opportunities that traditional savings and investing simply can't match.

    Is it the right move for everyone? Maybe not. But if you're serious about building real wealth, maintaining control, and creating financial security for yourself and your family, it deserves a serious look.

    The question isn't whether you can afford to start a DCA. The real question is: can you afford not to?

    Start Your Financial Makeover Today (Strong CTA)

    If you’re ready to stop playing defense with your money and start building real, protected, predictable wealth, your next step is simple:

    Start your Financial Makeover with MAKE WEALTH REAL today: www.mwrfinancial.com/krnrstn21

    Get plugged into the membership, get expert guidance, and put a real plan in motion: so your money can finally start working like it’s supposed to.


    Tweet Draft for Sonny:

    Your money is either working FOR you or working for someone else. Diversified Cashflow Accounts let you be your own bank: tax-free growth, guaranteed protection, complete control. Ready to stop leaving money on the table? 💰 Learn how: www.mwrfinancial.com/krnrstn21 #WealthBuilding #FinancialFreedom

  • Looking For Your First Investment Property? 10 Things to Know Before Buying in 2026

    Looking For Your First Investment Property? 10 Things to Know Before Buying in 2026

    So, you’ve decided that 2026 is the year you finally stop watching from the sidelines and start building real equity. Smart move. Real estate has always been one of the most reliable paths to wealth, but let’s be honest: the game has changed a bit over the last few years.

    At MAKE WEALTH REAL, we’re all about empowerment through education and action. You don’t need a suit and tie or a million-dollar inheritance to get started, but you do need a strategy. Buying your first investment property isn't just about picking a house with a "For Sale" sign; it’s about understanding the math, the market, and the long-term vision.

    Before you start scrolling through Zillow at 2 AM, let’s break down the 10 essential things you need to know before pulling the trigger on your first deal this year.


    1. Prepare Adequate Capital Before You Start

    Cash is still king, but in 2026, "liquidity" is the queen that keeps the king in check. You need to be adequately capitalized. This doesn't just mean having the down payment; it means having a "peace of mind" fund.

    Between closing costs, professional inspections, and those "surprise" renovations that always seem to pop up the week after closing, you want to make sure you aren't draining your bank account to zero. A good rule of thumb? Have your acquisition costs plus at least six months of carrying costs tucked away.

    2. Understand the Down Payment Requirements

    For your primary residence, you might have gotten away with 3% or 3.5% down. For an investment property? Lenders are looking for a bit more skin in the game. Typically, you’re looking at 15-20% of the purchase price.

    If you’re eyeing a $300,000 duplex, that’s $45,000 to $60,000 upfront. If that number makes your stomach drop, don’t panic. There are alternatives like seller financing or FHA "house hacking" (buying a small multi-family, living in one unit, and renting the others) that can lower that barrier to entry.

    Keys to a modern suburban duplex, a perfect starter multi-family investment property for 2026.

    3. Get Your Credit in Order

    In 2026, your FICO score is more than just a number: it’s a profit margin. The difference between a "good" score and an "excellent" score can mean thousands of dollars in interest saved over the life of the loan.

    Before you even talk to a Realtor, check your reports. Pay down those revolving balances and, for the love of all things holy, do not buy a new car or open a new line of credit right before you apply for a mortgage. Keep your profile clean and your debt-to-income ratio low.

    4. Talk to Lenders Early

    Don't be the person who finds the perfect house and then realizes they can't afford it. Consult with lenders early. You need to understand your borrowing power in the current 2026 landscape. Mortgage options have evolved, and different lenders have different appetites for first-time investors.

    Knowing your budget allows you to move with confidence. In a competitive market, confidence wins deals.

    5. Know the 2026 Interest Rate Landscape

    We aren’t in the era of 3% rates anymore, and that’s okay. As of early 2026, mortgage rates are hovering in the low 6% range. While that might seem high to someone who started looking five years ago, it’s actually quite reasonable in the grand scheme of real estate history.

    The key is to focus on the numbers. If the deal makes sense at 6.5%, it’s a good deal. If it only "works" if rates are 4%, walk away.

    S.I.M.P.L.E Leverage Everything!

    6. Single-Family vs. Small Multi-Family

    For your first rodeo, we usually recommend staying in the "Single-Family or Small Multi-Family" lane (1-4 units). Why? They are easier to finance, easier to manage, and easier to sell if you ever need to pivot.

    A duplex or triplex is the ultimate "cheat code" for first-timers because the rental income from the other units can help offset your mortgage, making it much easier to scale to larger properties later on.

    7. Focus Exclusively on Cash Flow Positive Properties

    Repeat after me: We do not buy for appreciation alone. Appreciation is the cherry on top; cash flow is the actual sundae. Your monthly rental income must exceed your monthly expenses (mortgage, taxes, insurance, maintenance, and vacancy).

    If a property just "breaks even," you aren't an investor; you’re a volunteer property manager. At MAKE WEALTH REAL, we want you to build wealth, not just a collection of bills. Use our tools at http://makewealthreal.com/krnrstn21 to ensure your personal finances are strong enough to support your investment journey.

    8. Select the Right Real Estate Market

    Location is everything, but it’s not just about "nice neighborhoods." It’s about inventory levels, job growth, and local laws. Research where people are moving in 2026. Look for areas where the "Rent-to-Price" ratio actually makes sense.

    Sometimes the best investment isn't in your backyard: it’s three towns over or even out of state.

    Digital map showing data-driven real estate market trends and opportunity zones for investors in 2026.

    9. Get a Fully Underwritten Pre-Approval

    A standard pre-approval letter is just a "maybe." A fully underwritten pre-approval is as close to a "yes" as you can get without a signed contract. It shows sellers you’ve already gone through the ringer with your bank, submitted your pay stubs, and verified your assets. In a multiple-offer situation, this is your secret weapon.

    10. Factor in the "Hidden" Costs

    Don’t let the "hidden" costs eat your lunch. Beyond the mortgage, you need to account for:

    • Property Taxes: These can jump after a sale.
    • Insurance: Especially in areas prone to climate-related issues.
    • Maintenance CapEx: The roof will eventually leak. The water heater will eventually die.
    • Property Management: Even if you manage it yourself now, budget for a pro so the numbers still work when you want to step back.

    How Lamont Milbourne Can Get You "Investor Ready"

    One of the biggest hurdles for first-time investors is the paperwork and the analysis. You might find a house, but do you know if it’s a deal?

    This is where Lamont Milbourne’s paid funding preparation service comes in. If you're serious about taking action, you shouldn't go it alone. Lamont provides a comprehensive package to make you the most attractive borrower in the room:

    • Professional Deal Analysis: We crunch the numbers so you don't have to.
    • ARV Comps: Real data on what the property will be worth after it’s fixed up.
    • Detailed Rehab Budgets: No more guessing what a kitchen remodel costs.
    • Loan Submission Packages: We package your deal for our Real Brokerage lending partners, ensuring you get the best terms possible.

    Ready to see what we’re working on? Check out Millis Property and see how we’re making moves at The Real Brokerage.

    Motivational Finance Prompt

    Join the Community

    Success in real estate is a team sport. If you’re looking for more tips, deep dives into deal analysis, and a community of like-minded investors who are actually doing the work, you need to be in our Skool community. It’s where we share the "under the hood" secrets that don't make it to the main feed.

    The Triple Threat: Are You Ready?

    • SELLERS: If you have a property that’s more of a headache than an asset, let’s talk. We buy houses and can help you exit gracefully.
    • BUYERS: Looking for your dream home or your first rental? Let us guide you through the 2026 market with data-driven precision.
    • INVESTORS: If you have the capital but not the time (or vice versa), let’s partner up.

    Wealth isn't just about what you make; it’s about what you keep and how you grow it. Start your Financial Transformation today by joining the MWR membership. Get the experts on your side to fix your credit, reduce your taxes, and eliminate your debt so you have more capital to pour into real estate.

    Join the movement here: www.mwrfinancial.com/krnrstn21


    Tweet Draft for Sonny:
    Ready to stop dreaming and start owning? 🏠 Real estate in 2026 is all about strategy. From cash flow secrets to underwritten approvals, here are 10 things every first-time investor NEEDS to know. Check out the full breakdown on the MAKE WEALTH REAL blog! #RealEstateInvesting #WealthBuilding #MWRFinancial #2026HousingMarket

  • Coastline and Capital: Why Anne Arundel County is the 2026 Stability Anchor for MD Real Estate

    Coastline and Capital: Why Anne Arundel County is the 2026 Stability Anchor for MD Real Estate

    If you’ve been keeping a pulse on the Maryland real estate market, you know that the last few years have been a bit of a rollercoaster. We’ve seen bidding wars that felt like gladiatorial combat and interest rates that made even the most seasoned investors break a sweat. But as we settle into March 2026, there is one place that is standing out as the "calm in the storm": Anne Arundel County.

    Commonly known as the "Land of Pleasant Living," this county isn't just about the scenic views of the Chesapeake Bay or the historic charm of Annapolis anymore. It has officially become the stability anchor for the entire state’s housing market. While other areas are seeing wild fluctuations, Anne Arundel is offering something far more valuable to the savvy investor and the growing family alike: predictability.

    Let’s dive into why the "Coastline and Capital" is the place to be right now, and more importantly, how you can position yourself financially to take advantage of it.

    The 2026 Shift: By the Numbers

    For a long time, buyers were priced out or simply exhausted. But the data from February and early March 2026 shows a massive shift in favor of those who have their financial house in order.

    Currently, the median listing price in Anne Arundel County is hovering around $524,000. Now, I know what you’re thinking, that’s not "cheap." But here’s the kicker: we are seeing a slight cooling trend from the aggressive peaks of late 2025. This isn't a "crash"; it’s a normalization. It’s the market taking a deep breath.

    What does this mean for you? It means better entry points. We are seeing active listings hit around 735 units, which is a significant 32% increase compared to this time last year. More inventory means you aren't fighting fifty other people for a three-bedroom ranch in Pasadena. You actually have time to do an inspection, think about the layout, and negotiate.

    Suburban homes and real estate for sale in an Anne Arundel County neighborhood near the Chesapeake Bay.

    Why Anne Arundel is the "Stability Anchor"

    So, why is this county holding steady while others are wavering? It comes down to the "Three Pillars" of the Anne Arundel economy:

    1. The Government and Defense Engine

    With the NSA and Fort Meade located right in the county, plus the proximity to D.C. and the State Capitol in Annapolis, there is a built-in "floor" for housing demand. These are recession-proof jobs. When the private sector gets shaky, the government sector stays consistent. This creates a permanent pool of qualified buyers and renters.

    2. Geographic Desirability

    You’ve got the waterfront lifestyle of the Bay, the suburban comfort of Severna Park, and the urban-adjacent accessibility of Glen Burnie and Linthicum. You can work in D.C. or Baltimore and live where people go on vacation. That kind of geographic flexibility is rare, and in a world where hybrid work is the norm in 2026, it’s a gold mine.

    3. Improving Affordability

    With mortgage rates stabilizing around 6.16%, the "sticker shock" of 2024 and 2025 has worn off. Combined with the cooling prices, the "price-to-income" ratio in Anne Arundel is looking much healthier than it was eighteen months ago. Buyers are coming back to the table, but they are doing so with more leverage than they’ve had in years.

    Spotlighting the Value Zones

    If you’re looking to get the most bang for your buck, you have to know where to look. Not every zip code is created equal.

    • Pasadena: Often overlooked in favor of its "fancy" neighbor Severna Park, Pasadena is seeing strong 2026 growth. It offers that coastal lifestyle at a fraction of the Annapolis price tag.
    • Severna Park: This remains the gold standard for long-term appreciation. If you can find a way to enter this submarket during the current "cooling" period, your future self will thank you.
    • Dundalk/Glen Burnie Borders: For the entry-level investor, the borders of these areas are providing excellent rental yields as the workforce looks for manageable commutes.

    Motivational Finance Prompt Graphic

    The Real Secret: It’s Not Just the Market, It’s Your Money

    Here is the truth that most real estate agents won't tell you: A "good market" doesn't matter if your personal finances are a mess.

    At MAKE WEALTH REAL, we talk to people every day who want to buy into places like Anne Arundel County but feel stuck. They see a $524k median price and think, "I'll never get there." But the problem usually isn't the house price, it's the leakage in their current lifestyle.

    To win in the 2026 real estate market, you need a strategy that goes beyond just saving pennies. You need what we call a Financial Transformation.

    Imagine trying to buy a home in Annapolis while you're still carrying high-interest credit card debt or losing 30% of your income to taxes you shouldn't be paying. You're trying to win a race with a parachute tied to your back.

    How MWR Helps You Anchor Your Own Wealth

    If Anne Arundel is the anchor for Maryland, our membership is the anchor for your bank account. To buy property in today’s environment, you need:

    1. Cash Flow Management: Shifting your taxes so you keep more of your paycheck now to put toward that down payment.
    2. Debt Elimination: Getting rid of the high-interest anchors that are killing your debt-to-income ratio (DTI).
    3. Credit Restoration: Ensuring you get that 6.16% rate (or lower) instead of being penalized with a sub-prime rate because of a few old mistakes.

    Financial planning desk with home blueprints and growth charts overlooking the historic Annapolis harbor.

    Making the Move in 2026

    The "Stability Anchor" of Anne Arundel County isn't going to stay this quiet forever. Markets move in cycles, and right now, we are in the "Sweet Spot." The inventory is up, the crazy bidding wars are down, and the prices are realistic.

    However, "realistic" still requires a plan. You don't just "stumble" into a half-million-dollar property and build a legacy. You engineer it. You use tools like the ones we provide at MAKE WEALTH REAL to ensure that when you sign that mortgage, it’s a blessing, not a burden.

    Stop waiting for the "perfect" time to buy. The perfect time is when you have the perfect financial foundation. Anne Arundel is ready for you, are you ready for it?

    S.I.M.P.L.E Leverage Everything!

    Your Path to Financial Transformation

    The real estate market in Maryland is moving, and Anne Arundel County is leading the way with stability and growth. But don't just be a spectator. It’s time to take control of your financial narrative.

    Whether you're looking to buy your first home, move up to the coastline, or start an investment portfolio, the journey starts with a Financial Makeover.

    Join the MWR membership today and start your Financial Transformation. Let us help you shift your taxes, eliminate your debt, and build the credit you need to dominate the 2026 real estate market.

    Ready to build wealth for real?
    Stop watching other people win—start your financial makeover today. Join the MWR membership and let us do the heavy lifting (tax strategies, debt elimination, credit restoration, and funding guidance) so you can move with confidence in this market.

    Start your Financial Makeover now: www.mwrfinancial.com/krnrstn21
    Click here to get started: www.mwrfinancial.com/krnrstn21

    For more information on our programs, visit www.mwrfinancial.com.

    📅 Book a call: https://calendly.com/cornerstoneestatellc/30min?month=2026-03 | 📞 Call/Text: 410-497-7152


    Sonny, here is the tweet for this post. Please get this into the rotation ASAP!

    "Anne Arundel County is the 'Stability Anchor' of 2026! ⚓ With inventory up 32% and prices normalizing, now is the time to plan your move. But a great market requires great finances. Check out our latest blog on why AA County is the place to be! #MarylandRealEstate #MWR #WealthBuilding #AnneArundel"

  • Debt Consolidation vs. Debt Avalanche: Which Is Better For Your Wallet?

    Debt Consolidation vs. Debt Avalanche: Which Is Better For Your Wallet?

    Let’s be real for a second: debt feels like carrying a backpack full of bricks while trying to run a marathon. Every time you think you’re picking up speed, a high-interest credit card bill or a personal loan payment yanks you right back. At MAKE WEALTH REAL, we talk to people every day who are tired of just "getting by." They want to thrive. They want to build a legacy. But you can’t build a skyscraper on a foundation of quicksand.

    To get your financial house in order, you need a strategy. You’ve probably heard the buzzwords: Debt Consolidation and Debt Avalanche. Both sound fancy, and both promise to help you escape the debt trap. But which one is actually better for your wallet?

    Today, we’re breaking down the pros, the cons, and the cold, hard math. By the end of this post, you’ll know exactly which path leads to your financial freedom.

    The Debt Avalanche: For the Math Nerds and Interest-Haters

    If you’re the type of person who looks at your credit card statement and gets physically ill seeing how much goes toward interest, the Debt Avalanche is your best friend.

    The strategy is simple but disciplined:

    1. List all your debts.
    2. Rank them by interest rate (highest to lowest).
    3. Pay the minimum on everything except the debt with the highest interest rate.
    4. Throw every extra cent you have at that top debt.
    5. Once it’s gone, move all that money to the next highest interest rate.

    Why Your Wallet Loves the Avalanche

    The Avalanche is mathematically the most efficient way to get out of debt. Period. By attacking the highest interest rates first, you are effectively "firing" the banks that are charging you the most to use your own money.

    Research shows that the debt avalanche method generally saves more money on interest over time than consolidation, especially if your debts have wildly different rates. For example, if you have an extra $100 a month to put toward your debt, the avalanche method could save you nearly $12,000 in interest over the life of your loans. It can also shave years off your timeline: dropping a 12-year repayment plan down to 9 years.

    The Downside

    The Avalanche requires a iron will. Because your highest-interest debt might also be your largest balance, it can take months (or even a year) before you see a "win" by completely paying off a card. If you’re the type of person who needs quick psychological victories to stay motivated, this might feel like a long, lonely road.

    Motivational Finance Prompt Graphic

    Debt Consolidation: The Great Simplifier

    Debt consolidation is like taking all those annoying little fires and putting them into one controlled fireplace. You take out a new loan (or use a balance transfer card) to pay off all your smaller, high-interest debts. Now, instead of five due dates and five different interest rates, you have one payment and one rate.

    Why Your Wallet Might Like Consolidation

    1. Simplified Management: No more missed deadlines or late fees because you forgot which card was due on the 15th.
    2. Lower Interest (Hopefully): If your credit score is decent, you can often secure a consolidation loan with a lower interest rate than your average credit card (which can hover around 20-29%).
    3. Fixed End Date: Most consolidation loans are "term loans," meaning you know exactly when you will be debt-free (e.g., in 3 or 5 years).

    The "Catch" with Consolidation

    Consolidation isn't a magic wand; it’s a tool. If you consolidate your debt but don’t change the spending habits that got you there, you’ll end up with a consolidation loan and new balances on your empty credit cards. Also, consolidation often extends your repayment period. While the monthly payment is lower, you might actually end up paying more in interest over time if you aren't careful.

    Comparison of debt avalanche and debt consolidation methods for effective interest savings and debt relief.

    Head-to-Head: Which One Wins?

    The choice between Avalanche and Consolidation usually comes down to two things: your credit score and your behavioral style.

    Choose the Avalanche Method if:

    • You have debts with significantly different interest rates (e.g., one card at 29% and another at 12%).
    • You are disciplined and don't need a "quick win" to keep going.
    • You want to maximize every single penny of long-term savings.

    Choose Consolidation if:

    • You can actually qualify for a significantly lower interest rate.
    • Managing multiple payments is causing you stress, late fees, or mistakes.
    • You need the psychological relief of a simplified "one-and-done" payment.

    The critical factor for your wallet is the interest rate differential. If you can’t get a consolidation loan rate that is lower than your current average, you’re just moving deck chairs on the Titanic. In that case, the Avalanche wins every time.

    How MAKE WEALTH REAL Levels the Playing Field

    At MAKE WEALTH REAL, we believe you shouldn't have to choose between "math" and "sanity." Our Lifestyle & Legacy Membership is designed to give you the tools to execute these strategies without the guesswork.

    We don't just tell you to pay off your debt; we show you how to find the money already hidden in your budget to do it. Through our Millionaire Maker software and Debt Elimination systems, we help our members automate the process. Whether you’re leaning toward an avalanche approach or a consolidated structure, our experts help you optimize your cash flow so you’re paying off debt with "found money": money saved from taxes, lowered bills, and eliminated interest.

    S.I.M.P.L.E Leverage Everything!

    Shifting Your Mindset: From Debtor to Wealth Builder

    The biggest mistake people make is thinking that "being debt-free" is the end goal. It’s not. Being debt-free is just the starting line. The real goal is Wealth Realization.

    When you eliminate debt, you stop paying for your past and start investing in your future. Every dollar you were sending to a credit card company is a dollar that could be growing in a private reserve account or a land banking project.

    This is why we focus on the S.I.M.P.L.E. method: Shift, Increase, Multiply, Protect, Leverage, and Everything. Debt elimination falls under "Increase" (increasing your cash flow) and "Protect" (protecting your future earnings from interest).

    MWR @Home Opportunity

    Ready to Start Your Financial Makeover?

    Choosing between Avalanche and Consolidation is a great first step, but it's only one piece of the puzzle. If you really want to change your life, you need a comprehensive plan that addresses your taxes, your credit, your debt, and your investments all at once.

    That’s exactly what the MWR Lifestyle & Legacy Membership offers. We provide the experts to do the heavy lifting for you: from lowering your monthly bills to correcting your credit and strategizing your debt payoff.

    Your Action Plan:

    1. Run the Numbers: List your debts and interest rates. See if an Avalanche makes sense.
    2. Join the Community: We have a thriving community on Skool where we share daily tips, success stories, and deep dives into wealth-building strategies. Come hang out with people who are on the same journey as you!
    3. Start Your Transformation: Don't wait for "the right time" to fix your finances. The best time was yesterday; the second best time is right now.

    Click here to start your Financial Transformation with the MWR Membership!

    Let’s stop making the banks rich and start making YOU wealthy.


    Tweet Draft for Sonny:
    "Debt Avalanche vs. Consolidation: Which one actually saves you $12k in interest? 📉 We're breaking down the math and the mindset behind debt elimination on the blog today! Don't let interest steal your legacy. Read more here: [Link] #MakeWealthReal #FinancialFreedom #DebtFreeJourney"

  • Asset Protection 101: How MWR Secures What Matters Most

    Asset Protection 101: How MWR Secures What Matters Most

    You've worked hard to build what you have. Your home, your savings, your investments, your business: these assets represent years of sacrifice, smart decisions, and relentless effort. But here's the harsh reality: without proper protection, everything you've built could disappear in an instant.

    One lawsuit, one unexpected crisis, one financial predator, and decades of wealth-building can vanish overnight. That's where asset protection comes in, and it's exactly why MAKE WEALTH REAL has made securing your financial future a cornerstone of our membership program.

    What Asset Protection Really Means

    Asset protection isn't just for the ultra-wealthy hiding money in Swiss bank accounts. It's a fundamental strategy that every middle-class family needs to understand and implement. At its core, asset protection is about creating legal barriers between you and anyone who might try to take what's yours.

    Think of it like building a fortress around your wealth. You're not doing anything shady or illegal: you're simply using proven, legitimate strategies to make it harder for creditors, lawsuits, or other financial threats to reach your assets.

    image_1

    The beauty of proper asset protection is that it works best when implemented before you need it. Once someone is already coming after your assets, your options become limited and expensive. But when you plan ahead, you can create multiple layers of protection that work together to keep your wealth safe.

    The Everyday Threats Most Families Ignore

    Most people think asset protection is only necessary if you're a doctor worried about malpractice suits or a business owner facing potential lawsuits. But the truth is, everyday families face asset threats that could wipe them out financially:

    Personal Liability Scenarios: You cause a car accident that exceeds your insurance coverage. Your teenager throws a party and someone gets seriously injured. Your dog bites a neighbor who decides to sue. These aren't rare occurrences: they happen to regular families every single day.

    Business Exposure: Even if you just have a small side hustle, you could be personally liable for business debts or lawsuits. That Etsy shop or consulting business might seem harmless, but without proper protection, it could expose all your personal assets.

    Divorce and Family Disputes: Nearly half of all marriages end in divorce, and family disputes over inheritance can get ugly fast. Without proper asset protection structures, you could lose half of everything you've worked for, or worse.

    Economic Instability: Bank failures, currency devaluation, and economic crashes can threaten traditionally "safe" assets. Diversification and protection become crucial when entire financial systems are at risk.

    image_2

    How MWR's Asset Protection Program Works

    At MAKE WEALTH REAL, we don't believe in one-size-fits-all solutions. Our asset protection strategies are tailored to your specific situation, family structure, and wealth level. Here's how we approach protecting what matters most to you:

    Legal Structure Optimization

    We help you create the right legal entities to hold different types of assets. This might include setting up LLCs for real estate holdings, trusts for long-term wealth transfer, or other structures that create legal separation between you and your assets.

    The key is matching the right structure to the right assets. Your primary residence needs different protection than your investment properties. Your business assets require different strategies than your retirement accounts.

    Domestic and International Strategies

    While most of our clients start with domestic asset protection, we also provide access to international strategies when appropriate. This isn't about hiding money offshore: it's about legal diversification that makes it harder for creditors to reach your assets.

    image_3

    International structures can be particularly effective for business owners, real estate investors, and anyone with substantial liquid assets. When properly implemented, these strategies are completely legal and transparent to tax authorities.

    Insurance Optimization

    Proper insurance is your first line of defense, but most people are dramatically underinsured. We review your entire insurance portfolio to identify gaps and ensure you have adequate coverage across all areas of potential liability.

    This includes reviewing your homeowner's insurance, auto coverage, professional liability, and umbrella policies. We also explore specialized insurance products that many people don't even know exist but could be crucial for their specific situation.

    Ongoing Monitoring and Adjustment

    Asset protection isn't a "set it and forget it" strategy. As your wealth grows, your family situation changes, and laws evolve, your protection strategies need to adapt. We provide ongoing monitoring and regular reviews to ensure your protection remains current and effective.

    Future-Proofing Your Family's Wealth

    The economic landscape is changing rapidly, and traditional approaches to wealth preservation are becoming less effective. Inflation is eroding purchasing power, government debt is reaching unsustainable levels, and new types of financial risks are emerging constantly.

    That's why our asset protection program goes beyond just legal structures. We help you diversify into assets that have historically held their value during times of economic uncertainty:

    Real Estate Holdings: Properly structured real estate can provide both income and protection against inflation while being difficult for creditors to quickly liquidate.

    Precious Metals: Physical gold and silver stored in secure, international locations provide a hedge against currency devaluation and economic instability.

    Alternative Investments: From private lending to business ownership, alternative investments can provide both returns and protection that traditional stocks and bonds can't match.

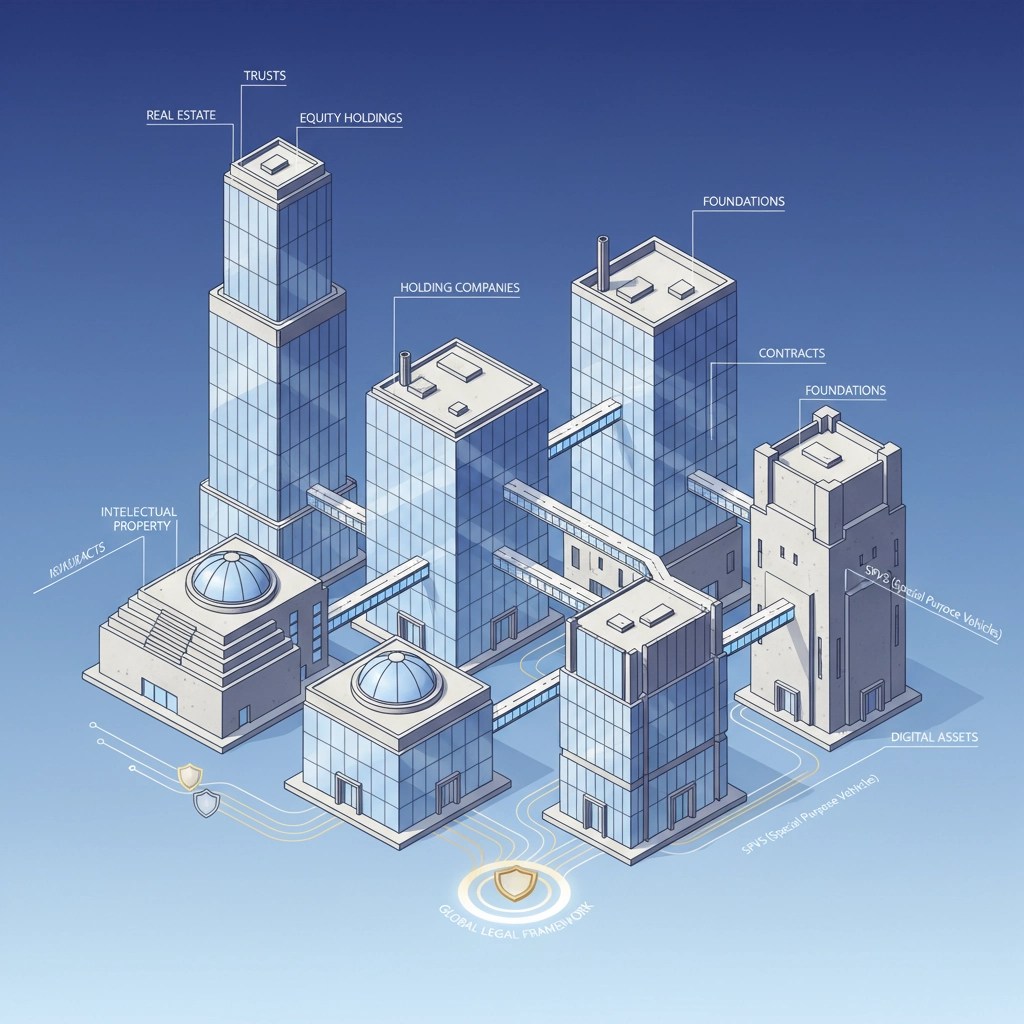
    image_4

    Generational Wealth Transfer

    True asset protection extends beyond your lifetime. We help you structure your wealth in ways that protect it for future generations while minimizing tax implications and providing flexibility for changing circumstances.

    This includes setting up family limited partnerships, dynasty trusts, and other vehicles that can preserve wealth across multiple generations while providing protection from each generation's potential liabilities.

    The Cost of Waiting

    Every day you delay implementing proper asset protection is another day your wealth remains vulnerable. The strategies that work best need time to mature and gain legal strength. Courts are more likely to respect asset protection structures that have been in place for years rather than those created in anticipation of specific threats.

    Moreover, the cost of implementing these strategies while you're financially healthy is a fraction of what you'll pay trying to protect assets during a crisis. Emergency asset protection is expensive, stressful, and often less effective than proactive planning.

    Taking the First Step

    Asset protection might seem complex, but it doesn't have to be overwhelming. The key is starting with a comprehensive review of your current situation and identifying the most significant vulnerabilities first.

    At MAKE WEALTH REAL, we've helped thousands of families protect their wealth using proven strategies that work in the real world. We understand that every family's situation is unique, and we take the time to create protection strategies that fit your specific needs and goals.

    Don't wait until it's too late. The time to protect your assets is now, while you're thinking clearly and have the luxury of implementing strategies at your own pace.

    Ready to secure what you've worked so hard to build? Start your financial makeover today by joining the MAKE WEALTH REAL membership at www.mwrfinancial.com/krnrstn21. We’ll help you lock down what you’ve built, reduce your risks, and position your family to protect and grow wealth for the long haul. Visit www.mwrfinancial.com/krnrstn21 to get started now—your future self will thank you for taking action today.


    Tweet Draft for Sonny:
    "Asset protection isn't just for the ultra-wealthy. Every middle-class family needs strategies to protect what they've built. One lawsuit, one crisis, and decades of wealth-building can vanish overnight. Learn how to build your fortress: www.mwrfinancial.com/krnrstn21 #AssetProtection #WealthBuilding #FinancialSecurity"

  • Why Everyone Is Talking About Off-Market Deals (And How You Can Find Them Too)

    Why Everyone Is Talking About Off-Market Deals (And How You Can Find Them Too)

    If you’ve spent any time looking for a home or an investment property lately, you know the vibe. You find a place on a popular listing site, it looks perfect, and by the time you’ve finished your first cup of coffee, there are already twelve offers, a bidding war has broken out, and someone just offered $50k over asking price: all cash.

    It feels like a war zone out there. But what if I told you that some of the best houses: the real "hidden gems": never even make it to Zillow or the MLS?

    Welcome to the world of off-market deals.

    In 2026, the secret is out: if you want to make wealth real in the real estate game, you have to stop looking where everyone else is looking. You need to get on the "Secret Menu." Today, we’re breaking down why off-market deals are the talk of the town and, more importantly, how you can start finding them yourself.

    The "Secret Menu" of Real Estate

    Think of the MLS (Multiple Listing Service) like a popular franchise restaurant. Everyone knows what’s on the menu, everyone is ordering the same thing, and the lines are out the door.

    Off-market deals are like the secret menu. They are properties for sale that aren't publicly advertised. Because they aren't "on the market," there’s no "For Sale" sign in the yard and no public listing for thousands of people to see. According to recent data, about 11% of sellers find their buyers without ever listing the property publicly. In a tight market, that 11% is where the real profit lives.

    Why Is Everyone Obsessed With Off-Market?

    The hype isn’t just noise. There are massive benefits for everyone involved: what we call the "Triple Threat": Sellers, Buyers, and Investors.

    1. For the Sellers: Privacy and Peace of Mind

    Not everyone wants a parade of strangers walking through their living room every weekend. Some sellers: especially those with high-end properties or sensitive life situations: prefer a quiet, discreet sale. Off-market deals allow them to skip the staging, skip the open houses, and deal with one serious buyer instead of fifty "looky-loos."

    2. For the Buyers: Zero Competition

    Imagine finding your dream home and not having to fight off ten other families. Off-market deals give buyers a chance to negotiate one-on-one with a seller. Without the pressure of a ticking clock or a bidding war, you can often secure a much better price and more favorable terms.

    3. For the Investors: The Margins You Need

    For real estate investors, the math has to work. When you buy off the MLS, you’re usually paying retail. When you find a deal off-market, you’re often finding a "distressed" situation: maybe a tired landlord, an inherited property, or a house that needs some TLC. This is where you find the deep discounts that allow for high ROI.

    Modern luxury villa hidden behind a gate representing exclusive off-market real estate deals.

    How to Find the "Unfindable": 4 Pro Strategies

    You won't find these deals by refreshing your browser. You have to be proactive. Here is how the pros are doing it in 2026:

    Strategy 1: The Power of the "Pocket Listing"

    Real estate agents often have "pocket listings." These are properties where the seller has signed a contract but isn't ready to go public yet, or they only want the agent to show it to a select group of qualified buyers.

    To get in on this, you need a relationship with an agent who is "in the mix." At MAKE WEALTH REAL, we leverage the power of The Real Brokerage to stay connected to these exclusive opportunities. You can see how we operate at https://onereal.com/lamont-milbourne.

    Strategy 2: "Driving for Dollars"

    This is an old-school classic that still works wonders. Grab your car (or your bike) and head into neighborhoods where you want to buy. Look for the "ugly" houses. Long grass, peeling paint, or a stack of newspapers on the porch. These are signs of a property that might be neglected. A simple letter or a knock on the door can turn a "distressed property" into your next big win.

    Strategy 3: Networking with Wholesalers

    Wholesalers are the "deal hunters" of the real estate world. They spend all day marketing to motivated sellers, getting houses under contract, and then "assigning" those contracts to investors like you for a fee. Building a relationship with a few solid wholesalers is like having a personal deal-delivery service.

    S.I.M.P.L.E Leverage Everything! Weekly Event Promotional Graphic

    Strategy 4: Direct Mail and Digital Marketing

    It might sound like 1995, but direct mail still works. Sending postcards to specific lists: like people who have high equity in their homes or those who have recently inherited property: can trigger a conversation before they even think about calling a traditional agent.

    The Biggest Mistake: Not Being "Investor Ready"

    Here is the cold, hard truth: finding an off-market deal is only half the battle. If you find a killer deal today, do you have the funding ready to close it?

    Off-market sellers usually want one thing: Speed. They aren't waiting 45 days for you to figure out your credit score or talk to a local bank that doesn't understand investment properties.

    This is where Lamont Milbourne’s Paid Funding Preparation Service comes in. If you want to play in the big leagues, you need to be "Investor Ready." Our package isn't just a "good luck" wish; it’s a full-scale tactical advantage including:

    • Professional Deal Analysis: We make sure the numbers actually make sense.
    • Accurate ARV Comps: Knowing the "After Repair Value" is the difference between a profit and a loss.
    • Detailed Rehab Budgets: Don’t get blindsided by construction costs.
    • Loan Submission Packages: We prepare your file so it’s "plug and play" for our lending partners at Real Brokerage.

    Don't let a great deal slip through your fingers because your paperwork wasn't in order. Visit https://lmilbourne9.wixsite.com/millisproperty to get your funding prep started.

    The Triple Threat Call to Action

    Whether you are looking to sell, buy, or invest, there is a path for you:

    • ARE YOU A SELLER? If you want a fast, private sale without the headache of the open market, let's talk. We have a network of hungry investors ready to go.
    • ARE YOU A BUYER? Stop fighting for scraps on the MLS. Let us help you find a home that fits your life and your budget: privately.
    • ARE YOU AN INVESTOR? You need deals, and you need funding. We provide both.

    A diverse group of real estate investors and professionals collaborating on a high-rise balcony.

    Join the Community

    Wealth isn't built in a vacuum. It’s built through community, education, and the right tools. If you’re serious about shifting your financial future, you need to be in the room where it happens.

    We invite you to join our Skool community. It’s where we drop the latest tips, share off-market strategies, and help you navigate the complex world of real estate and wealth management in 2026.

    And remember, real estate is just one piece of the puzzle. To truly protect and multiply your wealth, you need a solid financial foundation. This is what we do every day at MAKE WEALTH REAL. From tax strategies to debt elimination, we help you keep more of what you earn so you can invest more in what you love.

    MWR @Home Opportunity Promotion

    Ready to start your Financial Transformation?
    Join the MWR membership today and get the makeover your bank account deserves.
    Sign up here: www.mwrfinancial.com/krnrstn21

    For more information on our programs and how we help thousands of people achieve financial freedom, visit www.mwrfinancial.com.


    Tweet Draft for Sonny:
    "The best real estate deals aren't on Zillow: they're 'off-market.' 🏠 Ready to stop the bidding wars and start finding hidden gems? Check out our latest guide on how to get on the 'Secret Menu' of real estate and get Investor Ready! 🚀 #RealEstate #WealthBuilding #OffMarketDeals #MWR"