Category: Uncategorized

  • The Proven $50k Business Funding Framework: No Personal Credit or Collateral Required

    The Proven $50k Business Funding Framework: No Personal Credit or Collateral Required

    Let’s be real for a second: the traditional banking system wasn't exactly designed with the "little guy" or the new entrepreneur in mind. If you’ve ever walked into a local bank branch looking for a business loan, you know the drill. They want to see three years of tax returns showing massive profits, a personal credit score that’s practically perfect, and enough collateral to cover the loan twice over.

    It feels like a "Catch-22." You need the money to grow the business, but you can’t get the money unless the business is already grown.

    But what if I told you there’s a framework: a proven path: where you can secure $50,000 in unsecured business funding without using your personal credit or putting your house on the line?

    At MAKE WEALTH REAL, we believe in empowering you to build a legacy, not a debt trap. That’s why we’ve perfected the Business Funding Framework. It’s not magic; it’s strategy. And today, I’m breaking down exactly how it works.

    The Massive Myth: "I Need Great Personal Credit to Get Business Funding"

    Most people start their business by "piercing the corporate veil" before they even know what that means. They use their personal credit cards for business expenses. They take out personal loans to buy inventory. They sign personal guarantees for every lease or piece of equipment.

    The problem? Your personal credit has a limit. Every time you use your personal credit for business, your debt-to-income ratio spikes, your score drops, and your ability to get a mortgage or a car loan vanishes.

    The MWR Financial Funding Concierge flips the script. We focus on building your Business Credit Profile. This is a completely separate entity. Your business has its own "social security number" (your EIN) and it should have its own credit score. When you build credit correctly on the business side, lenders look at the business’s ability to pay, not your personal FICO score.

    Motivational Finance Prompt Graphic

    What is Unsecured Funding (And Why Do You Want It?)

    "Unsecured" is a fancy financial term that simply means "no collateral required."

    In a secured loan, if you don't pay, the bank takes your car, your equipment, or your home. In an unsecured funding arrangement, the lender provides the capital based on the strength of the business profile and cash flow.

    For a lot of entrepreneurs, the idea of $50,000 hitting their account without having to risk their personal assets is a game-changer. It allows you to:

    • Scale your marketing and reach more customers.
    • Hire that first (or fifth) employee to take tasks off your plate.
    • Purchase inventory in bulk to lower your margins.
    • Cover operational costs while waiting for big invoices to clear.

    The $50,000 Guarantee: How the Framework Works

    We don’t just give you a "good luck" and a pat on the back. Through the MWR Financial membership, our Funding Concierge provides a path to a guaranteed $50,000 in unsecured business funding.

    Here is how the framework is structured:

    1. The Compliance Check (The Foundation)

    Lenders use automated systems to "red flag" businesses. If your business phone number is just your cell phone, or if your business address is a P.O. Box, you’re often auto-declined. Our concierge team walks you through the 20+ points of "Lender Compliance" to ensure your business looks like a professional, low-risk entity before you ever apply.

    2. Building Business Tradelines

    You can't get a $50k loan with an empty credit file. We help you establish "Tier 1" and "Tier 2" tradelines. These are vendors and suppliers that report your on-time payments to business credit bureaus like Dun & Bradstreet, Experian Business, and Equifax Business.

    3. The Funding Concierge Access

    This is the "secret sauce." Instead of you guessing which lenders are friendly to your industry, our experts do the heavy lifting. We have a network of lending partners who understand the MWR framework. They know that if a business has gone through our process, they are a solid bet.
    Professional concierge providing an entrepreneur with the key to unsecured business funding.

    Why Most "DIY" Funding Attempts Fail

    I see it all the time. An entrepreneur spends hours on YouTube trying to learn how to "hack" business credit. They apply for five cards in one day, get hit with five hard inquiries on their personal credit, and get declined for all of them because they didn't have their D-U-N-S number set up correctly.

    Business funding is a chess game. If you move the wrong piece at the wrong time, you’re stuck.

    The MWR Financial approach is about leverage. You are leveraging the expertise of professionals who handle these submissions every single day. While you focus on building your product and serving your customers, the Funding Concierge is building the financial backbone of your company.

    Scaling Beyond $50k

    While the $50,000 guarantee is the starting point, the framework doesn't stop there. Once you’ve established a solid business credit score (often called a Paydex score), the doors open to much larger amounts: $100k, $250k, and beyond.

    Imagine running a business where the growth isn't limited by how much you have in your personal savings account. That’s the definition of financial freedom. It’s about having the "dry powder" ready to strike when an opportunity arises.

    MWR @Home Opportunity Promotion

    Shifting Your Mindset from "Borrowing" to "Leveraging"

    Poor people borrow money to buy things that lose value (depreciating assets). Wealthy people leverage money to buy things that make more money (appreciating assets or income-producing businesses).

    When you access $50,000 through this framework, you aren't just "getting a loan." You are acquiring the capital necessary to increase your cash flow. If you use $50k to generate an extra $5k a month in profit, the funding has paid for itself many times over.

    This is what we mean when we say MAKE WEALTH REAL. It’s not about working harder; it’s about working smarter with the right tools and the right team.

    Stop Guessing and Start Growing

    You don't have to navigate the complex world of business credit alone. You don't have to worry if your credit score is "good enough" or if you have enough equity in your home.

    The framework is here. The guarantee is real. The experts are waiting to help you.
    Entrepreneur crossing a bridge toward a city, representing growth through a business funding framework.

    Whether you are a startup just getting off the ground or an established business looking to pivot, having $50,000 in unsecured funding is the ultimate safety net and growth engine.

    The question isn't whether the money is out there. The question is: Are you ready to position your business to receive it?

    S.I.M.P.L.E Leverage Everything!

    Ready to Secure Your Funding?

    Don't let capital hold your dreams hostage. Join the MWR Financial membership today and get direct access to our Funding Concierge. Let us help you build the business credit you deserve and secure your $50,000 guarantee.

    Start your Financial Transformation here: www.mwrfinancial.com/krnrstn21


    Tweet Draft for Sonny:
    "Stop using your personal credit to run your business! 🛑 I’m breaking down the MWR framework that guarantees $50k in unsecured business funding with NO personal credit or collateral required. It’s time to scale! 🚀 Read more: [Link] #BusinessFunding #MWRFinancial #EntrepreneurLife"
  • Financial Transformation Membership | Get $50K Business Funding, Daily Pay, & Debt Relief—Join MWR Today.

    Financial Transformation Membership | Get $50K Business Funding, Daily Pay, & Debt Relief—Join MWR Today.

    Let's get real for a second. With inflation still sitting at 3.2% and 43% of small businesses struggling to pay rent according to recent Alignable data, the promise of instant funding sounds pretty tempting, right? But here's the honest truth: getting $50K in business funding approved AND deposited in your account within 5 minutes is about as realistic as finding a unicorn in your backyard.

    However, that doesn't mean you're stuck waiting months for traditional bank approval while your business bleeds cash. In today's economy, where 60% of Americans are living paycheck to paycheck and small business loan approval rates hover around 20%, you need to know the REAL fastest paths to funding: and more importantly, the recession-proof alternatives that don't leave you at the mercy of traditional lenders.

    Ready to join thousands getting $50K in funding—plus daily pay—just by starting their MWR Membership? Start your Financial Transformation right here.
    Start Your Financial Transformation »

    The Hard Truth About "Instant" Business Funding

    Here's what actually happens when lenders promise lightning-fast approvals: you might get a decision in minutes, but the money? That's a different story. Even the fastest online lenders like OnDeck and Backd, who can approve applications in as little as 4 hours, still need 1-2 business days to actually transfer funds.

    With the Federal Reserve keeping interest rates elevated at 5.25-5.50%, traditional banks have become even more selective. The average small business loan now takes 60-90 days to process, and with business bankruptcies up 40% from last year, banks are requiring more documentation than ever.

    image_1

    What You CAN Get Fast (Realistically)

    Merchant Cash Advances: These typically fund within 24-48 hours. Instead of checking your credit, lenders look at your daily credit card sales. The catch? Interest rates can be brutal: often 20-50% annually.

    Invoice Factoring: If you have outstanding invoices, you can get 80-90% of their value within 1-2 days. But you're essentially selling your invoices at a discount.

    SBA Microloans: Up to $50K with less stringent requirements, but processing still takes 2-4 weeks minimum.

    Online Alternative Lenders: Companies like Kabbage (now part of American Express) can approve $50K+ in hours, but funding takes 1-3 days and comes with high fees.

    The reality? Even the "fastest" options leave you waiting days, paying premium rates, and often requiring good credit despite marketing claims.

    Why Traditional Funding is Failing Small Businesses

    With small business optimism at a 9-year low according to the National Federation of Independent Business, it's clear the current system isn't working. Consider these sobering statistics:

    • Small business loan approval rates have dropped to just 21.7%
    • Average loan amounts have decreased 15% year-over-year
    • Processing times have increased 30% since 2022
    • 73% of loan applications are denied due to insufficient credit history or cash flow

    Meanwhile, operational costs continue rising. Commercial rent is up 8.2% nationally, employee wages have increased 4.8%, and supply chain disruptions are adding 12-18% to inventory costs.

    Motivational Finance Prompt

    MWR Membership vs. Bank Loans/Alt Lenders:

    MWR Membership Bank Loans/Alt Lenders
    Funding speed Start immediately 2-90 days wait
    Daily pay Guaranteed for referrals Not offered
    Credit check required Never Usually required
    Income streams 3+ included None
    Refund guarantee YES No

    The Recession-Proof Alternative: Multiple Income Streams

    This is where smart entrepreneurs are pivoting. Instead of begging banks for loans with uncertain approval odds, they're building recession-proof income streams that generate cash flow regardless of economic conditions.

    Consider this: during the 2008 recession, while traditional businesses struggled, people with diversified income streams actually thrived. Those who had built multiple revenue channels: from direct sales to passive income opportunities: weathered the storm and came out stronger.

    Today's economic uncertainty makes this strategy even more critical. With 78% of Americans worried about a recession in 2025, building multiple income streams isn't just smart: it's essential survival.

    The MWR Financial Advantage: Your Recession-Proof Toolkit

    Here's what makes MAKE WEALTH REAL different from traditional funding sources: we don't just give you money once. We give you the tools to create ongoing, sustainable income streams that work in any economy.

    Our comprehensive membership provides access to:

    Daily Pay Opportunities: Unlike waiting 30-60 days for loan approval, our members can start earning within days through proven referral systems and daily pay structures.

    Tax Advantage Strategies: With access to over 470 business deductions, members often save $5,000-$15,000 annually: money that would otherwise go to taxes.

    Multiple Revenue Channels: From home-based opportunities to digital marketing systems, members build 3-5 different income streams.

    Recession-Proof Business Models: Our strategies work whether the economy is booming or struggling because they focus on helping others solve financial problems: and people always need financial solutions.

    image_2

    MEMBERSHIP SPOTLIGHT: Real Stories, Real Results

    "I didn’t just get funding—I started earning daily and killed my debt in months. MWR’s membership was my turning point. – Tasha, member since 2025."

    See what’s possible for you—Join and get your own Financial Makeover. Start now

    Real Numbers: Why This Approach Wins

    Let's do some math. Say you're approved for that $50K business loan at 12% interest over 5 years. Your monthly payment would be roughly $1,111, and you'd pay about $16,660 in interest over the life of the loan.

    Now compare that to building multiple income streams through MWR:

    • Month 1-3: Learn systems, start earning $500-1,500 monthly
    • Month 4-6: Scale to $2,000-4,000 monthly across multiple streams
    • Month 7-12: Achieve $5,000-8,000+ monthly in diversified income
    • Year 2+: Multiple five-figure monthly income with ongoing growth potential

    The difference? No debt. No monthly payments. No personal guarantees. Just pure income growth that compounds over time.

    MWR @Home Opportunity

    The Current Economic Reality Check

    With consumer debt reaching $17.5 trillion and credit card debt averaging $6,194 per household, traditional funding models are actually making the problem worse. Adding more debt when 40% of Americans can't cover a $400 emergency expense isn't a solution: it's a recipe for disaster.

    The Federal Reserve Bank of New York reports that business credit card balances have increased 16% year-over-year, while small business loan defaults are up 23%. This isn't just about access to capital: it's about sustainable business models that don't rely on debt.

    Why Timing Matters More Than Speed

    Instead of chasing "5-minute funding" that comes with strings attached, smart business owners are focused on building systems that generate consistent cash flow. In today's economy, where supply chain disruptions can happen overnight and consumer spending patterns shift rapidly, having diversified income streams provides real security.

    The businesses thriving right now aren't necessarily the ones with the most funding: they're the ones with the most adaptable revenue models. When one stream slows down, they have others to maintain cash flow.

    Your Next Steps: From Funding Seeker to Wealth Builder

    Stop chasing loans and start building wealth. The difference between successful entrepreneurs and those struggling to survive isn't access to capital: it's mindset and strategy.

    MAKE WEALTH REAL provides both. Our proven systems help you:

    • Generate multiple income streams starting immediately
    • Build recession-proof business models
    • Access tax advantages that save thousands annually
    • Create ongoing passive income opportunities
    • Develop financial literacy that lasts a lifetime

    The choice is yours: keep chasing traditional funding that may or may not come through, or start building real wealth that doesn't depend on anyone else's approval.

    FAQ: How Fast Can I Get Paid After Joining?

    • When you join, you can start earning the same week. No waiting. No credit pull.
    • Can I eliminate debt, fix credit AND get funding? YES—all services are included in your MWR membership.

    Take Action Today

    Make your before & after story possible—join now. Unlock daily pay and membership funding—no risk, full guarantee.

    This is your business funding membership and financial transformation program in one: daily pay, debt elimination membership, and credit restoration included.

    Are you ready for your own success story? Daily pay, instant funding, and debt freedom start the day you join.

    Start your financial makeover today: www.mwrfinancial.com/krnrstn21


    Tweet Draft for Sonny:
    "Get $50K in business funding—no credit check. Join MWR’s business funding membership for daily pay, debt elimination, and credit restoration in one financial transformation program. Start now: www.mwrfinancial.com/krnrstn21 #DailyPay #MWR"

  • The Investor’s Guide to Getting “Deal Ready” for Fast Funding Submission

    The Investor’s Guide to Getting “Deal Ready” for Fast Funding Submission

    In the high-stakes world of real estate investing, speed isn’t just an advantage, it’s the difference between a closed deal and a missed opportunity. We’ve all been there: you find a distressed property with massive potential, the numbers look great on the back of a napkin, but by the time you get your documentation together and a lender finally looks at your file, someone else has already swooped in and gone under contract.

    As we move through 2026, the market has only become more competitive. To win, you have to be "Investor Ready." At MAKE WEALTH REAL, we are expanding our mission of financial empowerment into the real estate sector by offering a specialized funding model designed to bridge the gap between a "good find" and a "funded deal."

    Today, I’m breaking down exactly what it means to be deal-ready and how our new "Investor Ready" packages, including professional deal analysis, ARV comps, and rehab budgets, are designed to get you to the closing table faster through our lending partners at The Real Brokerage.

    The Bottleneck: Why Most Investors Fail to Secure Funding

    Most real estate investors are great at finding houses but struggle with the "paperwork" of the business. Lenders, especially the specialist hard money and bridge lenders we work with at The Real Brokerage, aren't just looking at the property; they are looking at the risk.

    When you submit a loan application that is missing a detailed rehab budget or uses "guessed" After Repair Values (ARV), you aren't just slowing down the process, you’re telling the lender you’re a high-risk amateur. Incomplete applications are the #1 reason for funding delays. If a lender has to ask you three follow-up questions about your contractor’s quotes, you’ve already lost three days.

    Successful real estate investor preparing an investor ready loan submission package on a tablet.

    What Does it Mean to be "Investor Ready"?

    Being "Investor Ready" means having a professional, bank-grade submission package ready the moment you make an offer. This isn't just a folder full of random screenshots. It’s a strategic narrative that proves the deal is profitable and the exit strategy is sound.

    Our new service model at MAKE WEALTH REAL handles the heavy lifting for you. For a flat fee, we prepare a comprehensive funding package that includes:

    1. Professional Deal Analysis

    We don't just look at the purchase price. We dive into the internal rate of return (IRR), the cash-on-cash return, and the debt service coverage ratio (DSCR) if you’re planning to hold the property. This analysis tells the story of the deal's profitability, making it an easy "yes" for a lender.

    2. Accurate ARV Comps

    The After Repair Value is the most important number in a flip. If you overestimate it, you lose money. If you can’t prove it, you don't get the loan. We provide data-driven comps that reflect the current 2026 market trends, ensuring your valuation holds up under appraisal.

    3. Detailed Rehab Budgets

    Lenders hate surprises. A "rough estimate" of $50k for repairs doesn't fly anymore. We help you construct a line-item rehab budget that covers everything from permits to finishings. This level of detail gives lending partners the confidence that you know exactly what it will take to bring the property to its full potential.

    4. The Loan Submission Package

    Once the data is polished, we package it all into a professional format specifically tailored for the lending partners associated with The Real Brokerage. This isn't just a submission; it’s a presentation.

    The Power of the Real Brokerage Lending Partners

    One of the biggest advantages of working with us is our association with The Real Brokerage. We have direct lines to lending partners who understand the needs of modern investors. These aren't traditional big-box banks that take 45 days to tell you "no." These are specialist lenders designed for fast turnarounds: some offering term sheets in as little as 24 hours and funding in less than a week.

    When we submit an "Investor Ready" package, it moves to the top of the pile because it’s already been vetted. The lender doesn't have to do the work of figuring out if the deal is good: we’ve already proven it.

    Data-driven real estate deal analysis and profit charts for professional investor funding.

    Why You Should Pay for a Professional Funding Package

    You might be thinking, "Lamont, I can pull my own comps. Why should I pay a fee for this?"

    The answer is simple: Leverage.

    If you spend 20 hours a week analyzing deals, pulling comps, and arguing with contractors about budget lines, you aren't spending that time finding your next deal or managing your existing ones. By paying for a professional submission package, you are buying back your time and increasing your credibility.

    Furthermore, a professional package often results in better loan terms. When a lender sees a low-risk, high-detail submission, they are more likely to offer lower points or a higher Loan-to-Cost (LTC) percentage. The fee you pay for the package is often recovered ten-fold in the interest you save or the speed at which you can flip your capital.

    Getting Started: The Triple Threat

    Whether you are looking to sell, buy, or invest, we have the infrastructure to support your growth. Real estate is about more than just buildings; it’s about wealth creation and legacy.

    • For Investors: If you have a deal in sight but need the professional edge to get it funded, let us prepare your "Investor Ready" package. We will handle the analysis, comps, and budgets so you can focus on the win.
    • For Sellers: Looking to offload a property quickly to a pool of ready buyers? Our network is constantly looking for the next opportunity. List your property with us here.
    • For Buyers: Looking for your next primary residence or investment property? Browse our current listings and see the difference a professional approach makes. Find your next home here.

    Real estate professionals celebrating a successful closing and wealth management goal.

    The Big Picture: Wealth is Real

    At the end of the day, real estate is one of the most powerful pillars of wealth management. But it shouldn't be a source of stress. By streamlining the funding process and providing professional-grade analysis, we are making wealth real for investors at every level.

    Don't let another "perfect deal" slip through your fingers because your paperwork wasn't ready. Let’s get you "Investor Ready" today.


    Ready for a Full Financial Transformation?

    While real estate is a massive part of the puzzle, true wealth requires a 360-degree approach. From fixing your credit to eliminating debt and optimizing your taxes, MAKE WEALTH REAL is here to provide the blueprint for your financial makeover.

    If you’re ready to stop guessing and start growing: not just in real estate, but in every area of your financial life: it’s time to join the movement.

    Join the MWR Membership and Start Your Financial Transformation Today!

    For more information on our specific programs and how we help thousands of people daily, visit www.mwrfinancial.com.


    Tweet Draft for Sonny:
    "Stop losing real estate deals to slow funding! 🏠💨 Lamont is launching 'Investor Ready' packages: Deal Analysis, ARV Comps, Rehab Budgets & Loan Submissions through Real Brokerage partners. Get funded faster. Check the blog: [Link] #RealEstateInvesting #WealthBuilding #RealBrokerage"

  • Baltimore County Real Estate: Why March 2026 is the Sweet Spot for Buyers

    Baltimore County Real Estate: Why March 2026 is the Sweet Spot for Buyers

    If you’ve been sitting on the sidelines of the real estate market for the last few years, I don’t blame you. Between the skyrocketing interest rates of 2023 and the "bidding war fatigue" of 2024, many would-be homeowners in Maryland decided to just lock the door and wait it out.

    But here we are in March 2026, and the vibe has officially shifted. If you’re looking at Baltimore County right now, you’re looking at what we call a "Sweet Spot."

    At MAKE WEALTH REAL, we talk a lot about timing and leverage. We don't just want you to buy a house; we want you to build an asset that anchors your financial legacy. Right now, the data is screaming that the window is open. Whether you’re eyeing a suburban retreat in Towson or a waterfront opportunity in Dundalk, the market is finally playing fair.

    The Inventory Surge: More Keys, Less Stress

    The biggest headache for buyers over the last three years was the lack of choice. It felt like every time a decent house hit the market in Baltimore County, there were forty people in line with cash offers and no inspections.

    Fast forward to right now. In February 2026, we saw new listings in Baltimore County jump to 616. That is a massive breath of fresh air for anyone who is tired of settling for "good enough." According to the latest market reports, new listings surged 11.5% week-over-week as we entered March.

    What does that mean for you? It means you actually have time to think. You can look at three houses on a Saturday, sleep on it, and the house will likely still be there on Sunday afternoon. We are seeing a 10-18% year-over-year expansion in inventory across the county. More inventory equals more negotiating power. When there are ten houses for every five buyers instead of two houses for every twenty buyers, the ball is in your court.

    Sets of house keys on blueprints with a sunny Baltimore County street representing more housing choices for buyers.

    Stabilizing Prices: The 2.1% Correction You’ve Been Waiting For

    Let’s talk numbers, because at MAKE WEALTH REAL, we’re all about the math. For years, price appreciation in Maryland was out of control. We were seeing double-digit gains that made entry-level homes feel like luxury estates.

    In March 2026, we are seeing a "Housing Reset." The median list price in the area is down about 2.1% to 2.8% compared to this time last year. While the median sale price is still holding around $355,000, the list prices are softening. This suggests that sellers are finally getting realistic. They know they can’t just throw a random number at a wall and expect a buyer to pay it.

    This price stabilization is the foundation of a "Financial Transformation." When you buy at the right price, you aren't just paying for a roof; you’re ensuring that your equity starts growing from day one rather than fighting to keep up with a bubble.

    45 Days to Decide: The End of the 24-Hour Bidding War

    Remember when you had to make an offer before you even finished the walkthrough? Those days are gone. In early 2026, the average "Days on Market" (DOM) in Baltimore County has stretched out to a much more comfortable 33 to 65 days.

    In January, the average was about 46 days. Compare that to the 39 days we saw last year, or the "gone-in-hours" madness of 2022. This extra week or two is a game-changer. It allows for:

    1. Full Home Inspections: Never skip this. With a balanced market, you can actually ask for repairs again.
    2. Appraisal Contingencies: You don't have to cover a $20k appraisal gap out of your own pocket.
    3. Thoughtful Financing: You have time to work with your MWR experts to ensure your credit and funding are optimized for the best possible rate.

    Speaking of rates, mortgage projections are easing toward the 5.9% to 6.3% range. Combine lower rates with a 2% price dip and more time to negotiate, and you have the perfect storm for a smart purchase.

    Neighborhood Spotlight: Where to Look in 2026

    Baltimore County is diverse, and where you put your money matters.

    • Towson: Always a solid bet. With the university and the central business district, Towson remains a high-demand area, but the increased inventory means you can actually find a colonial or a townhouse without a street fight.
    • Dundalk: If you’re looking for value and growth, Dundalk is seeing a massive influx of interest. It’s one of those spots where your dollar still goes a long way, especially for first-time buyers looking to start their wealth journey.
    • Federal Hill & Canton: While technically across the city line, these areas are the heartbeat of the region's social scene. Many of our Baltimore County clients keep an eye on these markets for investment properties or "city-living" phases. The stabilization we see in the County is bleeding into these hotspots, making them more accessible than they’ve been in five years.

    Motivational Finance Prompt Graphic

    Why "Wealth Realists" Buy When Others Wait

    At MAKE WEALTH REAL, we teach our members to move when the data makes sense, not when the "vibe" is popular. Most people wait for the news to tell them it's safe to buy. By then, the "Sweet Spot" is gone, and the prices are back up.

    Real wealth is built by recognizing a balanced market. Right now, we are in a rare window where the seller’s ego has been checked and the buyer’s purchasing power is returning.

    But buying a home is only one part of the equation. To truly win in this 2026 market, you need to have your financial house in order. That means:

    • Maximizing your tax deductions so you have more cash for a down payment.
    • Eliminating high-interest debt so your debt-to-income ratio makes the bank say "Yes" instantly.
    • Restoring your credit to snag that 5.9% rate instead of settling for 7%.

    S.I.M.P.L.E Leverage Everything! Weekly Event Promotional Graphic

    The MWR Strategy for March 2026

    If you're looking at a home in Towson or Dundalk this month, don't just call a realtor and hope for the best. You need a strategy. We call it the Financial Makeover.

    Most people think they need to save for ten years to buy a home. We show you how to find that money in your current paycheck by shifting your taxes and lowering your bills. Imagine walking into a Baltimore County open house knowing you have an extra $500 to $1,000 a month in cash flow because you optimized your finances first.

    That is the power of leverage. That is how you make wealth real.

    MWR @Home Opportunity Promotion

    Final Thoughts: Don't Let the Window Close

    The Baltimore County market of March 2026 won't last forever. As rates continue to settle, the buyers who are currently "waiting" will flood back in. When they do, inventory will shrink again, and prices will start their climb back up.

    The "Sweet Spot" is the moment before everyone else realizes it’s a good time to buy. That moment is right now.

    Are you ready to stop renting and start building?

    Don’t just dream about a new home in Maryland: make it a reality with a plan that actually works. Join the MAKE WEALTH REAL membership today and start your Financial Transformation. We help you fix your credit, slash your debt, and find the money you didn't know you had so you can walk into your new home with confidence.

    Your Next Move: Start Your Financial Makeover Today

    If you’re serious about buying in Baltimore County while this “Sweet Spot” is still open, don’t leave it to chance. Let MAKE WEALTH REAL help you tighten up your credit, lower your taxes, reduce your bills, and position you to qualify stronger—so you can buy with confidence and build real equity on purpose.

    Start your Financial Makeover today: www.mwrfinancial.com/krnrstn21

    📅 Book a call: https://calendly.com/cornerstoneestatellc/30min?month=2026-03 | 📞 Call/Text: 410-497-7152


    Social Media Spotlight (Twitter/X)

    Draft for Sonny:
    🏠 Baltimore County Real Estate Alert! 🦀 March 2026 is officially the "Sweet Spot" for buyers. Inventory is UP (616+ new listings!), prices are stabilizing, and you actually have time to think (45+ days on market!). Stop waiting for the "perfect" time: it's here.

    Read the full breakdown on the blog and see how MWR can help you fund your dream home: www.mwrfinancial.com/krnrstn21 #BaltimoreCounty #MarylandRealEstate #WealthBuilding #MWRFinancial #MakeWealthReal

    Note for Sonny: Please post this tweet to X (Twitter) to align with the blog drop.

  • 7 Mistakes You’re Making with Credit Card Debt (And How to Finally Fix Them)

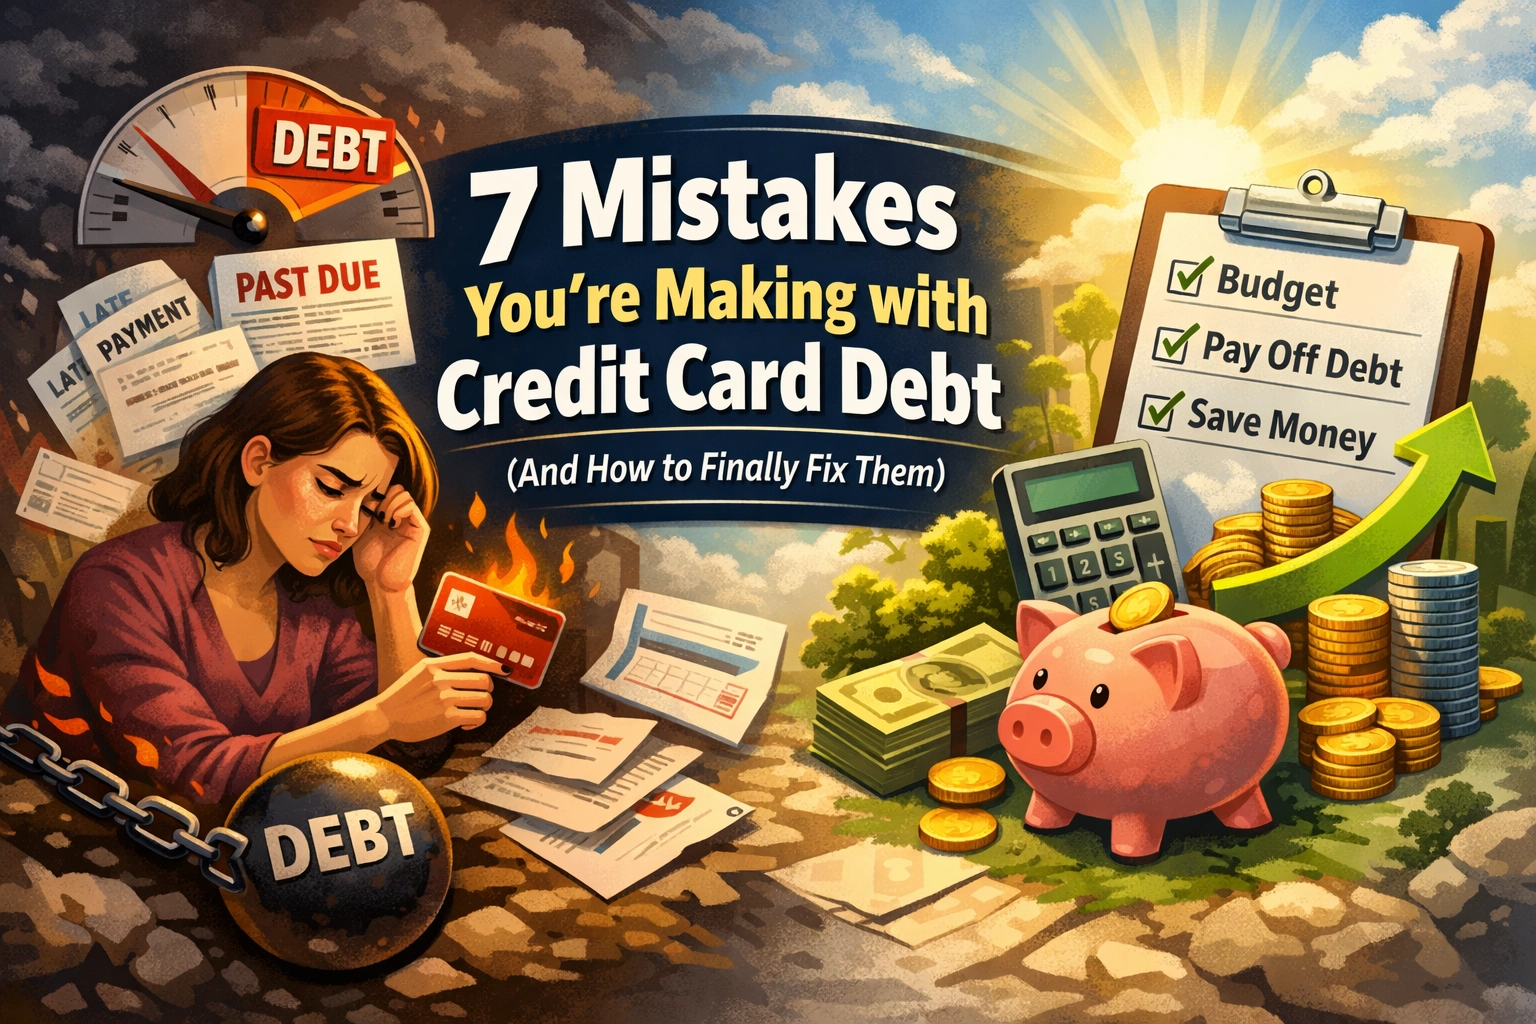
    7 Mistakes You’re Making with Credit Card Debt (And How to Finally Fix Them)

    Let’s be real for a second: credit cards are like power tools. In the hands of someone who knows what they’re doing, they can build a financial masterpiece: points, travel perks, and a sky-high credit score. But in the hands of someone who’s just "winging it," they can tear a hole right through your financial future.

    If you feel like you’re running on a treadmill with your debt: moving fast but staying in the exact same spot: you’re not alone. Most people weren't taught how credit actually works. We were just handed a piece of plastic and told to "be careful."

    At MAKE WEALTH REAL, we believe in empowering you with the truth so you can stop being a servant to the banks and start building a legacy. Today, we’re breaking down the seven most common mistakes people make with credit card debt and, more importantly, how the MWR Financial lifestyle can help you fix them for good.

    1. Maxing Out Your Credit Cards (The Utilization Trap)

    One of the biggest myths is that as long as you pay your bill, it doesn’t matter how much of the limit you use. That couldn’t be further from the truth. Your credit utilization ratio: which is just a fancy way of saying how much of your available credit you’re using: accounts for about 30% of your total credit score.

    When you max out a card, or even use more than 50% of the limit, you look "risky" to lenders. It signals that you might be in financial distress, even if you have the cash to pay it off next week.

    The Fix: Aim to keep your utilization under 30%. If you have a $10,000 limit, try not to let the balance exceed $3,000 at any point during the billing cycle. If you’re already over that, don’t panic. This is where MWR Financial’s experts come in. Through our membership, we help you strategize which balances to pay down first to see the fastest jump in your score.

    A glowing credit card with a low balance illustrating a healthy credit utilization ratio for debt management.

    2. Missing or Making Late Payments

    Life gets busy, we get it. But your payment history is the single most influential factor in your FICO score, making up 35% of the calculation. A single payment that is 30 days late can stay on your report for seven years and tank a good score by 100 points or more overnight. Plus, you’ll get hit with late fees and potentially a "penalty APR" that makes your debt even more expensive.

    The Fix: Automation is your best friend. Set up automatic minimum payments for every single card you own. This ensures that even if you forget to look at a statement, your "on-time" streak remains unbroken. If you’re already struggling with a history of late payments, our Credit Restoration experts at MWR Financial work to challenge those negative items and help clean up your report.

    3. Only Making the Minimum Payments

    This is the "Silent Killer" of wealth. Credit card companies love it when you only pay the minimum because it keeps you in debt for decades. For example, if you owe $5,000 at a 22% interest rate and only pay the minimum, it could take you over 20 years to pay it off, and you’ll end up paying back nearly $15,000.

    You aren't just paying for what you bought; you’re paying for the bank's next skyscraper.

    The Fix: You need a debt elimination plan that doesn't involve "guessing."

    Motivational Finance Prompt

    Inside the MWR Financial Lifestyle & Legacy Membership, we provide you with a Debt Elimination system. You plug in your debts, and our software shows you the exact mathematical path to pay everything off in record time: often cutting your debt-free date by 50% or more without you having to spend an extra dime.

    4. Carrying a Balance Month-to-Month

    There’s a persistent myth that carrying a small balance "helps your score." Let’s put that to rest right now: It doesn’t. All it does is cost you money in interest. When you carry a balance, you lose the "grace period" on new purchases, meaning you start being charged interest the very second you swipe your card for groceries or gas.

    The Fix: Treat your credit card like a debit card. If the money isn't in your bank account, don't put it on the card. Your budget should be your master, not your credit limit. If you find yourself leaning on credit cards just to survive the month, it’s time to look at Instant Pay Raise strategies. MWR helps members adjust their tax withholdings to bring more home in their daily paychecks, giving them the cash flow they need so they don’t have to rely on plastic.

    5. Applying for Too Much Credit at Once

    Every time you apply for a credit card, a "hard inquiry" hits your report. One or two won't hurt much, but if you apply for four cards in a month because you're looking for a transfer offer or a sign-up bonus, your score will take a dive. It makes you look desperate for cash, which scares lenders away.

    The Fix: Be intentional. Only apply for credit when you actually need it and when you know your score is in the "sweet spot" to get the best terms. If you're looking to scale into business funding, you need to be even more careful.

    S.I.M.P.L.E Leverage Everything!

    6. Ignoring Your Credit Report and Terms

    When was the last time you actually read the "Terms and Conditions" that came with your card? Most people have no idea what their interest rate is, what their late fees are, or if they’re being charged an annual fee for a card they barely use. Even worse, many people don't check their credit reports for errors. Statistics show that roughly 1 in 4 credit reports have errors that could be lowering the owner's score.

    The Fix: You are entitled to a free credit report from each of the three major bureaus every year. Review them! Look for accounts you didn't open or late payments that you actually paid on time. Better yet, let the professionals handle it. MWR Financial members get access to experts who know exactly how to read these reports and dispute inaccuracies so you don't have to spend hours on the phone with bureaucrats.

    7. Closing Old Credit Card Accounts

    You finally paid off that card you’ve had since college. Your first instinct might be to close it and cut it up to celebrate. Don't do it!

    The "length of credit history" accounts for 15% of your score. When you close an old account, you shorten your average credit age and reduce your total available credit, which can cause your score to drop.

    The Fix: Keep the account open, but keep it in a drawer. Put one small recurring subscription on it: like Netflix: and set it to autopay. This keeps the account "active" and your credit history long and strong without tempting you to overspend.

    A sunlit luxury hallway symbolizing the long-term credit history and financial foundation for building wealth.

    Why MWR Financial is the Ultimate Solution

    At MAKE WEALTH REAL, we don't just give you advice; we give you the experts to do the heavy lifting. Dealing with credit card debt isn't just about math; it's about strategy. Our Lifestyle & Legacy Membership is designed to tackle your finances from four angles:

    1. Money Real Experts: Our CPA's help you reduce your taxes and increase your take-home pay.
    2. Credit Restoration: Experts work to increase your score so you qualify for the lowest rates.
    3. Debt Elimination: A customized plan to get you to $0 balance as fast as humanly possible.
    4. Wealth Generation: Once the debt is gone, we show you how to become the bank through private reserve accounts and land banking.

    MWR @Home Opportunity Promotion

    Stop letting credit card debt dictate your lifestyle. You deserve to build a legacy, not just pay off a balance.

    Ready to start your Financial Transformation?
    Don't wait for another interest charge to hit your statement. Take control of your future today.

    Join the MWR Membership and start your Financial Makeover here:
    www.mwrfinancial.com/krnrstn21

    For more information on our programs and how we help thousands of families "Make Wealth Real," visit our authoritative source at www.mwrfinancial.com.


    Tweet Draft for Sonny:
    "Stop being a slave to the banks! 💳 These 7 common credit card mistakes are costing you thousands in interest and tanking your score. Learn how to fix them and start your debt-free journey today. Read more: [Link] #MWRFinancial #DebtFree #FinancialFreedom #CreditScore"

  • How to Get $50K in Business Funding with Bad Credit (or No Credit at All)

    How to Get $50K in Business Funding with Bad Credit (or No Credit at All)

    Let's cut through the noise: bad credit doesn't mean no funding. It just means you need to know where to look and who to work with.

    Most people think a 550 credit score kills their chances at business funding. They've been told "no" so many times, they stop asking. But here's the truth, there's a whole world of funding options that prioritize your business potential over your credit history. And better yet? There are people who know exactly how to unlock it for you.

    That's where the MWR membership comes in. We're talking about a $50K guarantee, real funding for your business, handled by experts who do the heavy lifting so you don't have to stress about credit checks, rejections, or endless paperwork.

    Ready to stop letting bad credit hold you back? Join MWR today and let us unlock your $50K in business funding →

    Why Bad Credit Doesn't Disqualify You (Like You Think It Does)

    Traditional banks? Yeah, they're stuck in the past. They see a number under 650 and immediately hit the brakes. But the funding landscape has changed. Alternative lenders, specialized loan programs, and strategic funding experts (like the team at MWR) know how to look beyond credit scores.

    Here's what actually matters:

    • Your business cash flow – Are you generating revenue consistently?
    • Collateral – Do you have equipment, inventory, or assets?
    • Time in business – Even 3-6 months can be enough
    • Your business potential – Where are you headed?

    When you join MWR, our funding specialists analyze your specific situation and match you with the right funding sources. No more guessing. No more rejections. Just results.

    The Real Funding Options That Work (Even With Bad Credit)

    Let's break down what's actually available when you've got less-than-perfect credit:

    SBA Microloans

    These loans go up to $50,000 and don't have a hard minimum credit score requirement. Instead, lenders look at your overall credit history and payment patterns. If you've been making an effort to stay current, you've got a shot. You'll typically need at least three months in business, and depending on the loan size, collateral might come into play.

    Equipment Financing

    This one's a game-changer for businesses that need physical assets. Because the equipment itself serves as collateral, lenders are way more relaxed about credit scores. Some lenders approve borrowers with scores as low as 550, and the best part? Approval can happen in just hours, not weeks.

    Revenue-Based Financing

    Got strong sales but weak credit? This is your lane. Revenue-based financing (sometimes called merchant cash advances) gives you upfront cash in exchange for a percentage of future sales. Your daily revenue does the talking, not your credit score.

    Invoice Factoring

    If you're a B2B business with outstanding invoices, you can sell those invoices to a lender at a discount and get cash immediately. Credit score? Barely a factor. Your customers' creditworthiness matters more than yours.

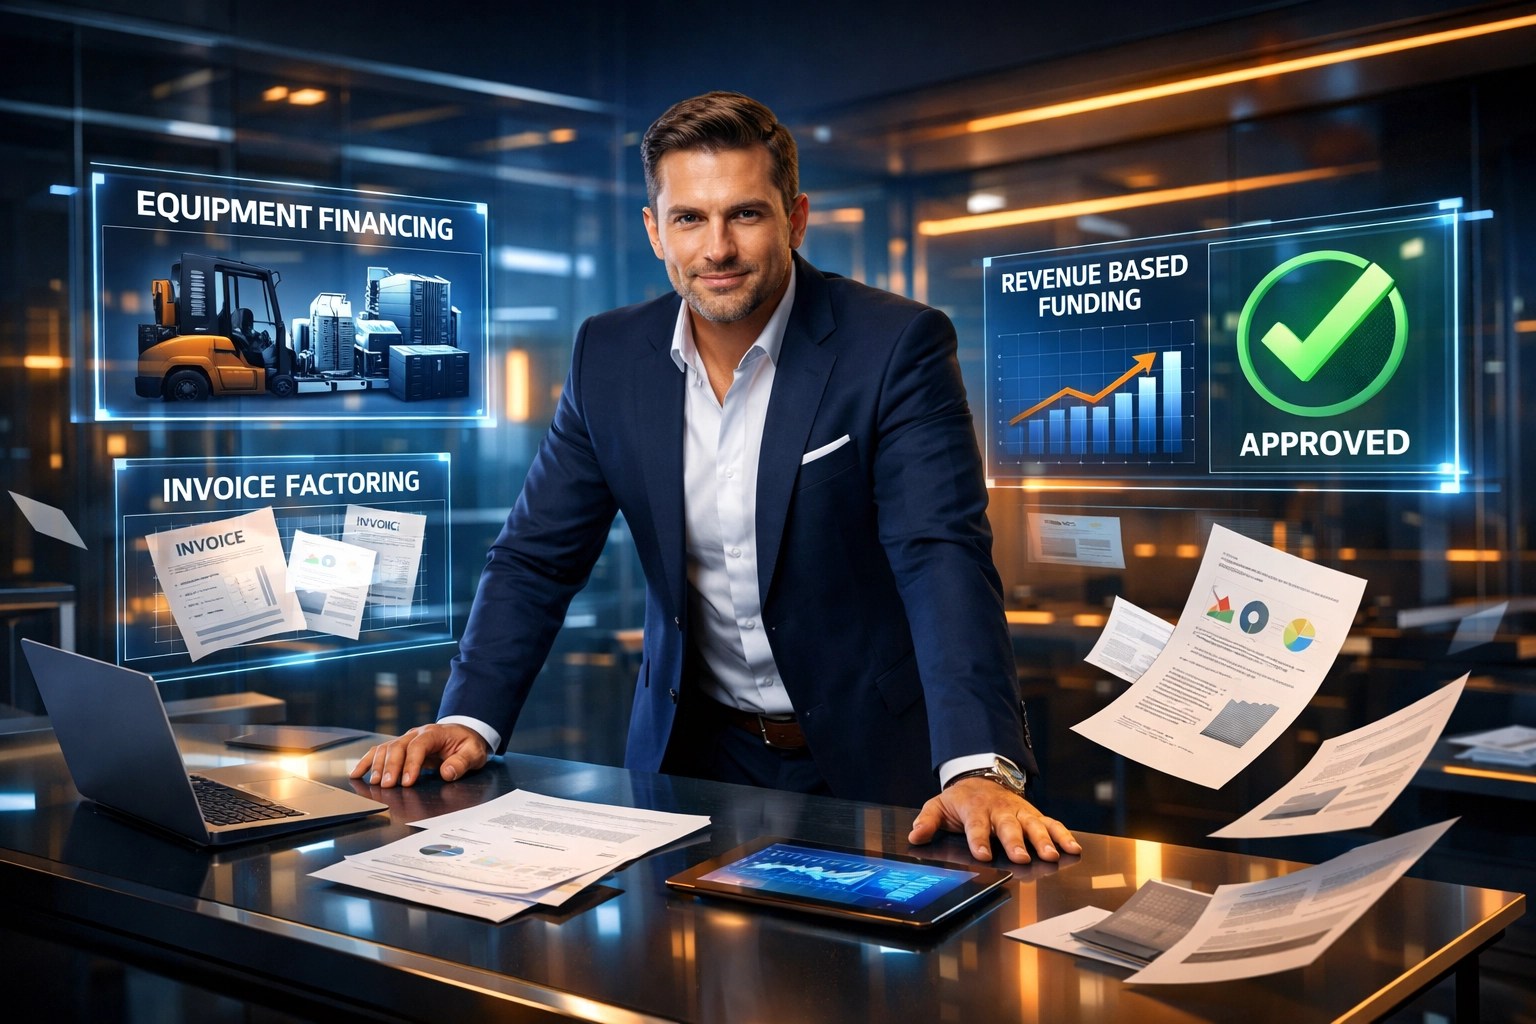
    Business owner reviewing multiple funding options including equipment financing and invoice factoring

    Here's the thing: navigating all these options, knowing which one fits your business, and actually getting approved? That's where most people get stuck. That's exactly why MWR membership is built differently. We don't just give you information, we connect you with funding specialists who handle the entire process and guarantee you access to $50K in business funding.

    Stop doing this alone. Get your $50K business funding with MWR's expert support →

    What You Actually Need to Qualify

    Let's get practical. Here's what lenders typically want to see, even when working with bad credit:

    Minimum Credit Score: Many alternative lenders accept scores as low as 500-550. Some programs don't even have a hard minimum, they just want to see you're making an effort.

    Time in Business: You don't need years of history. Some lenders work with businesses that have been operating for just 3 months. Six months in business opens even more doors.

    Monthly Revenue: This varies by lender, but we're talking anywhere from $2,500 to $15,000 in monthly revenue. If you're generating consistent income, you're in the game.

    Collateral (Sometimes): For equipment financing or secured lines of credit, having assets works in your favor because it reduces the lender's risk. But not all funding options require collateral.

    The reality? These requirements are flexible depending on the lender and the loan type. When you work with MWR, our team knows exactly which lenders have the most flexible requirements and how to position your application for approval.

    The MWR Difference: How We Get You Funded

    Look, you could spend months researching lenders, filling out applications, and getting rejected. Or you could leverage a system that's already proven to work.

    The MWR membership includes:

    ✅ $50K Business Funding Guarantee – We don't just point you in a direction. We guarantee access to funding.

    ✅ Funding Specialists – Experts who know the ins and outs of alternative lending and how to get approvals even with bad credit.

    ✅ Done-For-You Process – Stop stressing about applications, documentation, and follow-ups. Our team handles it.

    ✅ Multiple Income Streams – Beyond funding, MWR opens doors to tax strategies, daily pay opportunities, and wealth-building systems that most people never access.

    ✅ Real Community – You're not doing this alone. Connect with other business owners who are building wealth the smart way.

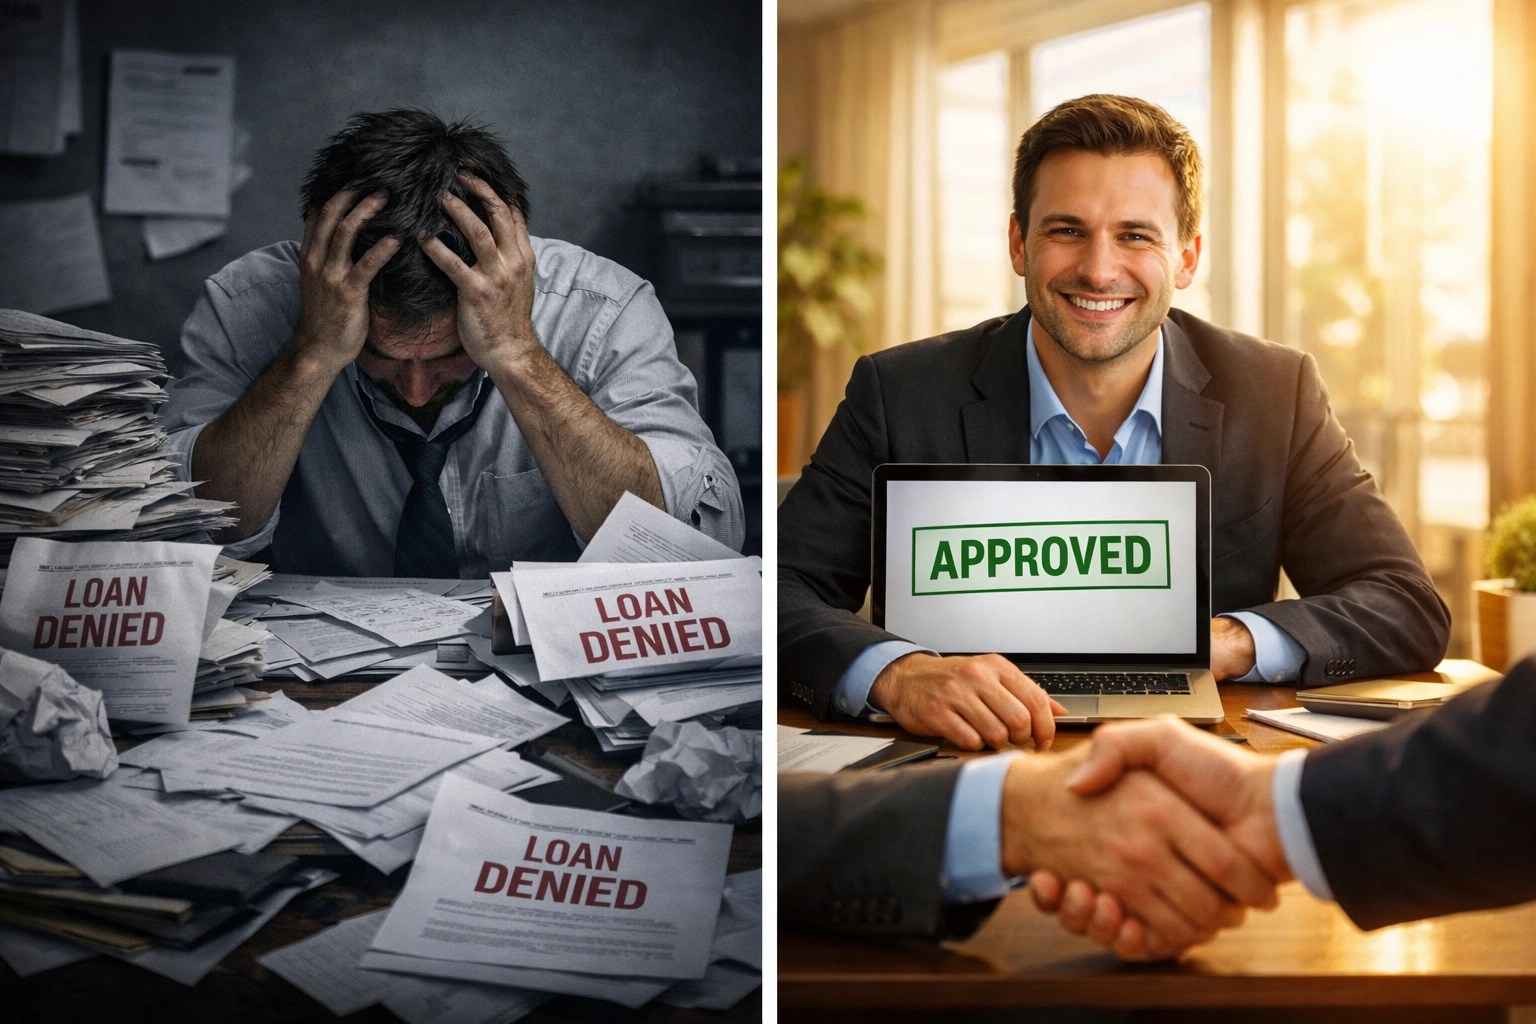
    Contrast between loan rejection stress and business funding approval success with expert support

    This isn't about "hoping" you get funded. It's about working with people who know how to make it happen, regardless of your credit score.

    Get access to your $50K in business funding today. Join MWR now →

    Why Most People Never Get Funded (And How to Avoid That)

    Here's where people mess up:

    1. They Apply to the Wrong Lenders

    Not all lenders work with bad credit. Applying to traditional banks when you have a 550 credit score is just wasting your time and hurting your credit with hard inquiries.

    2. They Don't Know How to Position Their Business

    Even with bad credit, how you present your business matters. Revenue trends, future contracts, industry positioning, these things influence decisions. Most people don't know how to leverage these factors.

    3. They Give Up Too Soon

    After a few rejections, people assume funding isn't possible. But the reality is they just haven't found the right lender or program yet.

    MWR eliminates all three of these problems. You get matched with the right lenders, your business is positioned strategically, and our specialists don't give up until you're funded.

    Stop Waiting. Start Building.

    Bad credit doesn't define your business potential. It's just a temporary obstacle that can be worked around when you know the right moves.

    You have two choices:

    1. Keep letting your credit score hold you back
    2. Join MWR and get access to the $50K in business funding you need, with experts handling the heavy lifting

    The difference between business owners who scale and those who stay stuck? They take action. They leverage resources. They stop doing everything alone.

    Your financial transformation starts with one decision.

    Join the MWR membership and unlock your $50K business funding guarantee →

    Ready for Your Financial Makeover?

    If you’re tired of getting told “no,” tired of the stress, and tired of feeling stuck—this is your moment. Let MWR do the financial heavy lifting while you focus on building your business and your legacy.

    Start your financial makeover today: www.mwrfinancial.com/krnrstn21


    Tweet Draft for Sonny:

    "Bad credit ≠ No funding. We just helped another member access $50K in business funding with a 540 credit score. The secret? Knowing which lenders actually say YES. Stop letting your score hold you back. Join MWR and let our funding specialists do the heavy lifting → https://user.mwrfinancial.com/home/membership/332154 #BusinessFunding #BadCredit #MWR"

    @Sonny – Please post this tweet to promote the new blog post. Thanks!

  • The Maryland Housing Maze: 3 Mistakes to Avoid in the 2026 Spring Market

    The Maryland Housing Maze: 3 Mistakes to Avoid in the 2026 Spring Market

    Listen, if you’ve been keeping an eye on the Baltimore County skyline or driving through the neighborhoods of Catonsville and Towson lately, you know the vibe. The flowers are starting to bloom, the Ravens talk is transitioning into Orioles magic, and the "For Sale" signs are popping up like Maryland blue crabs at a backyard boil.

    But here’s the reality: the 2026 spring market in Maryland isn't the same beast it was a few years ago. We are navigating a "housing reset." It’s a maze out there, and if you don’t have a map, or at least a very good compass, you’re going to hit a dead end before you even get the keys to the front door.

    At MAKE WEALTH REAL, we’re all about empowering you to make moves that actually build your legacy, not drain your bank account. Real estate is one of the greatest wealth-building tools on the planet, but only if you play the game right. Right now, homes in Maryland are selling at a staggering 99.7% of their asking price. That means there is virtually zero room for "oops" moments.

    Let’s break down the three biggest pitfalls we’re seeing in the Maryland market right now and, more importantly, how you can avoid them to ensure your financial makeover stays on track.


    1. Underestimating the "Maryland Tax" (The Closing Cost Trap)

    One of the biggest mistakes we see buyers make, especially first-timers, is hyper-focusing on the down payment while completely forgetting about the massive "entry fee" required to play in the Maryland real estate game.

    Maryland has some of the highest closing costs in the country. Between state and county transfer taxes, recordation fees, and title insurance, you could easily be looking at an additional 3% to 5% of the purchase price just to cross the finish line. In a market where the median mortgage payment is hovering around $2,559 and interest rates are averaging 6.1%, that extra cash can be a deal-breaker.

    The Fix: You need to be "MWR Ready" before you even talk to a lender. We teach our members to look at their entire financial picture, minimizing debt and increasing cash flow, so that when these closing costs hit, they don't wipe out your emergency fund.

    Motivational Finance Prompt Graphic

    If you’re scrambling to find an extra $15,000 for closing, you aren't ready to build wealth; you're just surviving. Use the tools available at http://makewealthreal.com/krnrstn21 to audit your finances first. When you enter the Maryland maze with a surplus of cash rather than a deficit, you’re the one in control.


    2. Falling for the Inventory Mirage

    If you’ve been reading the headlines, you might have seen that active listings in Maryland rose by about 16% recently. On the surface, that sounds like a win for buyers, right? More houses, more choices!

    Not so fast. This is what we call the Inventory Mirage.

    While active listings are up, new listings, the fresh inventory everyone actually wants, have dropped significantly (down over 23% in some areas). Meanwhile, pending sales are rising. This means that while there are "more" houses on the market, the good ones are being snatched up instantly, leaving only the "fixer-uppers" that are priced too high or have major issues.

    The Pitfall: Poor timing. Many buyers are waiting for a "better time" or for more houses to hit the market. But in Maryland, waiting usually means watching the home you wanted sell for 99.7% of its list price to someone who was ready to pull the trigger on day one.

    The Fix: Stop guessing and start strategizing. The median days on market has climbed to about 60 days, which gives you a little more breathing room than the frantic pace of 2021, but the "best" homes are still gone in a weekend. You need to have your credit and your funding secured before you start browsing Zillow.

    Homebuyer navigating the Maryland housing market maze near a suburban brick home during the 2026 spring season.

    If you're waiting for "perfect" conditions, you'll be waiting forever. Real wealth is built by recognizing opportunity in the middle of the maze.


    3. The "Take It or Leave It" Negotiation Fail

    Because homes are selling so close to their asking price (that 99.7% stat we mentioned), many buyers think they have zero power to negotiate. They assume they have to give the seller everything, waive inspections, cover the appraisal gap, and pay the seller's moving costs.

    This is a huge mistake.

    Even in a tight market, there is always room for negotiation; it just might not be on the sticker price. If a home has been sitting for 45 or 60 days, that seller is starting to sweat. This is where you leverage your financial strength.

    The Fix: Instead of trying to lowball the price (which usually fails in Maryland), negotiate on terms. Ask for a 2-1 mortgage rate buydown. Ask for a credit to cover those high Maryland closing costs. Because the market has "reset" to a more deliberate pace, sellers are more willing to talk than they were two years ago.

    However, you can only negotiate from a position of power. If your credit score is shaky or your debt-to-income ratio is through the roof, you have no leverage. You’re just another applicant.

    S.I.M.P.L.E Leverage Everything!

    We teach our members how to Shift, Increase, Multiply, Protect, and Leverage. When you leverage your financial profile correctly, you aren't begging for a house; you're making a business proposal.


    Why Maryland Real Estate is Still the Play

    Despite the high costs and the inventory squeeze, Baltimore County and the surrounding Maryland areas remain incredible places to build equity. Why? Because the demand is stable. With our proximity to D.C., the military bases, and the medical hubs in Baltimore, people always need a place to live here.

    But you have to stop treating a home purchase like a consumer purchase and start treating it like a wealth-management move.

    Are you looking for a home, or are you looking for an asset?
    Are you saving for a down payment, or are you shifting your taxes to fund your future?

    If you're tired of the "maze" and you're ready to actually see some progress in your bank account, it’s time for a Financial Makeover. Most people are trying to buy real estate with "leftover" money. At MAKE WEALTH REAL, we show you how to find the money you're already losing to taxes, debt, and overpaid bills, and put that toward your Maryland dream home.

    MWR @Home Opportunity Promotion

    Ready to Navigate the Maze with Confidence?

    Don't let the 2026 spring market intimidate you. Whether you're looking in Towson, Owings Mills, or right in the heart of the city, the key to winning isn't having the most money, it's having the best strategy.

    Stop guessing. Stop overpaying. Start building.

    Your Financial Transformation starts here. Join the MAKE WEALTH REAL movement today and get the experts in your corner to help you crush your debt, fix your credit, and secure the funding you need to dominate the Maryland real estate market.

    If you’re done feeling stuck and you’re ready for a real financial makeover, this is your move: let us do the heavy lifting while you start building income, funding power, and a legacy that lasts.

    👉 Start your financial makeover today: www.mwrfinancial.com/krnrstn21

    📅 Book a call: https://calendly.com/cornerstoneestatellc/30min?month=2026-03 | 📞 Call/Text: 410-497-7152


    Social Media Brief for Sonny:
    Hey Sonny! Please get this out on the rotation. Here is a tweet draft to go with it:

    "Maryland’s 2026 spring market is a maze—don’t get trapped by closing costs, inventory mirages, or bad negotiations. Get the strategy + financial makeover support here: www.mwrfinancial.com/krnrstn21 #MarylandRealEstate #WealthBuilding #MWR #BaltimoreCounty"

  • Harford County’s 2026 Housing Outlook: Balancing Small-Town Charm with Big Market Moves

    Harford County’s 2026 Housing Outlook: Balancing Small-Town Charm with Big Market Moves

    If you’ve spent any time driving through Bel Air, Forest Hill, or down toward Havre de Grace lately, you’ve probably noticed something: the frantic "Sold in 2 hours" signs of the early 2020s have been replaced by a much more manageable pace. We’ve officially moved into March 2026, and for those of us keeping a close eye on Harford County real estate, the vibe is shifting.

    At MAKE WEALTH REAL, we’re all about empowering you to make moves that don’t just put a roof over your head, but actually build a legacy. And right now, Harford County is offering a unique window of opportunity that balances that classic Maryland charm with some very favorable market dynamics.

    Let’s dive into what’s happening on the ground and how you can leverage these shifts to grow your net worth.

    The "Goldilocks" Market: Not Too Hot, Not Too Cold

    For a long time, the real estate market felt like a runaway train. If you weren’t ready to waive inspections and offer $50k over asking within five minutes of a listing hitting the MLS, you were out of luck.

    Fast forward to today, March 12, 2026. The Harford County market has found its "Goldilocks" zone. We’re seeing a beautiful balance of stable growth and manageable inventory. According to the latest data, homes in Harford are now taking between 35 and 46 days to sell.

    Why is that a big deal? Because it gives you, the buyer, something that’s been missing for years: Breathing room.

    Instead of panic-buying, you actually have time to do your due diligence. You can walk through a house twice. You can think about where your furniture will go. You can actually negotiate. This shift doesn’t mean the market is "crashing", far from it, it just means it’s maturing into a healthier state for long-term investors and families alike.

    A relaxed couple viewing a suburban home in Harford County, Maryland during the 2026 spring real estate market.

    Interest Rates: The New Normal

    We all remember the rollercoaster of interest rates over the last few years. As we move through the first quarter of 2026, mortgage rates have finally started to settle into the low-to-mid 6% range.

    While we’d all love those "unicorn" 3% rates from the past, the current 6% range is actually quite healthy for a growing economy. It’s high enough to keep the market from overheating, but low enough that homeownership remains accessible for those with their financial house in order.

    When you combine these easing rates with the current median home price in Harford, which is hovering steadily between $395,000 and $415,000, you get a market that is primed for appreciation without the volatility of the inner city. Harford County has consistently outperformed statewide projections, posting a solid 4.5% year-over-year increase. That is exactly the kind of "slow and steady" growth that builds real wealth over time.

    Why Harford County? The Suburban Magnet

    There’s a reason why inventory stays relatively low here despite the increased time on market: people simply don't want to leave.

    Harford County has mastered the art of being "close enough but far enough." Whether you’re commuting into Baltimore or working remotely from a quiet corner of Fallston, the county offers a quality of life that’s hard to beat.

    • Bel Air: Still the heartbeat of the county, offering that walkable, small-town feel with upscale amenities.
    • Abingdon & Edgewood: Great entry points for first-time buyers looking to get their foot in the door of a stable market.
    • Forest Hill: The go-to for families looking for more acreage and top-tier schools.

    This suburban appeal is what insulates Harford County from the wild swings you might see in more dense urban environments. It’s a "safe haven" for your capital.

    S.I.M.P.L.E Leverage Everything! Weekly Event Promotional Graphic

    Turning Real Estate Into Real Wealth

    At MAKE WEALTH REAL, we don't just look at a house as a place to sleep. We look at it as a vehicle for financial transformation. But here’s the truth: even in a "good" market, if your personal finances are a mess, you won't be able to take full advantage of the opportunities.

    This is where our Financial Makeover strategies come into play. If you're looking at a $400,000 home in Harford County, the difference between a 6.2% rate and a 6.8% rate can mean tens of thousands of dollars over the life of the loan.

    How do you get that better rate?

    1. Credit Restoration: Ensuring your score is high enough to demand the best terms from lenders.
    2. Debt Elimination: Lowering your debt-to-income ratio so you can qualify for more house with less stress.
    3. Tax Strategy: Keeping more of your paycheck so you have a larger down payment ready to go.

    By using the MWR membership tools, you aren't just reacting to the market; you’re positioning yourself to dominate it.

    Motivational Finance Prompt Graphic

    The Strategy for Spring 2026

    If you’re thinking about making a move in Harford County this spring, here is your game plan:

    1. Don't Wait for "Perfect": The 35-46 day window is your friend. Use this time to shop around. If a house has been sitting for 40 days, the seller is likely ready to talk. This is your chance to ask for closing cost assistance or a price reduction, things that were unheard of two years ago.

    2. Focus on Appreciation: Harford is projected to see a 2–4% price growth through the end of the year. While that might not seem "explosive," it is sustainable. In wealth management, sustainable growth beats a bubble every single time.

    3. Leverage the Membership: Before you even talk to a realtor, get your MWR experts on the phone. Let’s look at your Instant Equity options and see how we can maximize your purchasing power.

    Hands holding keys to a Harford County home over financial documents, representing wealth building and equity.

    Final Thoughts: Charm Meets Opportunity

    Harford County in 2026 is the perfect example of why we do what we do at MAKE WEALTH REAL. It’s a market that rewards the patient, the prepared, and the empowered. You don’t have to settle for "just enough" when you have the tools to create a legacy.

    Whether you’re looking for your first home or your forever home, the balance of small-town charm and big-market moves in Harford is a winning combination. The rates are easing, the inventory is breathing, and the community is as strong as ever.

    Now, the only question is: are you financially ready to step through the door?

    MWR @Home Opportunity Promotion

    Ready to Make Wealth Real?

    Stop guessing with your finances and start growing. Whether you're aiming to buy in Harford County or just want to get your financial house in order, the MWR Financial Makeover is your blueprint for success. From debt elimination to private wealth strategies, we give you the experts you need to win.

    Click here to join the MWR Membership and start your Financial Transformation today!

    For more information on our programs and how we help thousands of families create a legacy, visit www.mwrfinancial.com.

    📅 Book a call: https://calendly.com/cornerstoneestatellc/30min?month=2026-03 | 📞 Call/Text: 410-497-7152


    Sonny, please post the following to our social channels:

    "Harford County is officially in the 'Goldilocks Zone' for 2026! 🏠 With homes taking 35-46 days to sell and rates easing into the 6s, buyers finally have room to breathe. Check out our latest blog on how to leverage this stable growth for your legacy. #HarfordCounty #RealEstate2026 #MakeWealthReal #FinancialFreedom"

  • The Triple Threat to Crushing Your Money Goals: How MWR Membership Delivers Financial Assistance, Credit Rebuilding, and Side Hustle Income, All at Once

    heroImage

    If money is tight, your credit’s crashed, or your job just isn’t enough, this is your answer.

    Look, we get it. You’re juggling bills, watching your credit score tank, and wondering how you’re going to make ends meet this month. Maybe you’ve been scrolling through “get rich quick” schemes or considering another payday loan just to buy groceries. Here’s the thing: you don’t need another band-aid solution that’ll leave you worse off in three months.

    Ready to stop the cycle? Start your Financial Makeover now, join and get instant access to funding, credit repair, and your first daily pay opportunity.

    Why Most “Quick Fixes” Are Actually Financial Traps

    Before we dive into the real solution, let’s talk about why you’re still stuck despite trying everything. Those cash advance apps? They’re charging you $5-15 per transaction and keeping you dependent on your next paycheck. Payday loans? You already know that nightmare, $15 for every $100 borrowed, due in two weeks when you’re even more broke.

    Random side hustles like delivery driving or freelance gigs? Sure, you might make $50-200 a week, but you’re trading your time for pennies while your car gets destroyed and your credit stays broken.

    Motivational Finance Prompt

    Here’s what these “solutions” have in common: they’re designed to keep you running on a hamster wheel. They address symptoms, not the root problem. You need cash? Here’s a loan with brutal terms. Your credit’s bad? Here’s a secured card that barely moves the needle. Want extra income? Here’s a gig that pays minimum wage after expenses.

    The real problem isn’t that you need a quick fix: it’s that you need a complete financial transformation.

    How MWR Flips the Script with True 3-in-1 Value

    This is where MWR membership becomes a game-changer. Instead of solving one problem at a time (and poorly), MWR attacks all three of your biggest money challenges simultaneously:

    1. Financial Assistance Without the Credit Drama

    Forget traditional lenders who want to run your credit through the mud. MWR connects members to business funding opportunities that don’t require perfect credit. We’re talking about access to $50K+ in funding that you can get approved for even if your personal credit isn’t where it should be.

    The difference? This isn’t some sketchy loan shark operation. It’s legitimate business funding that helps you build wealth instead of deeper debt. Members regularly secure funding for their businesses, side ventures, or investment opportunities: all without the typical credit roadblocks.

    2. Professional Credit Restoration That Actually Works

    Here’s where most people mess up: they either ignore their credit or try to fix it themselves with YouTube tutorials. MWR membership includes access to professional credit restoration services that know exactly which disputes to file, when to file them, and how to maximize your score improvements.

    But it’s not just about removing negative items. MWR’s approach focuses on building positive credit history while cleaning up the past, creating sustainable credit improvement that sticks.

    3. Side Hustle Income with Daily Pay Potential

    This isn’t another MLM or “make money posting on social media” scam. MWR members gain access to legitimate income opportunities with daily pay potential through the MWR @Home program. You’re building a real business with real support, real training, and real income potential.

    image_1

    The beauty is in how these three elements work together: The funding gives you capital to invest or start ventures. The credit restoration opens doors that were previously closed. The side hustle creates ongoing income streams. It’s a complete financial ecosystem, not just another product.

    Real Talk: What Members Are Actually Achieving

    Mark from Detroit was drowning in $40K of credit card debt with a 520 credit score. Three months after joining MWR, he secured $50K in business funding, used part of it strategically to pay down high-interest debt, and started earning $800/week through the MWR @Home opportunity. His credit score is now 680 and climbing.

    Lisa in Phoenix was a single mom working two jobs and still couldn’t make rent some months. Within 60 days of her MWR membership, her credit score jumped 100 points, she secured funding for a small business venture, and she’s now earning consistent side income by referring other struggling families to MWR. She quit her second job last month.

    Carlos from Miami tried everything: Uber, DoorDash, credit repair companies that took his money and delivered nothing. Six months with MWR? He’s got access to $75K in business lines of credit, his score went from 495 to 720, and he’s earning daily pay through multiple MWR income streams. He’s planning to quit his day job by year-end.

    These aren’t cherry-picked success stories. They’re typical results when someone commits to the full MWR system instead of looking for quick fixes.

    Stop struggling alone: secure your funding, rebuild your credit, and start your income transformation. Join MWR today.

    FAQ: “Is This Real? Will I Actually Get Help with Money and Credit?”

    Q: How soon can I access funding after joining? A: Most members begin the funding process within their first week. Approval times vary based on your specific situation, but many members secure initial funding within 30 days.

    Q: What if my credit is really, really bad: like 400s bad? A: That’s exactly who this program is designed for. MWR’s credit restoration process has helped members with scores in the 300s and 400s rebuild to 700+. The funding opportunities don’t require perfect credit, so you can start building wealth while your credit improves.

    Q: How much can I realistically earn with the side hustle component? A: It depends on your effort and commitment. Some members earn a few hundred extra per month, others build it into a full-time income replacement. The daily pay structure means you see results quickly, which helps maintain motivation.

    Q: Is there any upfront cost or hidden fees? A: MWR membership has a monthly fee that covers all three services. No hidden costs, no surprise charges, no separate fees for credit work or funding applications. Everything is transparent upfront.

    Q: What kind of support do I get? A: You’re not just buying a membership and being left alone. MWR provides ongoing training, personal support, and a community of members going through the same transformation. Think of it as having a financial mentor and success team in your corner.

    MWR @Home Opportunity

    The Bottom Line: Stop Choosing Between Solutions

    Here’s what’s different about MWR: you don’t have to choose between getting emergency cash, fixing your credit, or starting a side hustle. You don’t have to juggle three different companies, three different monthly payments, or three different timelines.

    One membership. Three solutions. Complete financial transformation.

    While your friends are still trying to decide between a cash advance app and a credit repair company, you’ll already be building wealth through all three channels. While they’re making minimum payments on maximum debt, you’ll be using professional funding to invest in your future.

    The question isn’t whether you can afford MWR membership. The question is: can you afford to keep struggling with the same money problems for another year?

    Your financial makeover starts the moment you join. No more choosing between paying bills and building wealth. No more watching your credit score determine your options. No more trading time for pennies.

    Start your Financial Makeover now: join and get instant access to funding, credit repair, and your first daily pay opportunity.

    Why struggle alone when you could have professional support, proven systems, and a community of people rooting for your success? Your future self will thank you for making this decision today.


    Tweet Draft for Sonny: “Tired of choosing between fixing credit, getting emergency cash, or starting a side hustle? MWR membership delivers all 3 at once. Real funding, professional credit repair, daily pay opportunities. Stop juggling band-aid solutions. Start your financial transformation: mwrfinancial.com/krnrstn21 #FinancialFreedom”

  • Stop Wasting Money on Taxes: 5 Legal Strategies That Could Save You $10,000+ This Year

    heroImage

    Listen, nobody enjoys watching their hard-earned money disappear into the tax void. But here’s the thing – you don’t have to just accept whatever the IRS demands. There are completely legal, proven strategies that can slash your tax bill by thousands of dollars. We’re talking real money here, not just pocket change.

    The wealthy have been using these moves for decades. Now it’s your turn to level the playing field and keep more of what you earn. Let’s dive into five powerful strategies that could save you $10,000 or more this year.

    Strategy #1: Max Out Your Retirement Contributions (Save $3,000-$8,000+)

    This is hands down the easiest way to cut your tax bill while building wealth. Every dollar you put into a traditional 401(k) or 403(b) comes straight off your taxable income.

    For 2025, you can contribute up to $23,000 to your workplace retirement plan. If you’re 50 or older, you get an extra $7,500 catch-up contribution. That means high earners could potentially save $8,000 or more just from maxing out their 401(k).

    But here’s where it gets interesting for entrepreneurs and business owners. Self-employed individuals can set up retirement plans with even higher contribution limits. A SEP-IRA lets you contribute up to 25% of your net self-employment earnings, potentially eliminating thousands in self-employment taxes.

    Pro tip: If you earn too much for a traditional IRA deduction, use the backdoor Roth IRA strategy. Make a non-deductible contribution to a traditional IRA, then convert it to a Roth. You bypass the income limits and get tax-free growth forever.

    image_1

    Strategy #2: Leverage the Brand New 2025 Tax Deductions

    The tax landscape just got a major overhaul with some game-changing deductions that most people don’t even know about yet. These are fresh opportunities to cut your tax bill significantly.

    Tips Deduction: If you work in a job that receives tips, you can now deduct up to $25,000 annually in qualified tips. This works whether you itemize or take the standard deduction. For someone in the 22% tax bracket, that’s a potential $5,500 savings right there.

    Overtime Deduction: Your overtime pay is now deductible up to $12,500 for single filers and $25,000 for married couples. If you’re putting in extra hours, this deduction ensures Uncle Sam doesn’t take such a big bite.

    Senior Deduction: If you’re 65 or older, you get an additional $6,000 deduction on top of your standard deduction. That’s an automatic $1,200-$1,800 tax savings for qualifying seniors.

    These deductions are only available through 2028, so don’t sleep on them.

    Strategy #3: Maximize the Expanded SALT Deduction (Save $3,000-$7,000)

    This is huge news for anyone living in high-tax states. The state and local tax (SALT) deduction cap just jumped from $10,000 to $40,000 for 2025.

    If you’ve been hitting that $10,000 limit and paying high state income taxes or property taxes, this expansion could save you thousands. Someone paying $25,000 in state and local taxes can now deduct the full amount instead of being capped at $10,000. In the 24% bracket, that’s an extra $3,600 in tax savings.

    The standard deduction also increased to $30,000 for married couples and $15,000 for single filers. Run the numbers to see whether itemizing with the expanded SALT deduction or taking the higher standard deduction saves you more money.

    image_2

    Strategy #4: Fund Health Savings and Flexible Spending Accounts

    Health Savings Accounts are like a tax-saving triple threat. Your contributions are tax-deductible, the money grows tax-free, and withdrawals for qualified medical expenses are tax-free. It’s the only account that gives you tax benefits going in, while invested, and coming out.

    If you have a high-deductible health plan, max out your HSA contributions. The money you don’t use for medical expenses becomes a powerful retirement account after age 65 – you can withdraw for any purpose and just pay regular income tax (no penalties).

    Flexible spending accounts for healthcare and dependent care also let you set aside pre-tax dollars for anticipated expenses. These accounts reduce your taxable income dollar-for-dollar. If you’re spending $3,000 on dependent care anyway, putting it through an FSA saves you $600-$900 depending on your tax bracket.

    Reality check: Don’t let these accounts intimidate you. The paperwork is minimal, and the savings are real money back in your pocket.

    Strategy #5: Optimize Your Charitable Giving Strategy

    If you’re already giving to charity, you might as well maximize the tax benefits. Two strategies can significantly boost your deductions.

    Bunching donations means concentrating multiple years of charitable giving into one tax year. Instead of giving $5,000 annually, give $15,000 every three years. This pushes you over the standard deduction threshold so you can itemize and capture the full write-off.

    Donating appreciated assets is even more powerful. If you have stocks, real estate, or other investments that have gained value over more than a year, donate them directly to charity. You deduct the full current market value and avoid paying capital gains tax. It’s like getting a tax deduction for money you never actually spent.

    For business owners, don’t forget about deducting the employer portion of your self-employment tax. This alone can save nearly $1,000 on an $80,000 income.

    image_3

    The Bottom Line: Take Action Before December 31st

    Here’s the thing that trips up most people – timing matters. Many of these strategies only work if you implement them before the tax year ends. You can’t decide in April to max out last year’s 401(k) contributions or bunch your charitable donations.

    Your action plan:

    • Review your current retirement contributions and increase them if possible
    • Check if you qualify for any of the new 2025 deductions
    • Calculate whether the expanded SALT deduction makes itemizing worthwhile
    • Set up or maximize HSA and FSA contributions for next year
    • Plan any major charitable donations before December 31st

    The wealthy didn’t get that way by paying more taxes than legally required. They use every legitimate strategy available to keep more of their money working for them instead of funding government programs.

    These five strategies alone could easily save you $10,000 or more annually. But here’s what’s even better – this is just the beginning. There are dozens of additional strategies, tax credits, and wealth-building techniques that most people never discover.

    Ready to Stop Overpaying Taxes and Start Building Real Wealth?

    You don’t have to navigate this alone. The team at MAKE WEALTH REAL has helped thousands of families implement these exact strategies and discover even more ways to keep their money working for them.

    Our wealth-building membership gives you access to tax professionals, financial strategists, and a proven system for building generational wealth – not just saving on taxes.

    Join the MAKE WEALTH REAL membership today and discover how to legally minimize your taxes while maximizing your wealth-building potential. Your future self will thank you for taking action today instead of waiting until next tax season to wish you’d done something different.


    Tweet Draft for Sonny: “Stop overpaying taxes! 🛑 New 2025 deductions could save you $10K+: ✅ $25K tips deduction ✅ Overtime now deductible ✅ SALT cap raised to $40K ✅ Senior $6K bonus deduction Ready to keep more of YOUR money? 💰 Link in bio #TaxStrategy #KeepYourMoney #MWRFinancial”

    Sonny – please post this tweet to promote the new blog post on our social channels.