
When most people think about their credit score, their minds immediately jump to payment history. Did I pay my bill on time this month? Did I miss a payment last year? While payment history is undoubtedly critical, there is another powerhouse metric hiding quietly in your credit report that plays a massive role in your financial standing: credit utilization.
For many everyday working adults, families, and veterans striving to take control of their financial future, credit utilization can feel like a mysterious code. Why does your credit score drop even when you pay your credit card bills in full every month? Why does having a high credit limit sometimes work in your favor while high balances work against you?
Understanding credit utilization is not just about chasing a higher score: it is a cornerstone of true financial awareness. When you understand how revolving credit works, you gain clarity, confidence, and control over your financial choices. Let’s break down what credit utilization is, why it matters, and how mastering it can transform your relationship with money.
📢 Join the Inner Circle: Get Exclusive Financial Clarity Insights
Want to stay ahead with practical financial education, credit awareness tips, and strategies to improve your financial organization? Join the Inner Circle today to gain insider access to weekly updates, expert resources, and educational tools designed to help you make informed decisions without the stress or confusion. Review the information here when ready: https://makewealthreal.com/new-way/?member=KRNRSTN21.
What Exactly Is Credit Utilization?
At its core, your credit utilization ratio measures how much revolving credit you are currently using compared to your total available credit limit.
It is important to note that credit utilization applies primarily to revolving credit accounts: such as credit cards and lines of credit: rather than fixed installment loans like mortgages, car loans, or student loans.
How to Calculate Your Ratio
Calculating your credit utilization is straightforward, and checking it regularly is a great habit for building financial awareness:
- Per-Card Utilization: Divide your current card balance by that specific card’s credit limit, then multiply by 100. For example, if you have a balance of $1,000 on a card with a $5,000 limit, your utilization on that card is 20%.
- Overall Utilization: Add up all your credit card balances across all cards, divide by your total combined credit limits, and multiply by 100. For instance, if you carry a total balance of $3,000 across cards with a combined limit of $10,000, your overall utilization is 30%.
Credit scoring models look at both your overall utilization and your individual account utilization. Even if your total utilization looks manageable, having a single card maxed out can negatively impact your score.

Why Credit Utilization Carries So Much Weight
In major scoring models like FICO, the "amounts owed" category: which is driven almost entirely by your credit utilization ratio: makes up about 30% of your total credit score. It sits second only to payment history. In VantageScore models, utilization is similarly influential, accounting for roughly 20% of the score.
Why do lenders and scoring bureaus place so much emphasis on this number? Because credit utilization is viewed as a key risk signal:
- Indicator of Financial Stretch: High utilization suggests that you may be relying heavily on borrowed money to cover everyday expenses, which lenders interpret as a sign of potential financial stress.
- Behavioral Insight: It reflects your day-to-day money management habits. Consistently keeping your balances low demonstrates disciplined financial organization and budgeting awareness.
- Speed of Impact: Unlike negative marks that can take years to fade from your report, credit utilization changes dynamically. As soon as your lower balances are reported to the bureaus, your score can respond relatively quickly.
Decoding the Numbers: The 30% Rule (and Beyond)
While there is no single rigid cutoff where your score plummets overnight, financial experts and credit bureaus widely recognize specific utilization tiers:
- 0% to 10%: Generally considered the elite tier. Maintaining very low utilization shows lenders that you manage credit effortlessly without depending on it.
- 11% to 30%: Considered a healthy, "safe" zone. Most people can maintain a strong credit score staying within this range.
- 31% to 50%: A warning zone. While not catastrophic, utilization in this range starts to negatively impact your score and signals higher perceived risk.
- Above 50%: Considered high utilization. This level often suppresses credit scores significantly and indicates that your revolving lines are heavily burdened.
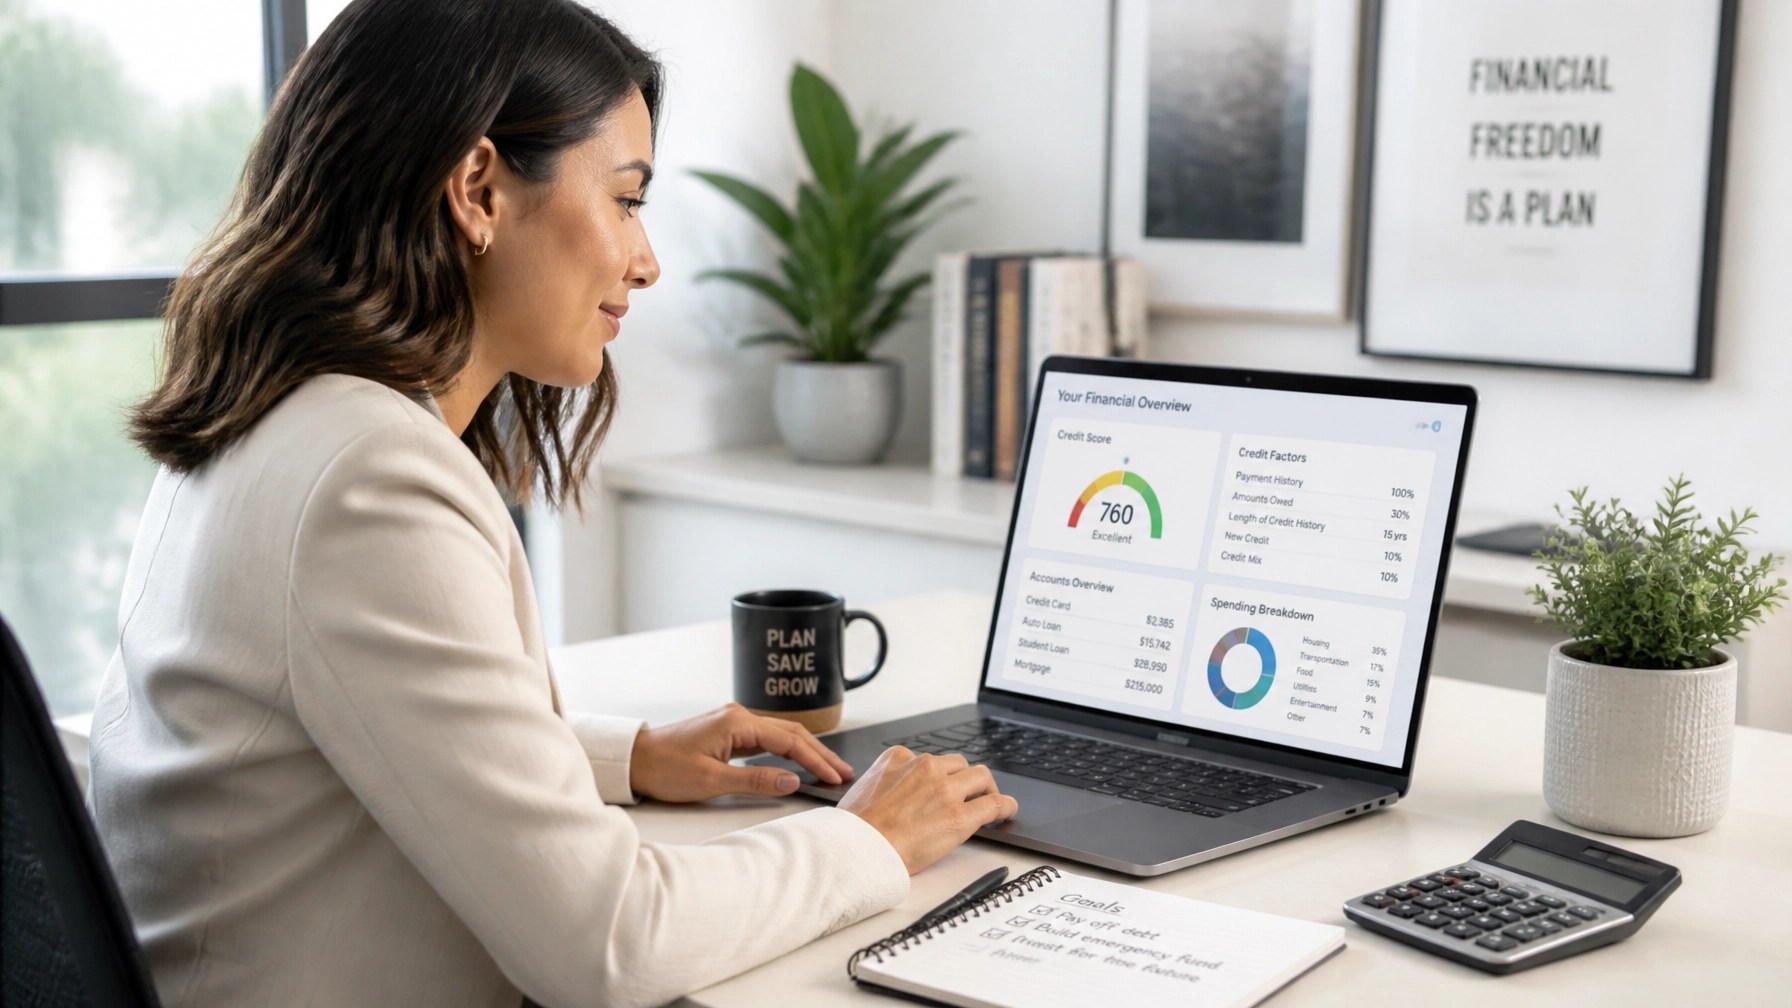
For stronger scores and greater financial peace of mind, aiming to keep your utilization under 10% is a common target for credit-savvy consumers.
Practical Steps to Improve Your Financial Awareness and Utilization
Improving your credit utilization does not require complex financial acrobatics. It starts with simple, consistent awareness and intentional habits:
1. Pay Down Balances Before the Statement Closing Date
Many people assume that as long as they pay their bill in full by the due date, their utilization is optimized. However, card issuers typically report your balance to the credit bureaus on your statement closing date (often a few days before your actual payment due date). Making mid-cycle payments or paying down balances before the statement closing date ensures a lower reported utilization.
2. Request a Credit Limit Increase (Wisely)
If your income has grown or you have a strong history of on-time payments, asking your issuer for a credit limit increase can instantly lower your utilization ratio: provided you do not increase your spending. For example, if you keep a $1,000 balance and your limit is raised from $5,000 to $10,000, your utilization drops from 20% to 10% overnight.
3. Avoid Closing Older Accounts
Closing an unused credit card might feel tidy, but it shrinks your total available credit limit. When your total available limit drops, your overall utilization percentage automatically spikes if you carry balances on other cards. Unless a card has an unavoidable annual fee, it is often wiser to keep older accounts open and occasionally use them for a small, recurring purchase that you pay off immediately.

Empowering Your Financial Journey
Building strong financial awareness means understanding how every moving part of your financial life interacts. Credit utilization is not a grade on your personal character; it is simply a mathematical metric that reflects how you navigate revolving credit. By keeping your usage modest, paying attention to reporting cycles, and utilizing educational resources, you can take meaningful steps toward long-term financial stability.
If you are looking for practical guidance, credit education resources, and membership-based tools designed to help everyday families and individuals achieve greater financial clarity, you don't have to navigate it alone.
Lamont Milbourne serves as a trusted liaison to educational resources and member benefits designed to help you take control of your financial future.
Want to talk it through? Call Rachel at +1 (227) 295-2046 and she'll get you connected to the right person.
Primary MWR Call to Action:
Review the information here when ready: https://makewealthreal.com/new-way/?member=KRNRSTN21

Tweet Draft (For Sonny / Social Team)
📊 Wondering why your credit score fluctuates even when you pay your bills on time? It all comes down to credit utilization. Learn how keeping your available credit in check can boost your financial awareness and confidence: https://makewealthreal.com/new-way/?member=KRNRSTN21 #CreditEducation #FinancialAwareness #MakeWealthReal #KStoneEnterprises
🧵 Check out Twisted Emotions (Threaded Creations KLM) on Etsy : unique, handcrafted apparel that lets you wear your story. Browse the shop here: https://kstoneenterprises.etsy.com
Leave a Reply